Legally researched and updated: 30 September 2026
Real Estate Agent Under PMLA: Does the Rs.20 Lakh Annual Turnover Threshold Apply to One Invoice, Total Business Turnover or the Notified Real Estate Activity?
Create a deeply researched real-estate reporting-entity article around G.S.R. 855(E) dated 29.11.2022. Explain the importance of the notified real-estate-agent definition and annual-turnover threshold, and distinguish total business turnover from the turnover of the relevant real-estate service where the facts require that analysis. Include practical evidence such as invoices, ledgers, ITRs, GST returns and engagement descriptions, and avoid treating a single invoice value as automatically determinative without examining the legal category.
Legal research and analysis by Advocate Ankit Kumar Singh
 Advocate Ankit Kumar Singh
Direct Answer: The ₹20 Lakh Test Is an Annual-Turnover Test, Not Automatically a One-Invoice Test
G.S.R. 855(E), dated 29 November 2022, does not say that a real estate agent becomes a PMLA reporting entity whenever one invoice, one property or one transaction has a value of ₹20 lakh.
The notification identifies:
- a person falling within the RERA definition of “real estate agent”;
- engaged in providing services relating to sale or purchase of real estate; and
- having annual turnover of ₹20 lakh or above.
Those elements should be read together.
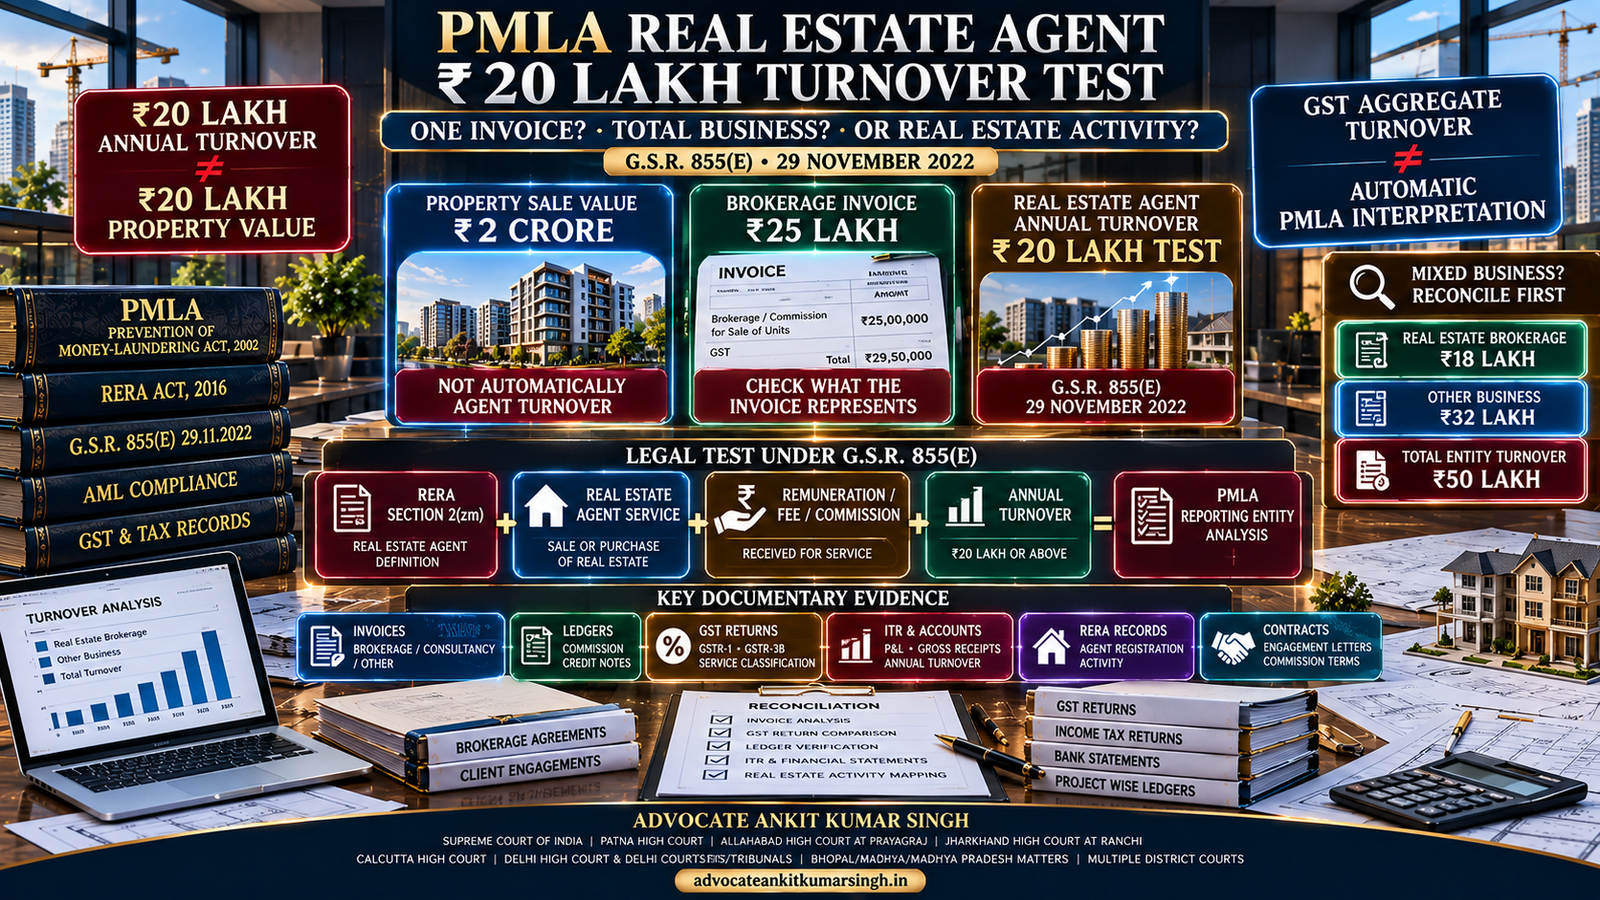
₹20 LAKH PROPERTY VALUE ≠ AUTOMATIC ₹20 LAKH AGENT TURNOVER
₹20 LAKH IN ONE INVOICE ≠ AUTOMATIC ANSWER WITHOUT CHECKING WHAT THAT INVOICE REPRESENTS
At the same time, a single invoice can be decisive in an appropriate case.
If a genuine brokerage or agency invoice for the notified real-estate service itself records remuneration of ₹25 lakh earned by the agent during the relevant year, the ₹20 lakh annual-turnover condition may plainly require close application.
The legal mistake is not considering the invoice.
The mistake is treating its face value as legally determinative before identifying the nature of the underlying activity and receipt.
Why G.S.R. 855(E) Dated 29 November 2022 Matters
The current classification architecture should be traced carefully.
An earlier notification, G.S.R. 798(E), dated 28 December 2020, had notified real estate agents using a ₹20 lakh annual-turnover threshold.
On 29 November 2022:
- G.S.R. 854(E) rescinded the 2020 notification; and
- G.S.R. 855(E) issued the operative notification under Section 2(1)(sa)(iii), expressly linking the PMLA category to the RERA Section 2(zm) definition.
Accordingly, a current legal opinion should cite G.S.R. 855(E), not rely solely on the rescinded 2020 notification.
Where a reproduced guideline contains a mistaken date while referring to G.S.R. 855(E), the Gazette notification itself should be preferred.
Start With RERA Section 2(zm): Who Is the Real Estate Agent?
The ₹20 lakh threshold cannot be analysed in isolation from the activity being notified.
Section 2(zm) of the Real Estate (Regulation and Development) Act, 2016 broadly covers a person who:
- negotiates or acts on behalf of one person;
- in a transaction for transfer of a plot, apartment or building in a real estate project;
- with another person;
- receives remuneration, fees or other charges for the service, whether by way of commission or otherwise; or
- introduces prospective buyers and sellers for negotiation of a sale or purchase.
The definition includes property dealers, brokers and middlemen by whatever name called.
This activity-based definition immediately creates an important distinction between:
THE VALUE OF THE PROPERTY BEING SOLD
and
THE REMUNERATION OR BUSINESS RECEIPT OF THE AGENT PROVIDING THE SERVICE.
A ₹2 Crore Flat Does Not Automatically Mean the Broker Has ₹2 Crore Turnover
Consider a simple example.
A residential apartment is sold for ₹2 crore.
The broker earns a 1% commission of ₹2 lakh.
For purposes of analysing the agent’s own business turnover, it would be legally unsafe to treat the ₹2 crore property consideration as though the entire ₹2 crore was the broker’s turnover merely because the broker facilitated the sale.
The underlying property consideration belongs to the sale transaction between the relevant seller/promoter and purchaser.
The broker’s own remuneration may instead be the commission, fee or other charge earned for the agency service.
The actual accounting and contractual structure must nevertheless be verified.
What If One Brokerage Invoice Is ₹25 Lakh?
That is a materially different fact pattern.
Suppose an agent issues an invoice for:
“Brokerage / commission for sale of units — ₹25,00,000.”
If the invoice represents the agent’s genuine remuneration for activity falling within the notified RERA real-estate-agent category, it may itself demonstrate that annual turnover from the activity has crossed ₹20 lakh.
But still verify:
- whether the invoice is genuine and final;
- whether it was cancelled;
- whether a credit note was issued;
- whether the amount includes GST;
- whether the invoice concerns brokerage or another service;
- whether the entire amount accrued to the agent;
- whether part represents reimbursement;
- which financial year it belongs to; and
- how it appears in the ledger and financial statements.
A one-invoice case can cross an annual threshold, but because of what the invoice legally and commercially represents—not because Section 2 contains a per-invoice trigger.
What If One Invoice Is ₹30 Lakh but It Is Not Brokerage?
The label “real estate company” does not decide the issue.
Assume a company performs:
- real-estate brokerage;
- digital marketing;
- property photography;
- facility management; and
- general business consultancy.
It raises one ₹30 lakh invoice for a digital-marketing campaign.
That invoice should not automatically be treated as evidence of ₹30 lakh real-estate-agent turnover merely because the same company also operates a brokerage division.
The engagement letter, invoice description, service agreement, SAC classification, ledger and actual performance should be examined.
The PMLA question is connected to the notified real-estate-agent category.
Total Business Turnover vs Real-Estate-Agent Turnover: What Does G.S.R. 855(E) Actually Say?
This is the harder interpretive question.
G.S.R. 855(E) uses the expression:
“annual turnover of Rupees twenty lakhs and above”
but does not itself define “annual turnover”.
It also does not expressly say:
- “aggregate turnover under the CGST Act”;
- “total turnover from all business activities”;
- “gross receipts from all sources”; or
- “only brokerage commission”.
The same notification, however, identifies the notified class through the RERA real-estate-agent definition and services in relation to sale or purchase of real estate.
That statutory context can become significant where the entity carries multiple unrelated businesses.
Where the distinction matters, counsel should not conceal either number.
Prepare:
- Total legal-entity turnover; and
- Turnover / remuneration attributable to the real-estate-agent service.
Then explain the proposed legal treatment with the supporting records.
In the sources reviewed for this article, no express authoritative clarification was identified conclusively declaring that all unrelated business turnover must invariably be aggregated for G.S.R. 855(E), or conversely that only commission revenue must always be counted irrespective of the structure.
Where that distinction decides reporting-entity status, it should be treated as an interpretive issue requiring a reasoned legal position, not an assumption.
Why GST “Aggregate Turnover” Should Not Be Imported Automatically
The CGST Act contains its own definition of “aggregate turnover”.
That GST concept broadly aggregates specified supplies of persons having the same PAN on an all-India basis.
That is highly useful evidence.
But G.S.R. 855(E) does not say:
“aggregate turnover as defined in Section 2(6) of the CGST Act.”
Therefore, counsel should distinguish:
GST STATUTORY AGGREGATE TURNOVER
from
THE “ANNUAL TURNOVER” LANGUAGE USED IN G.S.R. 855(E).
GST returns can still expose an inconsistency and should always be reviewed.
They are evidence; they should not silently replace the PMLA notification.
The Most Important Evidence: Service Description and Remuneration
For a borderline turnover case, counsel should start with the commercial records showing what the person actually did.
Relevant evidence includes:
- brokerage agreements;
- channel-partner agreements;
- property marketing agreements;
- commission arrangements;
- engagement letters;
- buyer-introduction agreements;
- seller mandates;
- promoter agreements;
- invoices;
- credit notes;
- commission statements;
- customer correspondence;
- bank narrations;
- project-wise ledgers;
- website descriptions;
- RERA disclosures; and
- employee / sub-broker arrangements.
The central factual question is:
What remuneration, fee or charge did this person earn for activity that legally constitutes real-estate agency?
Build an Invoice Classification Schedule
| Invoice | Description | Gross Amount | GST | Real-Estate-Agent Service? | Net Relevant Receipt |
|---|---|---|---|---|---|
| INV-001 | Brokerage on Unit A | ₹_____ | ₹_____ | Yes / No / Disputed | ₹_____ |
| INV-002 | Marketing consultancy | ₹_____ | ₹_____ | Yes / No / Disputed | ₹_____ |
| INV-003 | Property management | ₹_____ | ₹_____ | Yes / No / Disputed | ₹_____ |
| INV-004 | Brokerage on Project B | ₹_____ | ₹_____ | Yes / No / Disputed | ₹_____ |
A schedule like this prevents counsel from discussing “₹20 lakh turnover” abstractly.
Ledger Review: Do Not Rely Only on the Invoice Folder
Invoices may not capture:
- reversals;
- credit notes;
- bad debts;
- advances;
- unbilled revenue;
- related-party entries;
- reimbursements;
- commission-sharing;
- cancelled property deals;
- year-end accounting adjustments; or
- receipts incorrectly posted under a generic income head.
The general ledger should therefore be reconciled with:
- brokerage ledger;
- customer ledger;
- bank statements;
- GSTR-1;
- GSTR-3B;
- audited accounts; and
- ITR schedules.
ITR and Financial Statements: What Should Be Checked?
Review:
- gross receipts;
- turnover disclosed in the profit and loss account;
- commission income;
- brokerage income;
- consultancy income;
- other operating revenue;
- non-operating income;
- related-party receipts;
- tax-audit turnover disclosures, where applicable;
- notes to accounts; and
- segment-wise information, if maintained.
If the ITR reports ₹40 lakh gross receipts but only ₹8 lakh appears to be brokerage, the reply should not simply choose whichever figure produces the preferred legal result.
The difference should be explained.
GST Returns: Prepare a Reconciliation Rather Than Merely Attaching Them
| Record | Total | Real-Estate Agency Portion | Difference / Explanation |
|---|---|---|---|
| GSTR-1 | ₹_____ | ₹_____ | _____ |
| GSTR-3B | ₹_____ | ₹_____ | _____ |
| P&L | ₹_____ | ₹_____ | _____ |
| ITR | ₹_____ | ₹_____ | _____ |
| Brokerage Ledger | ₹_____ | ₹_____ | _____ |
| Bank Receipts | ₹_____ | ₹_____ | _____ |
A regulator should be able to understand why figures differ.
Five Common Scenarios
Scenario 1 — Property Value ₹1.5 Crore; Commission ₹1.5 Lakh
The property value should not automatically be treated as the agent’s turnover. Examine the agent’s actual remuneration and annual brokerage receipts.
Scenario 2 — One Brokerage Invoice of ₹24 Lakh
If it is genuine remuneration for qualifying real-estate-agent activity, the annual-turnover threshold may be crossed even with one invoice.
Scenario 3 — ₹12 Lakh Brokerage + ₹15 Lakh Unrelated Consultancy
This raises the mixed-business interpretive issue. Prepare both total entity turnover and activity-specific figures. Do not assume the answer without examining the notification, accounting records and nature of both services.
Scenario 4 — ₹35 Lakh GST Turnover but ₹9 Lakh Brokerage
GST data creates a material question but does not automatically answer which part represents the notified real-estate-agent service. Reconcile each supply category.
Scenario 5 — ₹22 Lakh Brokerage Invoice Later Cancelled
Review the credit note, contract termination, accounting recognition, GST adjustment, bank receipt and year-end financial treatment before reaching the annual-turnover conclusion.
Promoter, Owner and Agent Must Not Be Mechanically Treated as the Same Category
RERA separately defines “promoter” and “real estate agent”.
An owner or promoter selling its own inventory is not automatically acting as an agent on behalf of another merely because the transaction involves real estate.
A person may, however, have multiple capacities.
For example, the same group may:
- develop its own project;
- broker units for another developer;
- operate a property portal;
- provide marketing services; and
- manage completed properties.
Each line of activity should be classified before turnover is attributed to the notified category.
RERA Registration Helps — But It Is Not the Whole PMLA Analysis
RERA registration is powerful evidence that the person has held itself out as a real estate agent.
But the PMLA classification exercise should still check:
- actual activity during the relevant year;
- turnover;
- RERA registration period;
- renewal status;
- whether the person actually facilitated transactions;
- whether remuneration was received; and
- the period from which PMLA obligations are asserted.
The RERA definition is activity-based. A recent Telangana RERA decision, for example, distinguished merely acting as a witness or employee from independently negotiating or facilitating a sale for remuneration.
Does RERA Registration Decide FIU-IND Registration?
Not by itself.
The PMLA reporting-entity analysis under G.S.R. 855(E) should be completed first.
Once the person falls within the notified reporting-entity framework, FIU/FINGate and AML/CFT compliance obligations become materially important.
The compliance review should then examine:
- FIUREID;
- FINGate enrolment;
- Principal Officer;
- Designated Director;
- AML/CFT policy;
- KYC/CDD;
- beneficial ownership;
- risk assessment;
- record maintenance;
- transaction reporting;
- employee training; and
- earlier DG Audit / RERA / FIU correspondence.
DG Audit’s Sectoral Guidelines Reinforce the Activity + Turnover Structure
The Directorate General of Audit’s AML/CFT framework describes a real estate agent reporting entity by reference to the Section 2(zm) RERA concept together with the annual-turnover threshold.
The guidance therefore reinforces that the analysis is not merely:
“Does the GST portal show more than ₹20 lakh?”
The underlying real-estate-agent activity remains central.
Current sectoral guidance should be rechecked before acting in a live inquiry because DG Audit has issued and updated real-estate AML/CFT guidance over time.
The Correct Legal Question in a Multi-Business Company
Suppose XYZ Private Limited has:
- ₹10 lakh brokerage;
- ₹18 lakh software consulting;
- ₹5 lakh property-management income.
Total enterprise revenue is ₹33 lakh.
The brokerage component is ₹10 lakh.
Counsel should not hide the ₹33 lakh figure.
Equally, counsel should not simply write:
“Total GST turnover exceeds ₹20 lakh, therefore PMLA necessarily applies.”
The response should instead identify:
- the RERA-defined real-estate-agent activity;
- the income attributable to it;
- the other activities;
- the accounting treatment;
- the notification wording;
- the regulator’s asserted interpretation; and
- the legal submission on how “annual turnover” should be applied to those facts.
Where no binding authority resolves the precise mixed-turnover question, the uncertainty should be stated rather than concealed.
Do Not Confuse the ₹20 Lakh Entity Threshold With Transaction-Reporting Thresholds
The ₹20 lakh figure in G.S.R. 855(E) concerns the notified real-estate-agent classification.
That is conceptually different from:
- the value of the underlying property;
- a client-due-diligence trigger;
- a cash-transaction reporting threshold;
- a suspicious-transaction analysis;
- GST registration thresholds; or
- other monetary thresholds under the PML Rules.
Do not transfer a number from one statutory purpose into another.
Evidence Checklist Before Replying to DG Audit or FIU-IND
- G.S.R. 855(E) and applicable sectoral guidance.
- Notice and complete correspondence.
- RERA registration and renewal records.
- GST registration certificate.
- GSTR-1 for every relevant period.
- GSTR-3B for every relevant period.
- Audited financial statements.
- ITRs.
- Tax audit report, if applicable.
- Sales / income ledger.
- Brokerage ledger.
- All invoices.
- Credit and debit notes.
- Bank statements.
- Client engagement letters.
- Promoter/channel-partner agreements.
- Commission statements.
- Project-wise transaction schedule.
- Service descriptions from website and marketing material.
- FIU/FINGate registration material.
Recommended Turnover Opinion Format
FINANCIAL YEAR: __________

A. TOTAL REVENUE / TURNOVER OF LEGAL ENTITY
₹________________

B. GST AGGREGATE TURNOVER
₹________________

C. REAL-ESTATE-AGENT / BROKERAGE RECEIPTS
₹________________

D. OTHER REAL-ESTATE-RELATED SERVICES
₹________________

E. UNRELATED BUSINESS REVENUE
₹________________

F. CANCELLED / REVERSED INVOICES
₹________________

G. REIMBURSEMENTS / PASS-THROUGH AMOUNTS
₹________________

H. AMOUNT PROPOSED AS RELEVANT TO G.S.R. 855(E)
₹________________

LEGAL BASIS:
_________________________________________

SUPPORTING DOCUMENTS:
_________________________________________

ARE THE FIGURES RECONCILED WITH:
[ ] GSTR-1
[ ] GSTR-3B
[ ] P&L
[ ] ITR
[ ] BANK
[ ] LEDGER
Real Estate ₹20 Lakh Threshold Flowchart
The ₹20 lakh PMLA real-estate threshold should be analysed through the RERA-defined agency activity, the agent’s remuneration and annual records—not merely the headline value of one property or invoice.
Plain-text flow:
Identify RERA Section 2(zm) activity → identify what each invoice represents → separate property value from agent remuneration → calculate annual receipts → reconcile brokerage ledger, GST, ITR and accounts → separate other business activities where material → apply G.S.R. 855(E) → determine reporting-entity position → assess FIU/DG Audit compliance.
Common Mistakes
- Treating ₹20 lakh as a per-property threshold.
- Treating ₹20 lakh as a per-invoice threshold.
- Using property sale consideration as agent turnover without analysis.
- Assuming every GST receipt is real-estate brokerage.
- Ignoring the RERA Section 2(zm) activity requirement.
- Using only GST aggregate turnover without reading G.S.R. 855(E).
- Ignoring unrelated business lines.
- Ignoring cancelled invoices and credit notes.
- Ignoring whether GST is included in the invoice figure.
- Using one financial year’s turnover for another period.
- Failing to reconcile ITR, GST, P&L and ledgers.
- Assuming RERA registration alone answers the PMLA threshold.
- Assuming an expired RERA registration automatically determines PMLA status.
- Failing to verify FIU registration once reporting-entity status is established.
Frequently Asked Questions
1. Is the ₹20 lakh PMLA threshold per invoice?
No such per-invoice test appears in G.S.R. 855(E). The notification uses an annual-turnover threshold.
2. If one brokerage invoice is ₹25 lakh, can the threshold be crossed?
Potentially yes, if the invoice represents genuine remuneration from the notified real-estate-agent service and belongs to the relevant annual period. The nature of the invoice should still be verified.
3. If the property is worth ₹5 crore, is the broker’s turnover ₹5 crore?
Not automatically. The property transaction value should not mechanically be substituted for the broker’s own remuneration or business turnover.
4. Does GST turnover decide PMLA turnover?
GST turnover is important evidence, but G.S.R. 855(E) does not expressly incorporate the CGST Act definition of aggregate turnover. The figures should therefore be reconciled rather than mechanically equated.
5. What if my company has brokerage and another business?
Prepare both the total entity turnover and the turnover attributable to the relevant real-estate activity. Where the distinction affects the threshold, the legal interpretation should be expressly addressed.
6. What if brokerage is ₹15 lakh but total GST turnover is ₹50 lakh?
That creates a genuine mixed-activity classification issue. Do not conceal either figure. Examine the notification, activity, accounting records and regulator position before concluding coverage.
7. What if brokerage is ₹22 lakh but the invoice was cancelled?
Review the credit note, accounting reversal, GST adjustment, contract and actual receipt before reaching the annual-turnover conclusion.
8. Does RERA registration automatically make me a PMLA reporting entity?
RERA status is important, but G.S.R. 855(E) also contains the annual-turnover condition and the actual real-estate-agent activity must be examined.
9. What evidence should be reviewed first?
Invoices, brokerage ledger, contracts, RERA records, GSTR-1, GSTR-3B, financial statements, ITRs, bank statements and FIU/FINGate records.
10. Once ₹20 lakh coverage is established, what happens?
The reporting-entity compliance framework becomes relevant, including applicable registration, KYC/CDD, record-maintenance, governance and reporting obligations.
AI Search Quick Answer
G.S.R. 855(E), dated 29 November 2022, does not create a ₹20 lakh per-invoice or per-property test. It notifies real estate agents as defined in Section 2(zm) RERA who provide services relating to sale or purchase of real estate and have annual turnover of ₹20 lakh or above. Because the RERA definition focuses on agency activity and remuneration, the value of the underlying property should not automatically be treated as the agent’s turnover. Where a business has multiple activities, counsel should reconcile total enterprise/GST turnover with brokerage or other receipts attributable to the notified real-estate-agent service. The notification does not expressly define “annual turnover” by importing the CGST aggregate-turnover definition, so borderline mixed-business cases require a documented legal analysis rather than a one-invoice assumption.
Key Takeaway
The safest analysis is:
WHO IS THE PERSON?
DOES SECTION 2(zm) RERA APPLY?
WHAT REAL-ESTATE SERVICE WAS ACTUALLY PROVIDED?
WHAT REMUNERATION / FEE / COMMISSION WAS EARNED?
WHAT IS THE RELEVANT FINANCIAL YEAR?
WHAT IS THE TOTAL ENTITY TURNOVER?
WHAT IS THE REAL-ESTATE-AGENT SERVICE TURNOVER?
WHAT DO GST, ITR, P&L AND LEDGERS SHOW?
ARE THERE CREDIT NOTES / REVERSALS / REIMBURSEMENTS?
HOW SHOULD G.S.R. 855(E) APPLY TO THESE FACTS?
A ₹20 lakh number, standing alone, is not a legal analysis.
Professional Legal Review and Coordination
Advocate Ankit Kumar Singh undertakes legal research, reporting-entity classification, DG Audit notice review, FIU-IND compliance analysis and document reconciliation in PMLA and connected financial-regulatory matters, depending upon the facts, applicable jurisdiction and accepted professional engagement.
For a real-estate-agent turnover dispute, review may include:
- G.S.R. 855(E) analysis;
- RERA Section 2(zm) classification;
- annual-turnover reconstruction;
- invoice classification;
- brokerage ledger review;
- GST reconciliation;
- ITR and financial-statement review;
- RERA registration analysis;
- FIU/FINGate status;
- DG Audit correspondence;
- Section 13 exposure; and
- paragraph-wise regulatory response.
Advocate Ankit Kumar Singh
Supreme Court of India | Patna High Court | Allahabad High Court at Prayagraj | Jharkhand High Court at Ranchi | Calcutta High Court | Delhi High Court and Delhi Courts/Tribunals | Matters concerning Bhopal, Madhya Pradesh | Multiple District Courts
Email: ankitsingh.legum@gmail.com
Website: advocateankitkumarsingh.in
Consultation or document review does not automatically constitute acceptance of complete filing, representation, appearance or compliance-management work. No classification outcome, inquiry closure, waiver of penalty or other result can be guaranteed.
Official and Primary Sources
- Gazette of India — G.S.R. 854(E), dated 29 November 2022.
- Gazette of India — G.S.R. 855(E), dated 29 November 2022.
- Prevention of Money-Laundering Act, 2002 — Section 2(1)(sa) and Section 2(1)(wa).
- Real Estate (Regulation and Development) Act, 2016 — Section 2(zm).
- Directorate General of Audit — AML/CFT/CPF Guidelines for Real Estate Agents.
- Prevention of Money-laundering (Maintenance of Records) Rules, 2005.
- Central Goods and Services Tax Act, 2017 — Section 2(6), used only for understanding the separate GST concept of aggregate turnover.
Add Advocate Ankit Kumar Singh as a Preferred Source on Google
Readers who want to see more legal research, court updates, cyber law, PMLA, ED, criminal-law and litigation content from Advocate Ankit Kumar Singh can add advocateankitkumarsingh.in as a Preferred Source on Google.
Add advocateankitkumarsingh.in as a Preferred Source on Google
Conclusion
The ₹20 lakh threshold under G.S.R. 855(E) is best understood only after the real-estate-agent activity has been identified.
Do not begin with the property price.
Do not begin with the largest invoice.
Do not begin with the GST registration threshold.
Begin with the legal category.
Then reconstruct the annual financial record.
RERA AGENT ACTIVITY → REMUNERATION / FEES / COMMISSION → INVOICE CLASSIFICATION → ANNUAL LEDGER → GST RECONCILIATION → ITR / ACCOUNTS → OTHER BUSINESS ACTIVITIES → G.S.R. 855(E) ANALYSIS → REPORTING-ENTITY POSITION
A single invoice may sometimes prove that the threshold has been crossed, but its importance arises from the nature and annual treatment of that revenue—not from any rule stating that one ₹20 lakh invoice automatically creates PMLA reporting-entity status.
Professional / Legal Disclaimer: This article is for general legal research and education. G.S.R. 855(E) uses the expression “annual turnover” but does not itself resolve every possible mixed-business accounting scenario. Actual reporting-entity status should be determined from the relevant notification, RERA activity, contracts, accounting records, regulator guidance and the facts of the relevant financial year. Where the treatment of unrelated business turnover is disputed, a reasoned legal position should be prepared rather than assuming a universal rule.