DELHI ED | PMLA | CYBER-FRAUD INVESTIGATION | SHELL COMPANIES | 2026
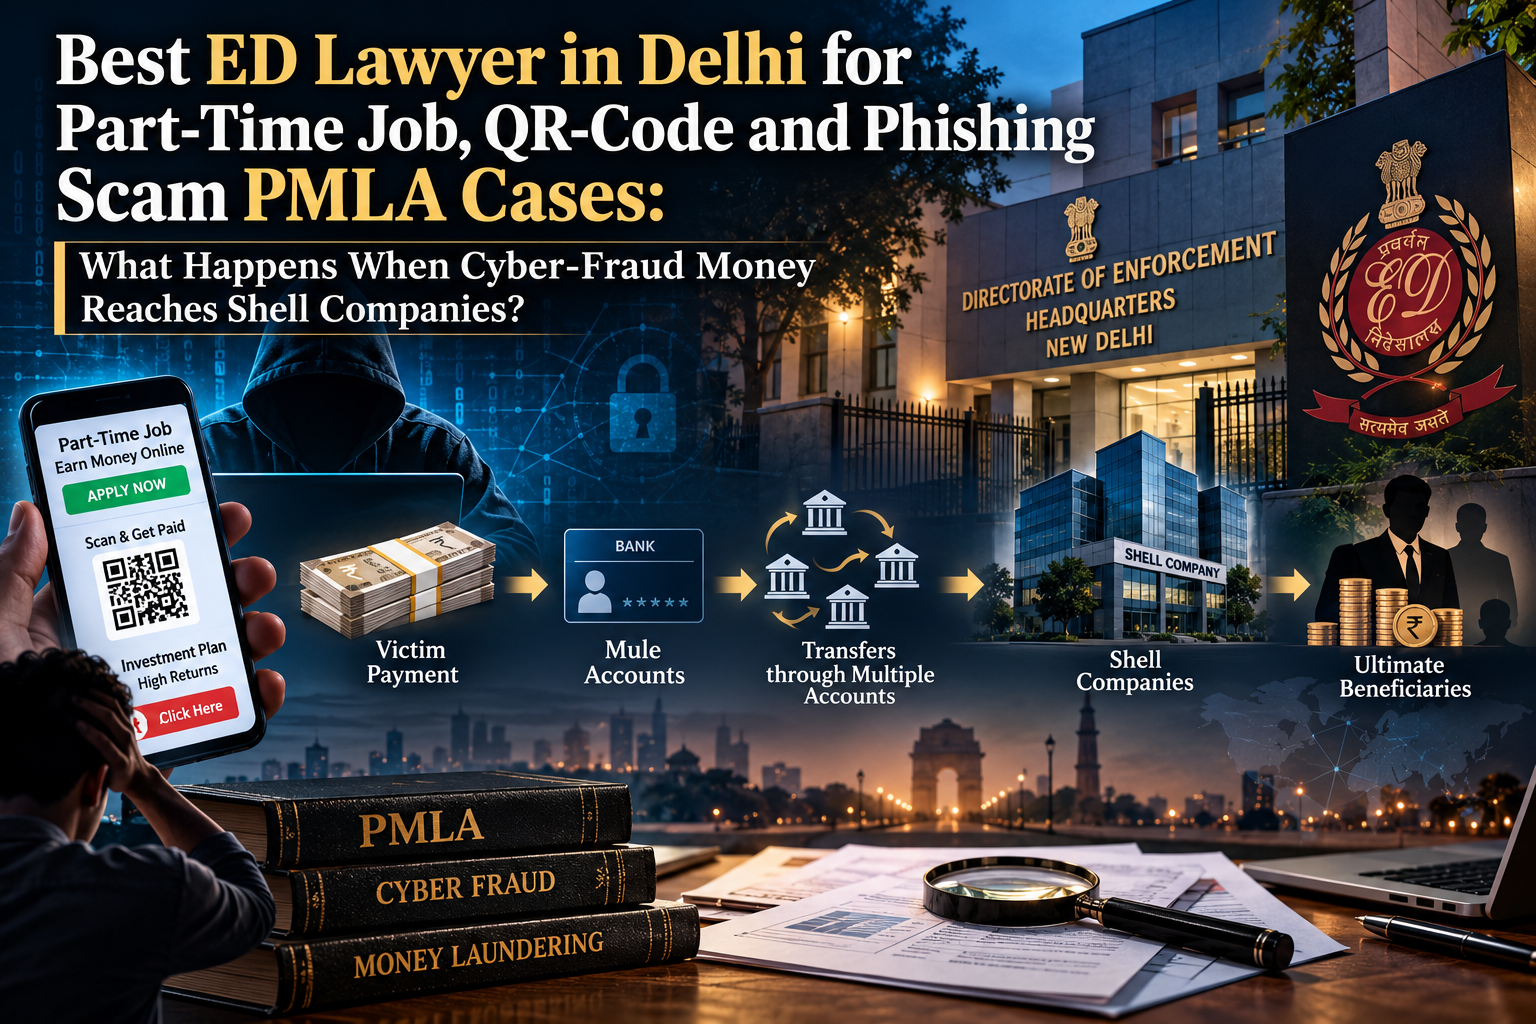
Best ED Lawyer in Delhi for Part-Time Job, QR-Code and Phishing Scam PMLA Cases: What Happens When Cyber-Fraud Money Reaches Shell Companies?
Legal Research and Analysis by: Advocate Ankit Kumar Singh
Published: 9 October 2026
Legal Focus: Enforcement Directorate Headquarters Unit, New Delhi; part-time job fraud; QR-code scams; phishing; mule bank accounts; interconnected companies; Chartered Accountants; directors; beneficial ownership; and proceeds of crime under the Prevention of Money-Laundering Act, 2002.
Research Note: The investigation described below is based principally on the Enforcement Directorate's official press release dated 5 March 2026. Investigative allegations are distinguished from judicial findings. Any subsequent orders or case developments must be verified from the relevant court record.
What Happens When Cyber-Fraud Money Reaches a Shell Company?
Direct Answer: When money allegedly obtained through part-time job scams, phishing or fraudulent QR-code payments reaches a company bank account, the Enforcement Directorate may examine whether the recipient company was carrying on genuine business or was being used to receive, transfer, conceal or otherwise deal with suspected proceeds of crime. The inquiry may extend to the company's directors, authorised signatories, Chartered Accountants, financial intermediaries and persons ultimately controlling or benefiting from the transactions.
However, a person does not become guilty of money laundering merely because their name appears in a company's incorporation documents or banking records. The statutory ingredients of the alleged offence and the evidence concerning that person's individual conduct remain essential.
A company director may have authorised particular transactions. An accountant may have prepared incorporation documents. An employee may have operated internet banking under instructions. A nominee director may have held a formal position without exercising practical control. Another individual may have directed the entire operation without appearing prominently in the company's records.
These circumstances require different factual and legal assessments.
The central question is not simply whether money passed through a suspected shell company. It is whether the available evidence establishes the relevant source of funds, the transactions undertaken, the actual persons exercising control and the involvement of each individual in any process or activity connected with proceeds of crime.
This distinction becomes particularly significant in large-scale investigations where money may travel through numerous accounts before being withdrawn, transferred overseas or converted into other assets.
The March 2026 ED Headquarters Investigation in New Delhi
On 5 March 2026, the Directorate of Enforcement issued an official press release concerning an investigation conducted by its Headquarters Unit in New Delhi.
According to the agency, the investigation concerned a substantial cyber-enabled financial fraud in which members of the public were allegedly induced to transfer funds through fraudulent investment opportunities, part-time employment schemes, QR-code scams, phishing operations and other deceptive digital arrangements.
The ED stated that approximately ₹641 crore in suspected cyber-fraud proceeds was initially credited into mule bank accounts managed or operated by persons associated with certain Telegram groups.
The funds were then allegedly routed through a network of dummy or shell entities across India, with the apparent objective of fragmenting the financial trail and obscuring the origin of the money.
The agency further reported that funds were transferred through Indian bank-issued debit cards to a UAE-based financial technology platform, PYYPL. According to the press release, money was subsequently withdrawn overseas or converted into virtual digital assets through a cryptocurrency exchange and transferred through multiple wallets.
The present analysis focuses primarily on the earlier and more legally significant question of how the initial victim payments reached the company accounts and how responsibility for those transactions may be attributed to specific individuals.
What Did the ED Report About the Companies in Delhi?
The agency alleged that a coordinated network comprising professionals and other individuals incorporated or controlled more than 20 interconnected entities operating from common addresses in Bijwasan, Delhi.
The ED referred to overlapping partners, authorised signatories, KYC documents, mobile numbers and email addresses. According to the agency, these features indicated common control and the use of entities as channels for transferring suspected illicit funds.
Overlapping corporate information may provide a legitimate basis for investigation. However, the evidentiary significance of each common address, bank mandate or authorised signatory must still be examined in context.
For example, several companies may share a registered office or professional service provider for legitimate reasons. Conversely, the same contact numbers, account operators and transaction instructions across several companies may become significant when considered alongside evidence of fraudulent financial activity.
Official Investigation Snapshot
| Particular | Information reported by ED |
|---|---|
| Investigating authority | Directorate of Enforcement, Headquarters Unit, New Delhi |
| Official press release | 5 March 2026 |
| Alleged fraud categories | Part-time job scams, fraudulent investments, QR-code scams and phishing |
| Reported suspected proceeds | Approximately ₹641 crore |
| Initial receiving accounts | Suspected mule bank accounts |
| Corporate entities | More than 20 interconnected entities reportedly operating from common addresses in Bijwasan, Delhi |
| Reported arrests on 28 February 2026 | Chartered Accountants Ashok Kumar Sharma and Bhaskar Yadav |
| Total arrests reported | 10 individuals as of 5 March 2026 |
| Provisional attachment | Two orders involving properties valued at approximately ₹8.67 crore |
| Prosecution complaints | Two complaints reportedly filed, with cognizance taken by the Special Court |
| Investigation status | Further investigation continuing as stated in the press release |
The agency also described searches carried out in November 2024 and subsequent proceedings involving anticipatory bail applications. The press release reported that the two Chartered Accountants were arrested on 28 February 2026 following their surrender.
Important Legal Distinction: An arrest, a rejected bail application, an attachment order or the filing of a prosecution complaint does not constitute a final conviction. The allegations and the liability of any individual must be assessed through the applicable judicial process.
Official Reference: Directorate of Enforcement, Headquarters Unit — Press Release dated 5 March 2026 (PDF).
How Part-Time Job, QR-Code and Phishing Scams Generate Financial Trails
Although these frauds use different methods of deception, the money obtained may subsequently travel through a similar banking and corporate network.
1. Part-Time Job and Online Task Scams
A fraudulent task-based employment arrangement may begin with a message offering earnings for simple online activities such as reviewing businesses, rating products or completing promotional assignments.
Small initial payments may create an impression of legitimacy. The victim may then be asked to deposit larger amounts under the pretext of unlocking tasks, increasing commissions, completing an investment cycle or withdrawing supposed earnings.
When the victim makes a payment, the money may be received in an account unrelated to the individual who communicated the employment offer.
Consequently, investigators must distinguish the person who induced the payment from the person who owned, operated or controlled the receiving account.
2. QR-Code and Payment-Redirection Fraud
QR-code fraud may involve deceptive payment instructions or misrepresentation of a merchant or payment recipient.
Investigators may examine the relevant UPI identifier, merchant account, transaction reference, beneficiary bank account and associated communications.
The existence of a QR-code transaction does not itself establish fraud. The surrounding representations, payment instructions, account control and financial consequences must be considered.
3. Phishing and Credential-Based Fraud
Phishing may involve fraudulent websites, impersonation messages or deceptive links intended to obtain confidential information or induce financial transfers.
Relevant evidence may include login records, device information, transaction authorisation, electronic communications and bank statements.
Where an account has been compromised, investigators may also need to distinguish the account holder from the person who obtained unauthorised access and executed the transaction.
Why the Distinction Matters Under PMLA
The original cybercrime and the alleged laundering of its proceeds are legally connected but distinct inquiries.
The person responsible for the initial deception may differ from the person handling the proceeds at a subsequent stage.
A proper financial reconstruction must therefore establish the relevant transactions without treating all persons appearing in the same network as having identical roles.
How Cyber-Fraud Proceeds May Move from Mule Accounts into Shell Companies
A large cyber-fraud investigation should be approached through a traceable chronology of transactions rather than an assumption that every credit, transfer or withdrawal represents a separate amount of criminal proceeds.
Stage 1: The Original Victim Payment
The starting point is the identifiable payment made by the victim.
The relevant records may include the complaint, originating bank account, transaction date, amount, UPI reference, merchant identifier and communications associated with the payment.
Where several victims are involved, each payment should be capable of being traced independently before the individual transactions are incorporated into a consolidated financial account.
Stage 2: Receipt into a Mule Bank Account
A mule account is generally understood as an account used to receive or transfer money for another person, sometimes in circumstances connected with fraud.
The registered account holder and the actual account operator may be different persons.
Investigators may therefore examine KYC documents, linked mobile numbers, internet-banking records, transaction devices, account-opening information and the circumstances in which account credentials were shared or obtained.
The evidentiary inquiry should determine whether the person knowingly permitted the account to be used, acted under particular instructions, had their account compromised or occupied some other position supported by the records.
Stage 3: Movement Through Additional Accounts
Funds may subsequently pass through other individual or business accounts.
Each transfer should be examined for its date, amount, recipient, stated purpose and connection with the suspected original proceeds.
Repeated transfers may become relevant to an allegation of layering, but the legal significance of the transactions depends upon the source of funds, surrounding circumstances and applicable statutory requirements.
Stage 4: Transfer into Company Bank Accounts
A company may receive funds against an invoice, commercial agreement, loan, investment or other stated transaction.
The existence of a commercial document does not conclusively establish the legitimacy of the underlying payment. Equally, the mere fact that a company received funds from a suspected account does not automatically prove that the recipient knowingly participated in money laundering.
Relevant records may include contracts, invoices, GST documents, accounting ledgers, bank statements, proof of actual services, purchase orders and correspondence with the relevant counterparty.
The central inquiry is whether the documentary explanation corresponds with the transaction that actually took place.
Stage 5: Identification of the Actual Financial Controller
The director named in the incorporation documents may not be the person who approved or executed the disputed transactions.
Bank mandates, internet-banking authorisations, mobile credentials, account access, communications and operating instructions may assist in identifying the person who exercised practical control.
Where a professional or employee was involved, the nature and scope of that individual's authority should also be determined.
Stage 6: Transfer to the Ultimate Recipient
The alleged proceeds may eventually be transferred to additional companies, withdrawn, converted into other assets or retained by a particular individual or entity.
It is important to distinguish the registered owner of an account or asset from the person exercising actual control or receiving the economic benefit.
These findings may become relevant to the alleged proceeds-of-crime connection, individual responsibility and attachment proceedings.
Illustrative Cyber-Fraud Money Trail and Individual Responsibility Flowchart
An illustrative fund-flow reconstruction demonstrating why account ownership, operational control, individual conduct and the alleged proceeds-of-crime connection require separate examination.Plain-Text Alternative: Original victim payment → first receiving or mule bank account → transfers through additional accounts → company or related-entity accounts → identification of the actual financial controller and ultimate beneficiary → individual assessment of the scheduled offence, proceeds of crime and relevant conduct under PMLA.
Company Directors, Chartered Accountants, Account Operators and Beneficiaries: Why Their Roles Must Be Examined Separately
Financial investigations involving multiple entities often include individuals performing substantially different functions.
Although these persons may appear in the same bank statements or company records, their legal positions should not be treated as identical.
1. Company Directors
Directors may be responsible for managing a company's operations, approving decisions and maintaining statutory compliance.
However, the existence of a directorship is not a substitute for analysing the circumstances in which criminal liability may arise.
Section 70 of the PMLA governs offences by companies and includes provisions concerning persons responsible for the conduct of company business, together with other circumstances relating to consent, connivance or neglect.
The statutory qualifications concerning lack of knowledge and due diligence must also be considered where applicable.
A legally meaningful inquiry should examine whether the director exercised control over the relevant accounts, approved the disputed transactions, participated in the alleged financial arrangement or otherwise falls within the applicable statutory requirements.
2. Chartered Accountants
Chartered Accountants may be retained to assist with incorporation, accounting, compliance, taxation, auditing or related professional services.
The performance of ordinary professional work cannot automatically be equated with knowingly facilitating money laundering.
At the same time, a professional designation does not prevent investigation if the material alleges involvement in the movement, control or concealment of proceeds of crime.
Relevant matters may include:
- The nature of the professional engagement.
- The instructions received from the client.
- The documents prepared or submitted.
- Any involvement in opening or operating bank accounts.
- The extent of access to financial credentials.
- Communications concerning particular transfers.
- Whether services were actually rendered.
- The basis and amount of professional remuneration.
The distinction is between professional work supported by genuine instructions and evidence of conduct that may fall within the statutory offence.
3. Bank-Account Operators
The person whose name appears on an account may differ from the individual who actually executed transfers.
Bank statements establish the occurrence of financial entries but may not, by themselves, establish the identity of the person who authorised each transaction.
Relevant evidence may include electronic banking logs, device access, linked mobile numbers, authorised-signatory records, transaction approvals and communications directing payments.
4. Nominee or Dummy Directors
A nominal appointment may raise questions concerning why a person was appointed, what responsibilities were exercised and whether the individual possessed information about the company's actual business.
However, describing someone as a dummy director does not resolve the legal issue.
The relevant inquiry concerns actual conduct and the requirements of the applicable statutory provision.
5. Beneficial Owners and Ultimate Recipients
A beneficial owner or ultimate recipient may exercise economic control without appearing as the person who initially received the disputed funds.
Investigators may examine asset ownership, corporate structures, related-party transactions, subsequent transfers, financial instructions and the actual use of money.
Ownership, possession, financial benefit and criminal responsibility must nevertheless be distinguished according to the evidence and the law.
6. Employees and External Service Providers
Company employees, consultants and service providers may perform functions connected with accounting, banking or administration.
The fact that an employee processed a transaction does not necessarily answer whether the person was independently responsible for the alleged offence.
The instructions received, scope of authority, awareness of relevant circumstances and nature of the alleged conduct must be assessed individually.
Role-Wise Legal Assessment Matrix
| Person | Principal Issue | Important Evidence |
|---|---|---|
| Director | Actual management, responsibility and involvement | Board records, bank mandates, approvals, communications |
| Chartered Accountant | Nature of professional services and alleged additional involvement | Engagement letters, working papers, financial instructions |
| Account Operator | Actual execution and control of transactions | Banking logs, access records, account authorisations |
| Nominee Director | Formal designation compared with actual conduct | Appointment papers, access rights, communications |
| Beneficial Owner | Economic interest and control over funds | Ownership records, transfers, assets, financial instructions |
| Employee | Nature of duties and instructions | Employment documents, reporting records, communications |
| Outside Vendor | Commercial legitimacy and role in disputed payments | Agreements, invoices, delivery records, tax documents |
When Does a Cyber-Fraud Investigation Become a Money-Laundering Case?
A cybercrime case and a PMLA investigation may arise from the same financial transactions, but the legal ingredients are different.
Cybercrime investigation generally examines the alleged deception, unlawful access, impersonation or other underlying criminal activity.
A PMLA investigation examines whether the relevant property constitutes proceeds of crime and whether the accused was involved in a process or activity connected with those proceeds as contemplated by the statute.
Section 2(1)(u): Proceeds of Crime
Section 2(1)(u) of the PMLA defines proceeds of crime with reference to property derived or obtained directly or indirectly as a result of criminal activity relating to a scheduled offence, together with the value-based elements recognised by the provision.
Accordingly, the alleged criminal origin of the property must be addressed rather than simply assuming that every disputed banking transaction constitutes proceeds of crime.
Section 3: Offence of Money Laundering
Section 3 concerns direct or indirect involvement in a process or activity connected with proceeds of crime, including activities specified in the statute and its Explanation.
These include concealment, possession, acquisition, use and projecting or claiming proceeds of crime as untainted property.
The legal question concerns whether the person's alleged conduct falls within the applicable provision and is supported by the evidence.
Importance of the Scheduled Offence
The presence of an Information Technology Act offence or another cybercrime allegation in an FIR does not automatically establish every requirement for a PMLA proceeding.
The applicable scheduled offence must be identified from the PMLA Schedule and the relevant legal provisions.
For example, Sections 66C and 66D of the Information Technology Act, 2000 concern identity theft and cheating by personation through computer resources, respectively. These provisions should not be assumed, merely because they appear in a cybercrime FIR, to independently satisfy the scheduled-offence requirement under PMLA.
The investigating record may also involve cheating, forgery, criminal conspiracy or other alleged offences. The precise provision, corresponding older or newer criminal-law framework and applicable scheduled-offence position must be examined.
For conduct after the commencement of the Bharatiya Nyaya Sanhita, 2023, the relationship between the BNS provisions and the offences referenced in the PMLA Schedule requires attention to the governing law and judicial interpretation.
Section 70: Offences by Companies
Where the alleged offence involves a company, Section 70 becomes particularly relevant.
The provision should not be reduced to a proposition that every director is automatically guilty.
The inquiry must address the statutory conditions governing the responsibility of persons associated with the company and the evidence concerning their respective conduct.
Supreme Court Judgment: Pavana Dibbur v. Directorate of Enforcement
In Pavana Dibbur v. Directorate of Enforcement, Criminal Appeal No. 2779 of 2023, decided on 29 November 2023, reported as 2023 INSC 1029, the Supreme Court considered important questions concerning proceeds of crime, the scheduled-offence requirement and the position of a person proceeded against under PMLA without being an accused in the underlying scheduled offence.
The Court explained that a person accused of money laundering need not necessarily be named as an accused in the scheduled-offence prosecution.
However, the existence of proceeds of crime connected with criminal activity relating to a scheduled offence remains an essential statutory consideration.
The judgment also addressed the circumstances in which criminal conspiracy under Section 120B IPC could constitute a scheduled offence.
This legal position is important when examining allegations against persons who may not have participated in the original cyber fraud but are alleged to have subsequently handled or dealt with its proceeds.
Judgment: Pavana Dibbur v. Directorate of Enforcement — Supreme Court, 29 November 2023 (PDF).
Why a ₹641-Crore Investigation Does Not Automatically Establish Every Individual's Laundering Role
In a large financial investigation, the amount attributed to the overall scheme may represent transactions involving numerous victims, accounts, companies and individuals.
That consolidated figure does not independently establish how much money each person handled or the nature of that person's involvement.
For example, money may pass through several accounts before reaching its final destination. The same underlying amount may therefore appear repeatedly in different bank statements.
Without proper reconciliation, the financial records may present a misleading picture of the amount originally received, the subsequent movement of funds and the property ultimately held by particular persons.
A company may also have received disputed credits alongside unrelated commercial payments.
The records should distinguish the original suspected proceeds from subsequent transfers of the same funds and payments supported by genuinely unrelated transactions.
Person-Specific Questions
- Which transactions are specifically attributed to the individual?
- What evidence connects those transactions with the alleged scheduled offence?
- Did the person own, control or operate the account?
- Who instructed or authorised the relevant transfers?
- What was the stated commercial or financial purpose?
- What evidence exists concerning the individual's alleged involvement?
- Where did the disputed funds ultimately go?
- What legal provision is relied upon to attribute responsibility?
The answers may differ for each person, even where several individuals were associated with the same company.
At the same time, the absence of money from an individual's current bank balance does not necessarily resolve allegations concerning earlier transactions.
The evidentiary and statutory inquiry is broader than the balance remaining in an account on a particular date.
Preparing a Person-Wise and Entity-Wise Financial Reconstruction Matrix
A structured financial matrix may assist in identifying the evidence supporting each material transaction.
| Information | Required Analysis |
|---|---|
| Transaction Reference | Unique bank, UPI or payment identifier |
| Date and Amount | Verified transaction date, currency and amount |
| Originating Account | Account holder and alleged source of funds |
| Receiving Account | Individual, company or other recipient |
| Declared Purpose | Invoice, contract, loan or stated transaction basis |
| Actual Operator | Person authorising or executing the transfer |
| Corporate Connection | Director, employee, consultant or beneficial owner |
| Supporting Evidence | Bank statement, agreement, communication or other record |
| Subsequent Movement | Next verified account or destination |
| Unresolved Question | Missing document, disputed attribution or inconsistent explanation |
This method allows the investigator or legal team to identify which propositions are supported by original records and which require further verification.
It also assists in separating established financial events from allegations concerning a person's knowledge, purpose or criminal responsibility.
Missing information should be identified as an evidentiary gap rather than replaced with an assumption.
Digital Evidence Required in Cyber-Fraud-Linked PMLA Cases
Cyber-fraud investigations frequently involve a combination of conventional banking documents and electronic records.
The evidence may include:
- Original complaints and victim transaction records.
- UPI references and payment settlement information.
- Relevant QR-code or merchant-payment details.
- Preserved phishing communications and related platform data.
- Bank statements and account-opening KYC.
- Company incorporation and authorised-signatory documents.
- Internet-banking access and transaction approval records.
- Relevant email and messaging correspondence.
- Accounting ledgers, invoices and tax records.
- Original electronic files and available metadata.
- Device extraction records where lawfully obtained.
- Forensic documentation, hash values and chain-of-custody records.
Section 63 of the Bharatiya Sakshya Adhiniyam, 2023 provides an important statutory framework concerning the admissibility of electronic records, subject to its conditions and the applicable law.
A screenshot may demonstrate that information appeared on a device, but it may not establish the entire underlying financial transaction or the identity of the person responsible for it.
Similarly, an account statement may establish that money moved between accounts without conclusively identifying the individual who operated the relevant banking credentials.
The evidentiary analysis should distinguish transaction occurrence, account ownership, actual control, knowledge and alleged involvement in laundering activity.
Which ED Authority or Court Handles a Cyber-Fraud-Linked PMLA Case in Delhi?
Investigations conducted by the ED Headquarters Unit in New Delhi should be distinguished from matters handled by other ED zonal offices.
The relevant authority should be identified from the actual summons, notice, attachment order or judicial record.
Depending upon the stage of the proceedings, different statutory provisions and forums may become relevant.
| Proceeding | Relevant Provision / Forum | Central Issue |
|---|---|---|
| Summons | Section 50 PMLA | Attendance, information and document production |
| Search and Seizure | Section 17 PMLA, where applicable | Authorisation and statutory procedure |
| Provisional Attachment | Section 5 PMLA | Statutory grounds and identification of property |
| Adjudication | Section 8 PMLA | Examination of the attachment and relevant material |
| Arrest | Section 19 PMLA | Statutory conditions and procedural safeguards |
| Bail | Section 45 PMLA and applicable law | Statutory requirements and individual circumstances |
| Prosecution | Section 44 PMLA and designated Special Court | Alleged offence and evidentiary foundation |
| Appeal | Sections 26 and 42 PMLA, as applicable | Correct remedy, forum and limitation |
The competent Special Court must be determined from the applicable legal framework and the specific case record.
An investigation being conducted from New Delhi does not automatically establish that every connected judicial proceeding belongs before the same court.
Similarly, the availability of a remedy before the Delhi High Court depends upon jurisdiction, maintainability, the nature of the challenged action and other relevant considerations.
What Should a Director, Chartered Accountant or Account Holder Do After Receiving an ED Summons?
A summons under Section 50 PMLA requires prompt and careful attention.
Receipt of a summons does not, by itself, establish that the recipient has committed an offence. Nevertheless, the statutory obligations associated with a valid summons should not be disregarded.
Step 1: Verify the Summons
Identify the issuing officer, ED unit, statutory provision, appearance date, place of attendance and records requested.
Where an official electronic verification mechanism applies, it should be used through the genuine government website.
Step 2: Identify the Capacity in Which the Person Has Been Summoned
The recipient may be a director, employee, accountant, consultant, account holder, custodian of records or another person believed to possess relevant information.
The document schedule may help identify the transactions or period under examination.
Step 3: Preserve Authentic Records
Relevant original documents and electronic records should be preserved without deletion, fabrication, alteration or selective destruction.
Step 4: Prepare an Accurate Chronology
The chronology should identify the period of professional or corporate involvement, appointment dates, actual responsibilities, access to accounts and relevant financial transactions.
Step 5: Reconcile the Financial Records
Material payments should be matched against bank statements and supporting commercial documents.
Where the records are incomplete, the missing information should be clearly identified.
Step 6: Review the Statutory Position
The legal assessment may include the alleged scheduled offence, proceeds-of-crime connection, applicable PMLA provisions and the nature of the person's alleged involvement.
Step 7: Respond Truthfully and Cooperate in Accordance with Law
Any statement or document submission should be accurate and based upon genuine information.
Where additional time is required for legitimate reasons, an appropriate documented request may be made to the issuing authority.
Professional preparation must not involve manufacturing explanations, creating false documents or influencing another person's statement.
Related Reading: ED Summons in Delhi under Section 50 PMLA: Rights, Documents and Statement Preparation.
Common Mistakes in Cyber-Fraud and Shell-Company PMLA Investigations
1. Treating Every Director as the Actual Account Operator
Formal corporate responsibility and practical banking control may differ. Both should be examined.
2. Treating the Entire Alleged Fraud Amount as an Individual's Personal Gain
The amount attributed to a larger network may not correspond with the amounts handled or received by a particular person.
3. Assuming Every Company with Common Directors Is a Shell Company
Corporate connections may justify scrutiny, but actual business activity and supporting documents remain relevant.
4. Assuming Professional Designation Provides Automatic Protection
Professional status does not replace examination of an individual's conduct and the applicable law.
5. Ignoring Actual Banking Access
A registered account holder, authorised signatory and actual transaction operator may occupy different positions.
6. Failing to Identify the Scheduled Offence
Cybercrime allegations should be examined against the PMLA Schedule and the relevant statutory provisions.
7. Relying Exclusively on Consolidated Spreadsheets
Transaction summaries should be traceable to original banking and supporting records.
8. Failing to Preserve Electronic Evidence
Loss of relevant data may affect the ability to reconstruct transactions and establish the surrounding facts.
9. Confusing Agency Allegations with Judicial Findings
Investigative claims must not be represented as findings of guilt unless established through the appropriate judicial process.
10. Applying the Same Legal Remedy to Every Stage
Summons, arrest, attachment, adjudication, bail and prosecution involve different statutory procedures and legal tests.
Practical Document Checklist for a Cyber-Fraud-Linked PMLA Matter
The following checklist may assist with an organised legal review, subject to the particular facts and applicable legal requirements.
- ED summons, notices and correspondence.
- Relevant FIR or complaint details, where available.
- Company incorporation documents and statutory records.
- Director and authorised-signatory appointment records.
- Relevant bank statements and account-opening documentation.
- Bank mandates and access authorisations.
- Transaction-wise payment records.
- Commercial agreements, invoices and accounting ledgers.
- GST and income-tax records where relevant.
- Professional engagement letters and working papers.
- Relevant communications concerning disputed transfers.
- Supporting records showing actual services or transactions.
- Documents concerning asset ownership or beneficial control.
- Relevant search, seizure, freezing or attachment documents.
- Previous judicial orders and procedural records.
A complete record should also identify information that remains unavailable and the lawful steps that may be necessary to obtain it.
Frequently Asked Questions
1. Can ED investigate part-time job scams under PMLA?
Yes, where the statutory foundation exists, including an applicable scheduled offence, alleged proceeds of crime and the relevant money-laundering activity. A fraudulent job offer alone does not automatically establish every requirement of the PMLA.
2. Can a company director face PMLA proceedings if fraud money entered the company account?
Potentially, depending upon the evidence and applicable law. The relevant inquiry includes the company's transactions, the director's actual responsibilities and the statutory conditions governing individual liability.
3. Can a Chartered Accountant be investigated for incorporating a company later described as a shell company?
Yes, where the investigation concerns relevant conduct and supporting evidence. However, ordinary incorporation or accounting work should not automatically be equated with proven participation in money laundering.
4. Is a mule-account holder automatically guilty of money laundering?
No. The registered holder's position, actual operation of the account, relevant conduct and the applicable statutory ingredients must be examined.
5. Can a person face PMLA proceedings without participating in the original cyber fraud?
Potentially, yes. A person alleged to have subsequently dealt with proceeds of crime may face scrutiny even where that person is not an accused in the scheduled-offence prosecution. The statutory requirements must nevertheless be established.
6. What if a company received the money for genuine business services?
The relevant contracts, invoices, actual services, commercial correspondence, banking records and other supporting evidence should be examined to determine the nature of the transaction.
7. Does an ED summons automatically make the recipient an accused?
No. A summons under Section 50 may be issued to obtain evidence or documents. The recipient's legal position depends on the relevant circumstances and statutory proceedings.
8. Does every QR-code or phishing case attract PMLA?
No. The applicable scheduled offence and proceeds-of-crime requirements must be examined. The existence of an online fraud does not automatically establish money laundering.
9. Can a person be investigated when no money remains in their bank account?
Yes, depending upon the circumstances. Historical account activity and alleged involvement in transactions may remain relevant even where the present account balance is zero.
10. Does the total alleged fraud amount establish the amount laundered by each person?
No. A consolidated figure does not, by itself, establish the transactions or conduct attributable to a particular individual. Individual financial reconstruction may be necessary.
11. What is the relevance of Section 70 PMLA?
Section 70 concerns offences by companies and the circumstances in which responsibility may extend to persons associated with the conduct of company business or officers involved in the contravention. Its statutory requirements and qualifications must be examined.
12. Can a director or professional approach the Delhi High Court?
Appropriate High Court remedies may be available depending upon jurisdiction, maintainability, the nature of the grievance, the applicable legal provisions and the procedural stage. A High Court remedy cannot be assumed to be available in every situation.
13. What documents should be preserved after receiving an ED summons?
The summons, relevant banking and corporate documents, authentic transaction records, professional engagement documents, communications and other records connected with the inquiry should be preserved as applicable.
14. Does an ED press release establish that the persons named have committed an offence?
No. A press release communicates the agency's investigative position and procedural developments. Criminal liability must be adjudicated according to law.
15. How should someone evaluate a lawyer for an ED or PMLA matter in Delhi?
Relevant considerations include experience with the applicable statutory framework, familiarity with the procedural stage, ability to analyse complex financial records, clarity concerning professional responsibilities and compliance with the rules governing legal practice. Descriptions such as "best ED lawyer" are search expressions and do not establish an objective professional ranking.
Quick Legal Answer: Why Directors, Chartered Accountants and Beneficiaries Do Not Automatically Have the Same PMLA Liability
In a cyber-fraud-linked money-laundering investigation, the legal position of each individual depends upon the applicable statutory provisions and the evidence of that person's conduct. A company director may exercise managerial responsibility, a Chartered Accountant may provide professional services, an account operator may execute financial transfers and a beneficial owner may receive economic advantage. These roles are not interchangeable. The alleged proceeds-of-crime connection, actual involvement and supporting records must be examined separately for each person.
Conclusion: The Real Question Is Who Controlled the Money and What the Evidence Establishes
The March 2026 Enforcement Directorate Headquarters investigation illustrates how alleged cyber-fraud proceeds may travel from victims' accounts into mule bank accounts, interconnected companies and further financial arrangements.
Such investigations can involve complicated banking records, corporate structures and electronic evidence.
However, the existence of a large suspected transaction network does not eliminate the need to identify the legal and factual position of individual participants.
A financial reconstruction should establish the origin of the disputed property, the movement of funds, the persons exercising actual control, the apparent commercial purpose of the transactions and the evidence concerning the conduct of each individual.
For company directors, Chartered Accountants, account operators and alleged beneficiaries, these distinctions may become central to understanding the allegations and the available legal remedies.
The essential legal principle is that a scheme-wide allegation must be examined alongside the specific statutory requirements and evidence relevant to each person. Neither professional designation nor association with a suspected company can replace that individual legal assessment.
Related Legal Research
- How Delhi ED Traces Cryptocurrency and Virtual Digital Asset Funds.
- PMLA Investigations Involving Shell Companies, Beneficial Ownership and Layering.
- Chartered Accountants, Company Secretaries, Auditors and Professional Intermediaries Facing ED Proceedings.
- ED Summons in Delhi under Section 50 PMLA: Rights, Documents and Statement Preparation.
Legal Research and Professional Coordination
Advocate Ankit Kumar Singh undertakes legal work involving the Prevention of Money-Laundering Act, Enforcement Directorate proceedings, cybercrime-connected financial investigations, corporate transactions, banking records and related litigation, subject to the facts of the matter, jurisdiction and accepted professional engagement.
Relevant work may include examination of statutory notices, summons, financial records, corporate documentation, alleged proceeds-of-crime transactions, attachment proceedings and available remedies before the competent authority or court.
Consultation, legal drafting, filing, representation or professional coordination depends upon the nature of the engagement, applicable procedure and the requirements of the relevant forum.
Where proceedings before the Supreme Court require an Advocate-on-Record, the applicable filing and representation requirements must be followed. Local or authorised counsel may also be required according to the forum.
The professional base is Patna, Bihar. Discussion of Delhi ED investigations or Delhi courts does not represent a claim of maintaining a separate permanent office in Delhi.
Professional Name: Advocate Ankit Kumar Singh
Relevant Court and Forum Coverage: Supreme Court of India | Patna High Court | Allahabad High Court at Prayagraj | Jharkhand High Court at Ranchi | Calcutta High Court | Delhi High Court and Delhi Courts/Tribunals | Matters concerning Bhopal, Madhya Pradesh | Multiple District Courts.
Advocate Ankit Kumar SinghPhone: 8294431232
Email: ankitsingh.legum@gmail.com
Website: advocateankitkumarsingh.in
No particular outcome concerning arrest, bail, attachment, release of property, quashing, discharge, trial or appellate proceedings can be guaranteed.
Official Sources and Legal References
-
Directorate of Enforcement — Headquarters Unit, New Delhi, Press Release dated 5 March 2026.
Read the official ED press release (PDF). -
Prevention of Money-Laundering Act, 2002.
Relevant provisions include Sections 2(1)(u), 3, 5, 8, 17, 19, 44, 45, 50 and 70.
Directorate of Enforcement — Official PMLA Acts and Rules. -
Pavana Dibbur v. Directorate of Enforcement, 2023 INSC 1029.
Supreme Court of India, Criminal Appeal No. 2779 of 2023, judgment dated 29 November 2023.
Read the Supreme Court judgment (PDF). -
Information Technology Act, 2000.
Relevant provisions concerning identity theft and cheating by personation using computer resources, where applicable.
India Code — Official Statutory Portal. -
Bharatiya Nyaya Sanhita, 2023.
Applicable criminal-law provisions should be examined according to the date and nature of the alleged conduct.
Ministry of Home Affairs — New Criminal Laws. -
Bharatiya Sakshya Adhiniyam, 2023.
Relevant provisions concerning electronic records and evidence, including Section 63.
India Code — Bharatiya Sakshya Adhiniyam, 2023.
Legal Verification: The applicable statutory provisions, amendments, procedural rules, court orders and the status of an individual proceeding should be verified from current official sources before taking legal action.
Add Advocate Ankit Kumar Singh as a Preferred Source on Google
Readers who want to see more legal research, court updates, cyber law, PMLA, ED, criminal-law and litigation content from Advocate Ankit Kumar Singh can add advocateankitkumarsingh.in as a Preferred Source on Google.
Add advocateankitkumarsingh.in as a Preferred Source on Google
Legal Disclaimer: This article provides general legal information and professional research as of 9 October 2026. It does not constitute legal advice for any particular person or transaction. The discussion of the March 2026 ED investigation is based on the agency's publicly disclosed allegations and procedural information and does not represent a finding of guilt against any individual. All legal rights, obligations and remedies depend on the relevant facts, records, statutory provisions and judicial proceedings. The phrase "best ED lawyer" is used in the article title as a search-intent expression and does not assert a verified professional ranking or superiority. No assurance is made regarding arrest, bail, discharge, quashing, attachment, release of property, conviction, acquittal or any other legal outcome.