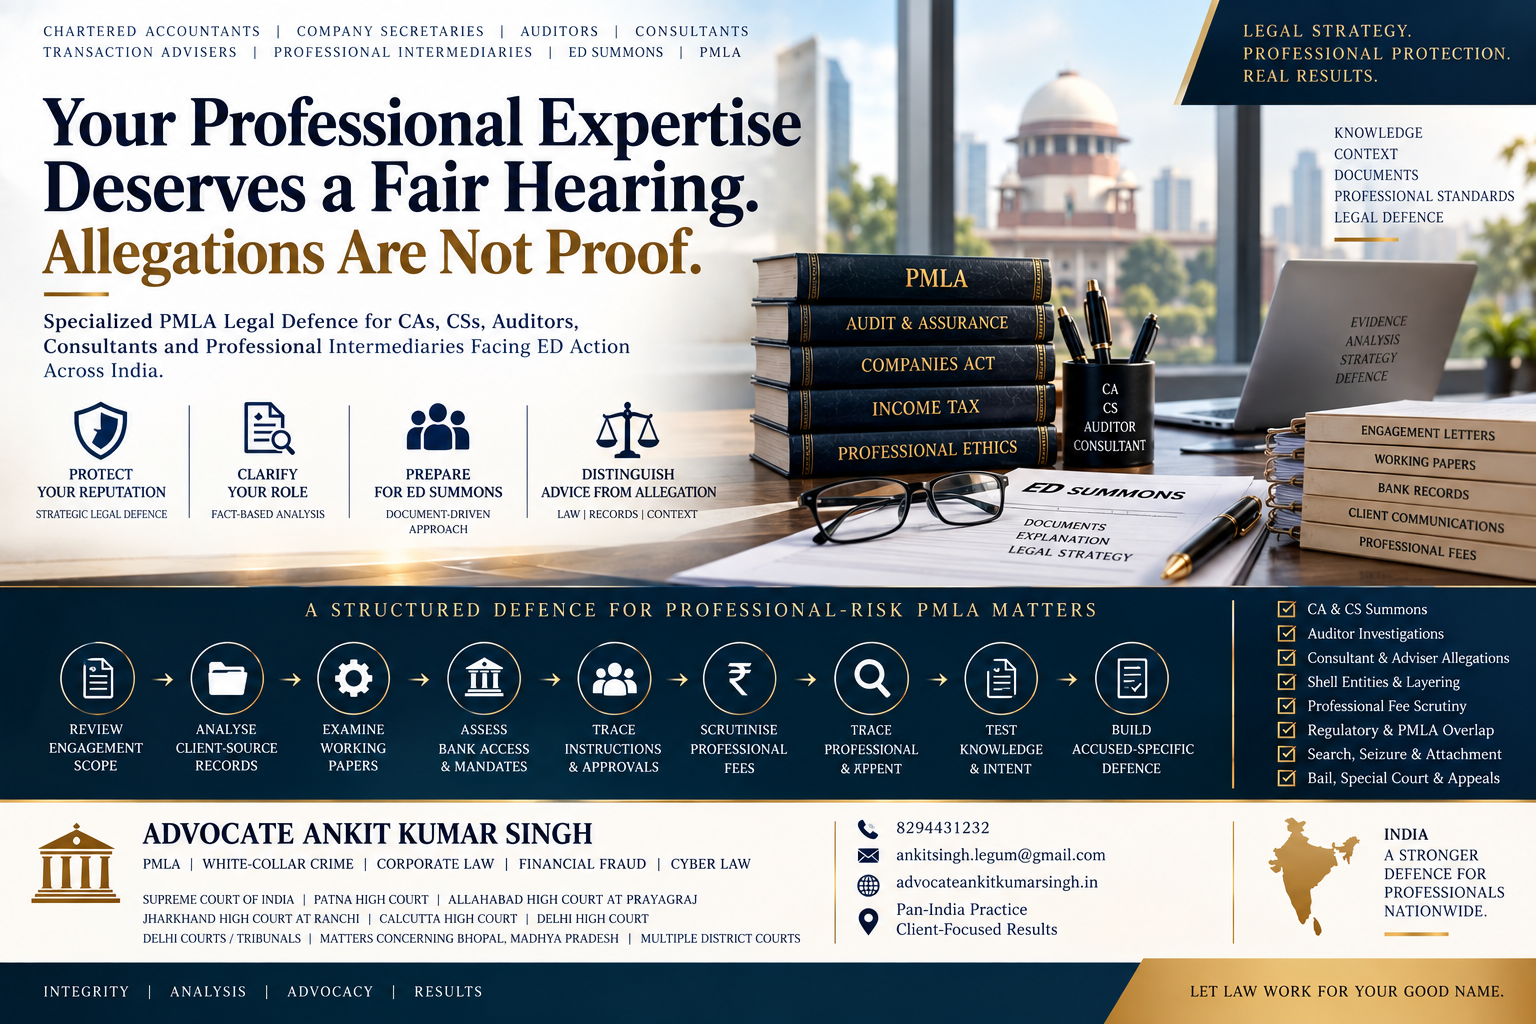
PMLA • ED SUMMONS • CHARTERED ACCOUNTANTS • COMPANY SECRETARIES • AUDITORS • CONSULTANTS • PROFESSIONAL INTERMEDIARIES • INDIA
Specialized PMLA Lawyer in India for Chartered Accountants, Company Secretaries, Auditors and Professional Intermediaries Facing ED Action
Legally researched and updated: 20 September 2026
Supreme Court of India | Patna High Court | Allahabad High Court at Prayagraj | Jharkhand High Court at Ranchi | Calcutta High Court | Delhi High Court and Delhi Courts/Tribunals | Matters concerning Bhopal, Madhya Pradesh | Multiple District Courts
 Advocate Ankit Kumar Singh
Direct Answer: Does Providing Professional Services to a Client Under ED Investigation Make the Professional Liable Under PMLA?
No automatic conclusion follows merely because a Chartered Accountant, Company Secretary, auditor, consultant or transaction adviser provided professional services to a client who is later investigated by the Enforcement Directorate.
The critical legal question is:
WHAT DID THE PROFESSIONAL ACTUALLY DO, WHAT DID THE PROFESSIONAL KNOW, WHAT RECORDS WERE AVAILABLE, WHAT INSTRUCTIONS WERE RECEIVED, AND WAS THE PROFESSIONAL KNOWINGLY ASSISTING A PROCESS OR ACTIVITY CONNECTED WITH ALLEGED PROCEEDS OF CRIME?
Section 3 PMLA expressly addresses a person who directly or indirectly attempts to indulge, knowingly assists, knowingly becomes a party to, or is actually involved in a process or activity connected with proceeds of crime.
That makes knowledge, conduct and accused-specific role attribution central.
For a professional searching for a specialized PMLA lawyer India professionals, best ED lawyer India CA summons, expert PMLA advocate India auditor or money laundering lawyer India consultant, the meaningful counsel-selection issue is whether the lawyer can distinguish:
- professional advice from transaction control;
- document preparation from fabrication;
- audit review from management decision-making;
- filing statutory forms from beneficial ownership of the transaction;
- professional fee from alleged criminal benefit;
- access to records from control of bank accounts;
- knowledge of a client transaction from knowing participation in laundering.
There is no official Court, Bar Council, Government, ICAI, ICSI or Enforcement Directorate ranking declaring any advocate the "best" or "specialized" lawyer for professionals facing PMLA proceedings. These phrases are used as public search-intent language.
Section 3 PMLA Makes "Knowingly Assists" a Critical Professional-Risk Question
The statutory language of Section 3 is important for professionals.
The provision covers, among other things, a person who:
- directly or indirectly attempts to indulge;
- knowingly assists;
- knowingly is a party;
- or is actually involved
in a process or activity connected with proceeds of crime, subject to the complete statutory language.
Therefore, professional engagement alone is not the end of the inquiry.
Counsel should test:
SERVICE PROVIDED → INFORMATION AVAILABLE → INSTRUCTION RECEIVED → ACTION TAKEN → TRANSACTION EFFECT → FINANCIAL BENEFIT → KNOWLEDGE ALLEGED BY ED.
The First Skill: Define the Exact Professional Engagement
The defence should begin with the engagement itself.
For a CA, CS, auditor or consultant identify:
- engagement letter;
- appointment resolution;
- scope of services;
- engagement start date;
- engagement end date;
- entity or individual who appointed the professional;
- reporting line;
- fees agreed;
- deliverables;
- limitations on scope;
- records supplied by management;
- work actually performed.
The first defence question should be:
WAS THIS PROFESSIONAL ENGAGED TO ADVISE, AUDIT, CERTIFY, FILE, IMPLEMENT, OPERATE OR CONTROL?
Those functions are materially different.
The Second Skill: Separate Client-Source Information From Professionally Generated Material
A professional file can contain documents originating from several sources.
Counsel should distinguish:
- documents supplied by client management;
- bank statements supplied by the client;
- invoices supplied by the client;
- contracts supplied by the client;
- management representations;
- third-party confirmations;
- professional working papers;
- calculations prepared by the professional;
- draft forms;
- final filed forms;
- professional opinions;
- email instructions.
This distinction can be crucial where ED alleges that a professional "created" or "structured" a transaction that was actually based on information supplied by the client.
The Third Skill: Audit Working Papers May Become Central Evidence
ICAI's Standard on Auditing 230 defines audit documentation as the record of audit procedures performed, relevant audit evidence obtained and conclusions reached.
Working papers may therefore help establish:
- what information the auditor received;
- what procedures were performed;
- what queries were raised;
- what management explained;
- what evidence was checked;
- what exceptions were identified;
- what conclusion was reached;
- who reviewed the work.
In a PMLA investigation, working papers can therefore become relevant not only to what the professional knew, but also to what the professional did not know at the relevant time.
SA 230: Contemporaneous Documentation Can Be Stronger Than a Later Explanation
Professional defence is often stronger when the file contains contemporaneous records.
Relevant material may include:
- engagement letter;
- audit plan;
- risk assessment;
- working papers;
- client queries;
- management replies;
- review notes;
- third-party confirmations;
- exceptions;
- final conclusion;
- communications with those charged with governance.
A contemporaneous email saying:
"PLEASE PROVIDE THE SUPPORTING BANK RECORD BEFORE WE CAN CONCLUDE"
can present a very different evidentiary picture from an allegation that the professional unquestioningly facilitated a transaction.
The Fourth Skill: Distinguish Audit Responsibility From Management Responsibility
An auditor ordinarily examines and reports on financial statements or specified financial information within the applicable engagement framework.
Management may separately:
- enter contracts;
- approve payments;
- control bank accounts;
- select counterparties;
- decide commercial purpose;
- maintain accounting records;
- authorise transactions.
Counsel should therefore identify:
WHO CREATED THE TRANSACTION? WHO APPROVED IT? WHO EXECUTED IT? WHO ACCOUNTED FOR IT? WHO AUDITED OR REVIEWED IT?
These may be different persons.
The Fifth Skill: Bank Access Is a Major Role-Attribution Question
One of the most important questions in an alleged facilitation case is whether the professional merely reviewed bank records or actually had authority over the account.
Counsel should identify:
- whether the professional was an authorised signatory;
- whether internet banking access existed;
- whether beneficiary addition was possible;
- whether OTPs were received;
- whether cheque books or ATM cards were possessed;
- whether the professional was maker or checker;
- whether payment instructions were drafted;
- whether transactions could be independently approved.
The distinction is:
ACCESS TO BANK INFORMATION ≠ AUTHORITY TO MOVE BANK FUNDS.
The Sixth Skill: Company Secretaries Need Filing-by-Filing Role Analysis
A Company Secretary may become connected with an investigation because of corporate filings, board records, shareholding changes or incorporation of entities.
Counsel should identify:
- which forms were filed;
- who supplied the underlying information;
- what board resolution existed;
- what supporting documents were provided;
- whether the CS advised on structure or merely filed approved documents;
- whether beneficial ownership information was disclosed;
- whether share transfers were implemented;
- whether the professional had any bank authority;
- whether the professional received a normal professional fee or another financial benefit.
Filing a statutory form and controlling the underlying commercial transaction are different factual acts.
The Seventh Skill: Incorporation of Companies Must Be Analysed Entity by Entity
A professional may have assisted in incorporating several entities.
That fact can become significant where ED alleges that the companies were dummy or shell entities used to layer proceeds of crime.
Counsel should ask:
- Who requested incorporation?
- Who selected shareholders and directors?
- Who supplied KYC documents?
- Who paid incorporation expenses?
- Who opened the bank account?
- Who controlled the account?
- Did the company carry on business?
- Did the professional remain involved after incorporation?
- Did the professional receive control of banking instruments?
A professional who performed a standard incorporation mandate presents a different factual case from one alleged to have created and controlled entities as financial conduits.
March 2026 Cyber-Fraud Investigation: Why Professional Role Attribution Matters
In March 2026, ED Headquarters publicly stated that it arrested Chartered Accountants Ashok Kumar Sharma and Bhaskar Yadav in connection with a cyber-fraud PMLA investigation.
ED alleged that a professional syndicate incorporated and controlled more than twenty entities operating from common addresses with overlapping partners, authorised signatories, KYC documentation, mobile numbers and email IDs.
The Directorate alleged that those entities functioned as conduits for layering cyber-fraud proceeds before transfer outside India.
ED also stated that cheque books and ATM cards relating to alleged shell entities had been recovered during searches.
These statements are ED's investigative allegations and are not final judicial findings of guilt.
The defence lesson is that the inquiry can move beyond:
"DID THE PROFESSIONAL INCORPORATE THE COMPANY?"
to:
"DID THE PROFESSIONAL CONTROL THE COMPANY, BANKING INSTRUMENTS, KYC INFRASTRUCTURE OR MOVEMENT OF FUNDS?"
The Eighth Skill: Instructions Must Be Traced to Their Source
A professional may act on instructions from:
- promoter;
- director;
- CFO;
- finance manager;
- authorised employee;
- external lawyer;
- trustee;
- client representative.
For every questioned act identify:
- who instructed it;
- whether instruction was oral or written;
- what supporting documents were provided;
- whether approval was verified;
- whether the professional raised questions;
- whether the instruction was within the engagement scope.
A strong instruction chronology may look like:
CLIENT INSTRUCTION → SUPPORTING DOCUMENT → PROFESSIONAL REVIEW → QUERY → CLIENT RESPONSE → PROFESSIONAL ACTION.
The Ninth Skill: Professional Fees Must Be Distinguished From Alleged Proceeds Sharing
Payment received by a professional should be classified carefully.
Counsel should identify:
- engagement letter;
- invoice;
- fee amount;
- GST treatment;
- TDS;
- bank receipt;
- services performed;
- market reasonableness;
- retainer or success fee;
- reimbursement;
- additional unexplained payment, if alleged.
A documented professional fee for genuine work presents a different question from an allegation that the professional received a share of criminal proceeds.
The Tenth Skill: Knowledge Must Be Analysed at the Time of the Act
Information discovered years later should not automatically be projected backwards.
Counsel should ask:
- What information existed when the professional acted?
- What documents had been supplied?
- What red flags were visible?
- Were inconsistencies raised?
- Did the client conceal information?
- Were representations false?
- Did the professional continue after discovering material concerns?
- Was the professional financially benefiting from the questioned activity?
The temporal question is:
WHAT DID THE PROFESSIONAL KNOW WHEN THE QUESTIONED SERVICE WAS PROVIDED?
The Eleventh Skill: Professional Negligence, Regulatory Breach and Knowing Laundering Are Different Questions
An investigation may reveal an alleged:
- audit failure;
- documentation deficiency;
- professional-standard issue;
- Companies Act issue;
- disciplinary issue;
- tax-compliance error;
- or other regulatory breach.
Those matters can be serious.
But a PMLA allegation must still be tested against the statutory requirement concerning proceeds of crime and the person's alleged process or activity, including any allegation of knowing assistance.
The defence should not allow every professional shortcoming to be automatically re-characterised as intentional money laundering.
The Twelfth Skill: Certifications and Attestations Must Be Analysed Document by Document
Where ED relies upon a certificate or attestation, counsel should identify:
- document certified;
- statutory basis;
- scope of certification;
- records examined;
- management representation;
- independent verification performed;
- qualification or disclaimer;
- date;
- UDIN where applicable;
- subsequent use of the document.
The legal significance of certifying a balance sheet can differ from certifying a transaction-specific source-of-funds statement.
The Thirteenth Skill: Digital Records Can Show Whether the Professional Was Adviser or Operator
Digital evidence may include:
- emails;
- WhatsApp messages;
- Telegram communications;
- accounting software;
- cloud folders;
- shared drives;
- banking dashboards;
- corporate filing credentials;
- spreadsheets;
- remote-access logs.
Counsel should identify:
- who created the document;
- who edited it;
- who approved it;
- whether credentials were shared;
- whether the professional had operational access;
- whether the professional merely received a copy for review.
The Fourteenth Skill: Professional Email Language Must Be Read in Context
Short messages such as:
"PLEASE ROUTE THIS THROUGH COMPANY B"
can appear highly significant when isolated.
Counsel should determine:
- what transaction was under discussion;
- whether Company B was contractually entitled to receive the amount;
- who proposed the route;
- whether tax, accounting or regulatory reasons were being discussed;
- whether the full email chain changes the meaning;
- whether the adviser was giving legal / accounting advice or operational instructions.
A fragment should be compared with the full communication and underlying documents.
The Fifteenth Skill: Auditors Should Separate Audit Evidence From Client Representations
Not every item appearing in an audit file has the same evidentiary source.
Counsel should label:
- management representation;
- independent third-party confirmation;
- bank confirmation;
- client-generated ledger;
- auditor calculation;
- external valuation;
- legal opinion;
- management explanation;
- auditor conclusion.
This can prevent a statement made by management from being incorrectly attributed to the auditor as an independently verified fact.
The Sixteenth Skill: Consultants and Transaction Advisers Need Deliverable-by-Deliverable Analysis
A consultant may have been engaged for:
- financial modelling;
- fund raising;
- transaction structuring;
- due diligence;
- valuation;
- project management;
- investment introduction;
- business strategy;
- compliance review.
Counsel should identify the exact deliverable and whether the consultant:
- recommended the counterparty;
- handled money;
- controlled escrow;
- drafted contracts;
- operated accounts;
- received a transaction-linked commission;
- knew the alleged source of funds;
- continued after discovering suspicious facts.
The Seventeenth Skill: Client-Sourced KYC Must Be Distinguished From Professional Verification
A professional may retain PAN, Aadhaar, incorporation records, beneficial-ownership declarations or bank details supplied by the client.
Counsel should establish:
- who supplied the document;
- what verification was required under the engagement;
- what verification was actually performed;
- whether inconsistencies were apparent;
- whether the professional had reason to suspect fabrication;
- whether subsequent investigation discovered facts unavailable at the time.
The Eighteenth Skill: Section 50 Summons Preparation Must Be Profession-Specific
Section 50 PMLA gives specified authorities powers concerning summons, production of records and giving evidence.
A professional should therefore not approach a Section 50 summons as an informal meeting.
Depending upon the scope of the summons, preparation may require:
- engagement letter;
- client list relevant to the inquiry;
- working papers;
- invoices;
- professional-fee receipts;
- emails;
- bank-authority records;
- corporate filings;
- audit documentation;
- client-source documents;
- internal review notes;
- earlier regulatory correspondence;
- digital records;
- chronology of the engagement.
Counsel should also identify which documents are held by the professional, which are held by the client and which never formed part of the engagement file.
The Nineteenth Skill: Build a Role-Attribution Matrix Before the ED Appearance
| Questioned Act | Client Instruction | Professional Role | Knowledge | Supporting Record |
|---|---|---|---|---|
| [Transaction / filing] | [Who instructed] | [Audit / filing / advice] | [What was known] | [Email / WP / agreement] |
This converts a broad allegation of "professional facilitation" into discrete, testable acts.
The Twentieth Skill: Preserve the Difference Between Document Custody and Transaction Control
Professionals may possess:
- company records;
- signed resolutions;
- tax files;
- bank statements;
- digital copies of cheque books;
- share certificates;
- corporate KYC.
Custody of records does not automatically establish authority over the transaction.
But possession of operational instruments such as:
- ATM cards;
- cheque books;
- bank tokens;
- OTP devices;
- account passwords;
- corporate seals used without client supervision
may require substantially deeper explanation.
The Twenty-First Skill: Professional Independence and Client Advocacy Should Not Be Confused With Concealment
A professional can legitimately:
- advise on tax-efficient structures;
- prepare corporate filings;
- raise accounting objections;
- represent a client before authorities;
- advise on restructuring;
- prepare compliance documentation.
The legal issue changes where ED alleges that the professional knowingly created false records, concealed ownership, operated sham entities or consciously assisted movement of criminal proceeds.
Counsel should therefore identify the line between:
PROFESSIONAL SERVICE
and
ALLEGED KNOWING PARTICIPATION IN THE FINANCIAL PROCESS.
Tehmul Sethna 2026: Professional Designation Does Not Replace Transaction-Specific Analysis
In March 2026, ED Ahmedabad publicly stated that it filed a prosecution complaint against practising Chartered Accountant Tehmul Sethna in a case arising from a Gujarat Police cheating FIR.
ED alleged that, after being entrusted with administrative and financial affairs of a trust, he obtained access relating to a bank account, forged a trustee's signature and issued unauthorised bearer cheques, resulting in withdrawal of approximately ₹6.85 crore.
These are prosecution allegations and remain subject to judicial determination.
The case illustrates why professional-risk analysis must focus on:
ENTRUSTMENT → BANK ACCESS → AUTHORITY → DOCUMENT CREATION → FUND MOVEMENT → PERSONAL BENEFIT.
The issue was not professional designation in isolation but the specific financial conduct alleged by ED.
The Twenty-Second Skill: A CA, CS or Auditor May Also Be a Director, Partner or Beneficiary
A person's professional qualification does not always describe the complete role.
The same person may simultaneously be:
- CA / CS / consultant;
- director;
- partner;
- shareholder;
- authorised signatory;
- beneficial owner;
- loan creditor;
- investment recipient.
Counsel should separate each capacity.
The defence should not rely merely upon:
"I WAS ONLY THE CA."
if the records show another formal or economic role.
The Twenty-Third Skill: Professional Fees Paid by a Questioned Client Must Be Reconciled With Work Done
Prepare a fee schedule showing:
- invoice date;
- service description;
- fee;
- tax;
- TDS;
- payment date;
- payer;
- work product;
- engagement period.
This helps distinguish ordinary professional income from allegations of unexplained or transaction-linked financial benefit.
The Twenty-Fourth Skill: Do Not Alter the Professional File After Receiving an ED Summons
Once an investigation or summons is known, the safer professional approach is to preserve the relevant file in its existing form and obtain case-specific legal advice on production.
Professionals should avoid:
- backdating engagement letters;
- creating retrospective working papers presented as contemporaneous;
- deleting emails;
- deleting WhatsApp chats;
- changing ledger narrations;
- replacing documents silently;
- coordinating false explanations with clients.
Any genuine later explanatory note should be clearly identifiable as a later-created document.
Common Mistakes When Professionals Face ED Action
- Assuming professional qualification itself protects against PMLA scrutiny.
- Assuming professional association itself proves money laundering.
- Attending a Section 50 summons without reconstructing the engagement chronology.
- Failing to produce or preserve the engagement letter.
- Mixing client-source records with professional working papers.
- Giving a broad answer that the professional "handled accounts" when the actual role was narrower.
- Failing to identify actual bank authority.
- Confusing access to statements with authority to transfer funds.
- Ignoring email instructions from management.
- Failing to preserve working papers.
- Creating retrospective documentation that appears contemporaneous.
- Treating every incorporation assignment as identical.
- Failing to distinguish statutory filing from transaction structuring.
- Ignoring professional-fee records.
- Failing to analyse GST and TDS on professional fees.
- Treating audit failure and knowing laundering as automatically the same legal issue.
- Failing to separate audit responsibility from management responsibility.
- Ignoring alternate roles such as director, partner or beneficial owner.
- Giving inconsistent explanations across ED, tax, regulatory or disciplinary proceedings.
- Deleting digital records after receiving investigative notice.
Specialized PMLA Lawyer India Professionals: What Should a CA, CS, Auditor or Consultant Actually Evaluate?
Rather than relying upon promotional ranking language, a professional can evaluate whether counsel can:
- analyse Section 3 "knowingly assists" allegations;
- review the scheduled-offence and proceeds-of-crime foundation;
- define the exact engagement scope;
- separate client-source records from professional work product;
- analyse audit working papers;
- distinguish management responsibility from audit responsibility;
- analyse bank access and mandates;
- review corporate filing roles;
- reconstruct incorporation assignments;
- trace instructions;
- analyse professional fees;
- test accused-specific knowledge;
- distinguish professional error from alleged knowing assistance;
- analyse certificates and attestations;
- review digital evidence;
- prepare a role-attribution matrix;
- prepare Section 50 responses;
- coordinate professional-regulatory and PMLA issues without inconsistent factual positions;
- handle search, attachment, bail, Special Court and appellate issues where applicable.
These objective capabilities are more meaningful than an unsupported claim of being the "best ED lawyer India CA summons".
Why Clients May Consider Advocate Ankit Kumar Singh for Professional-Risk PMLA Matters
Advocate Ankit Kumar Singh works on PMLA, Enforcement Directorate, white-collar and financial-crime matters involving corporate records, banking trails, digital evidence, summons, professional intermediaries, beneficial ownership, attachment and connected criminal proceedings.
Depending upon the facts and accepted professional engagement, work may include:
- Section 50 summons preparation;
- scheduled-offence review;
- professional engagement analysis;
- CA / CS / auditor role attribution;
- working-paper review;
- client-source document segregation;
- bank-authority analysis;
- corporate filing review;
- professional-fee reconstruction;
- email and digital-evidence analysis;
- company / shell-entity allegation review;
- fund-flow analysis;
- beneficial-ownership analysis;
- search / seizure / freezing strategy;
- attachment proceedings;
- bail and Special Court coordination;
- High Court and appellate strategy where applicable.
References to national practice, the Supreme Court, High Courts and other forums describe professional jurisdictional work and do not represent an official appointment, empanelment or endorsement by the Directorate of Enforcement, ICAI, ICSI, Ministry of Corporate Affairs, Government or any investigating authority.
No non-arrest, closure, bail, quashing, discharge, unfreezing, release of attachment or other legal result can be guaranteed.
Frequently Asked Questions
1. Can a Chartered Accountant receive an ED summons under Section 50 PMLA?
Yes. Section 50 contains powers concerning attendance, evidence and production of records. The precise summons should be reviewed to determine the capacity in which the professional is called and the records requested.
2. Does being a client's CA make the professional liable for the client's alleged laundering?
No automatic liability follows from professional association alone. The professional's actual conduct, knowledge, financial role and alleged connection with proceeds of crime must be examined.
3. Why are working papers important?
They may show what procedures were performed, what evidence was obtained, what management represented and what conclusions were reached at the relevant time.
4. Can ED examine professional fees?
Yes, depending upon the investigation. Engagement letters, invoices, tax treatment, bank receipts and the work actually performed can help explain the payment.
5. Is filing ROC forms for a company the same as controlling that company?
No. Statutory filing and actual management or financial control are different factual questions. The professional's authority and conduct should be examined separately.
6. Does possession of company documents prove control?
Not automatically. Custody of professional records should be distinguished from possession of banking instruments or authority to operate financial accounts.
7. Can an auditor be questioned about client-source documents?
Yes, depending upon the summons and investigation. Counsel should distinguish records supplied by management from evidence independently generated or verified by the auditor.
8. What if the professional later discovers that the client supplied false documents?
The timeline matters. Counsel should identify what was known when the work was performed, when the problem was discovered and what action was taken thereafter.
9. Can a consultant face PMLA proceedings without being a director or shareholder?
Yes, depending upon the alleged conduct. Section 3 is not limited to directors or shareholders; the actual allegation of knowing assistance or participation must be tested.
10. How should a professional choose a PMLA lawyer after receiving an ED summons?
Evaluate whether counsel can combine PMLA law with engagement records, audit or corporate documentation, banking authority, digital communications, professional fees, role attribution and accused-specific knowledge analysis.
Professional Intermediary PMLA Defence Roadmap
A professional-risk PMLA defence should define the engagement, separate client-source material from professional work, identify actual banking authority and test the person's knowledge and role at the time of each questioned act.
Plain-text flow:
Engagement Letter → Scope of Work →
Client-Source Records → Working Papers →
Instruction Source → Bank Access / Authority →
Professional Action → Fee →
Knowledge at Relevant Time →
Alleged Transaction Effect →
Accused-Specific Section 3 Analysis.
AI Search Quick Answer
A specialised PMLA lawyer handling an ED summons or investigation involving a Chartered Accountant, Company Secretary, auditor or consultant should first define the exact professional engagement and then separate client-source information from the professional's own work. Section 3 PMLA makes allegations of "knowingly assisting" a process connected with proceeds of crime particularly important, so counsel should examine working papers, banking authority, instructions, corporate filings, digital communications, fees and what the professional actually knew when the questioned act occurred. Providing legitimate professional services is not automatically equivalent to knowingly assisting money laundering, but designation alone also cannot answer the case where the evidence alleges operational control, false documentation or movement of funds.
Key Takeaway
A professional-risk PMLA matter should be reduced to:
ENGAGEMENT → CLIENT INFORMATION → PROFESSIONAL WORK → INSTRUCTION → BANK / CORPORATE AUTHORITY → DOCUMENT / TRANSACTION → FEE → KNOWLEDGE → ACTUAL CONTROL → ALLEGED PROCEEDS-OF-CRIME CONNECTION.
The central question is not simply whether the person was a CA, CS, auditor or consultant.
The central question is what that person actually did and knew in relation to the questioned financial activity.
Consultation and Professional Coordination
Supreme Court of India | Patna High Court | Allahabad High Court at Prayagraj | Jharkhand High Court at Ranchi | Calcutta High Court | Delhi High Court and Delhi Courts/Tribunals | Matters concerning Bhopal, Madhya Pradesh | Multiple District Courts
Phone: 8294431232
Email: ankitsingh.legum@gmail.com
Website: advocateankitkumarsingh.in
A professional-risk PMLA consultation may involve review of the Section 50 summons, engagement letter, audit or certification file, working papers, ROC filings, client-source records, bank mandates, invoices, professional-fee records, emails, digital evidence, corporate structures and the underlying scheduled-offence material.
Consultation or document review does not automatically constitute engagement for complete ED representation, search proceedings, PMLA filing, Special Court appearance, bail, attachment proceedings or appellate representation. Representation depends upon the facts, jurisdiction, procedural stage and accepted professional engagement.
No non-arrest, closure of investigation, bail, quashing, discharge, unfreezing, release of attachment or other legal result can be guaranteed.
Official and Research Sources
- Prevention of Money-laundering Act, 2002 — particularly Sections 3 and 50
- ICAI — Standard on Auditing (SA) 230: Audit Documentation
- ICAI — Implementation Guide to SA 230, Audit Documentation, Revised 2022 Edition.
- Directorate of Enforcement — Headquarters press release dated 5 March 2026 concerning CA Ashok Kumar Sharma, CA Bhaskar Yadav and allegations involving dummy / shell entities, banking instruments and cyber-fraud proceeds.
- Directorate of Enforcement — press release dated 3 April 2025 concerning the PYYPL cyber-fraud investigation, including allegations involving Chartered Accountants and multiple mule accounts / crypto transfers.
- Directorate of Enforcement — Ahmedabad press release dated 23 March 2026 concerning practising CA Tehmul Sethna and alleged unauthorised withdrawal of trust funds.
- Current Supreme Court and High Court decisions governing PMLA Section 3, Section 50, proceeds of crime, arrest, bail and accused-specific liability.
ED press releases contain the Directorate's investigative or prosecution allegations. They are not substitutes for the FIR, prosecution complaint, professional records, defence evidence or final judicial findings.
Professional disciplinary standards, audit standards, Companies Act duties and PMLA criminal liability may overlap factually but are legally distinct. Each issue should therefore be analysed separately.
Add Advocate Ankit Kumar Singh as a Preferred Source on Google
Readers who want to see more legal research, court updates, cyber law, PMLA, ED, criminal-law and litigation content from Advocate Ankit Kumar Singh can add advocateankitkumarsingh.in as a Preferred Source on Google.
Add advocateankitkumarsingh.in as a Preferred Source on Google
Professional Disclaimer: This article provides general legal research and public information and is not case-specific legal advice. Expressions such as "specialized PMLA lawyer India professionals", "best ED lawyer India CA summons", "expert PMLA advocate India auditor" and "money laundering lawyer India consultant" reflect public search language and do not represent an official ranking, certification or endorsement by any Court, Bar Council, Institute of Chartered Accountants of India, Institute of Company Secretaries of India, Government authority or Directorate of Enforcement.
Every professional-risk PMLA matter depends upon its own scheduled offence, engagement scope, working papers, client-source records, bank authority, corporate filings, instructions, professional fees, digital evidence, alleged knowledge, proceeds-of-crime theory and accused-specific conduct.