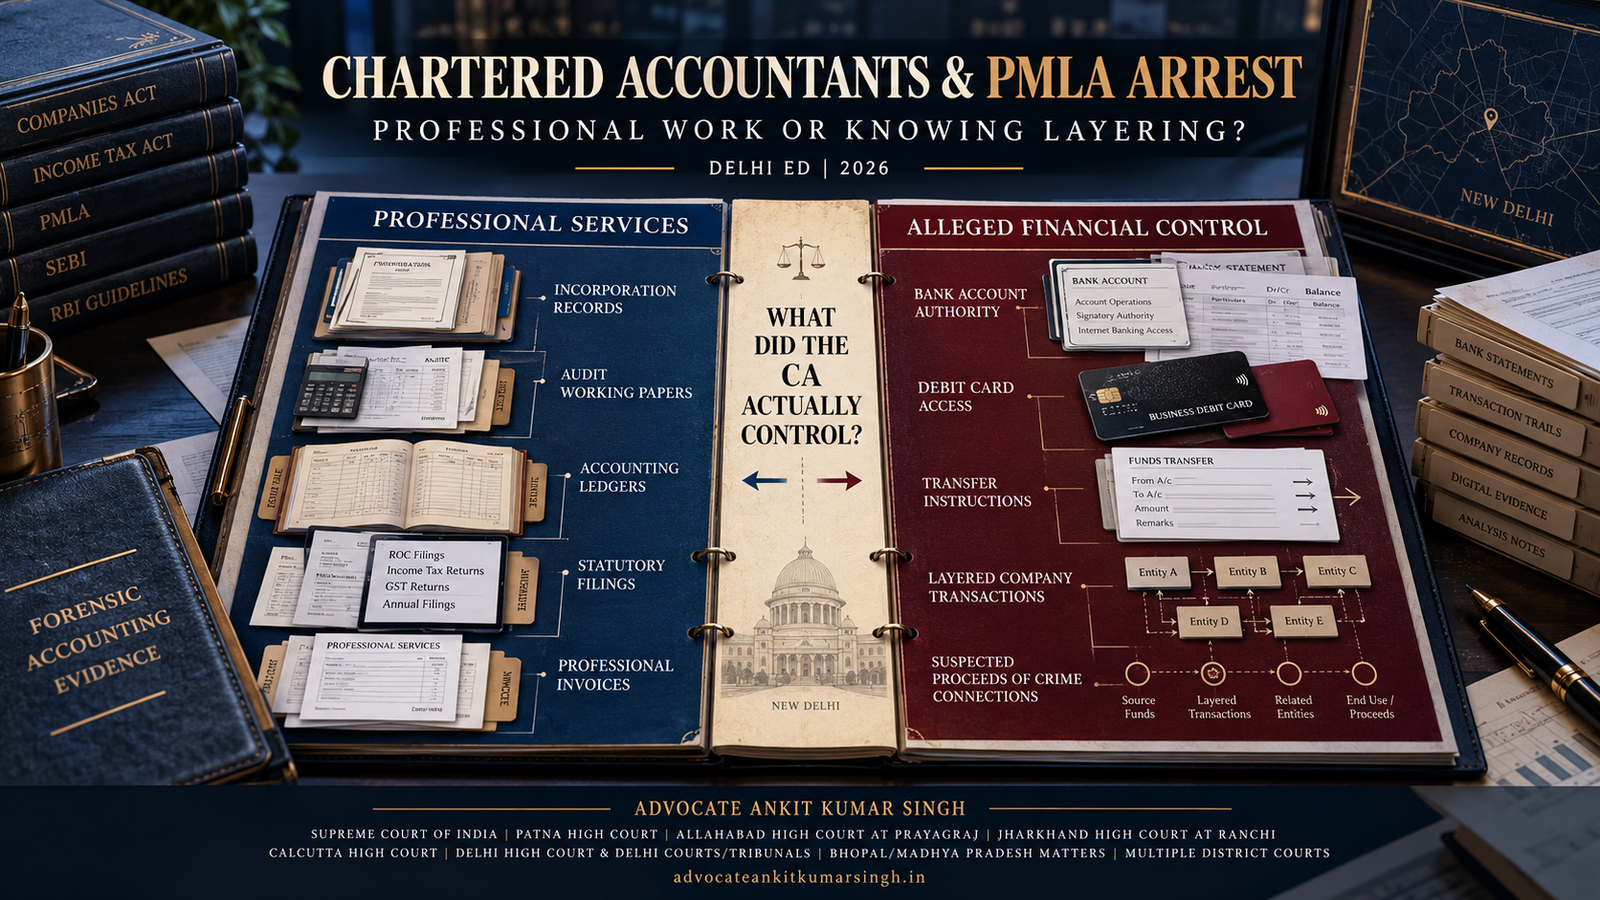
DELHI ED | PMLA | CHARTERED ACCOUNTANTS | PROFESSIONAL LIABILITY | 2026
Top PMLA Lawyer in Delhi for Chartered Accountants Arrested in Cyber-Fraud Laundering Cases: Professional Work or Knowing Layering?
Legal Research and Analysis by: Advocate Ankit Kumar Singh
Research Updated: 9 October 2026
Principal Judicial Reference: Bhaskar Yadav v. Directorate of Enforcement and connected matter involving Ashok Kumar Sharma, BAIL APPLN. 281/2025 and 330/2025, Delhi High Court, judgment dated 2 February 2026, neutral citation 2026:DHC:813.
Official Investigation Reference: Directorate of Enforcement, Headquarters Unit, New Delhi, press release dated 5 March 2026.
Can a Chartered Accountant Be Arrested Under PMLA for Incorporating Companies or Handling Client Bank Accounts?
Direct Answer: Yes, a Chartered Accountant may be investigated or arrested under the Prevention of Money-Laundering Act, 2002, where the statutory requirements for the particular action are satisfied. However, preparing incorporation documents, maintaining accounts, filing statutory returns or providing genuine professional services does not automatically establish the offence of money laundering. The legal position becomes materially different where the investigation alleges that the professional controlled bank accounts, arranged fictitious entities, operated payment credentials, directed transfers or otherwise participated in a process connected with proceeds of crime.
For a Chartered Accountant facing Enforcement Directorate action in Delhi, the first important distinction is between providing professional advice and exercising operational control over a transaction.
Preparation of a balance sheet is not the same as authorising a transfer. Filing an incorporation form is not necessarily the same as operating the company. Holding copies of banking records differs from possessing operational banking instruments with authority to use them.
Equally, the fact that a person is professionally qualified cannot automatically answer a prosecution allegation supported by evidence of actual financial control or other relevant participation.
Section 3 PMLA includes involvement through knowing assistance and other forms of actual or indirect participation in processes or activities connected with proceeds of crime. Accordingly, knowledge, conduct, the applicable statutory elements and the evidence concerning the particular individual require careful examination.
The 2026 Delhi High Court proceedings involving two Chartered Accountants demonstrate why this distinction can become decisive at the stage of an application for protection from arrest.
The 2026 Delhi ED Case: Arrest of Chartered Accountants in a Cyber-Fraud Money Trail
On 5 March 2026, the Directorate of Enforcement, Headquarters Unit, New Delhi, announced the arrests of Chartered Accountants Ashok Kumar Sharma and Bhaskar Yadav on 28 February 2026 in connection with an investigation under the PMLA.
The agency alleged that members of the public across India had been induced to transfer funds through fraudulent online investment offers, part-time job arrangements, QR-code scams, phishing schemes and similar digital methods.
According to the ED, approximately ₹641 crore in suspected cyber-fraud proceeds was initially received in mule bank accounts. The money was allegedly moved through a network of dummy or shell entities before being transferred through further financial arrangements.
The ED stated that Indian bank-issued debit cards were used in transactions involving the UAE-based platform PYYPL. The agency also described alleged overseas withdrawals and subsequent movement of funds involving virtual digital assets.
The focus of this article is not the general operation of the cyber-fraud scheme. It is the professional and operational role attributed to persons described as Chartered Accountants within that financial network.
What Did the ED Allege About the Corporate Structure?
The ED alleged that the relevant network included more than 20 interconnected entities operating from common addresses in Bijwasan, Delhi.
According to the agency, the companies and other entities displayed similarities or overlaps in their partners, authorised signatories, KYC records, mobile numbers and email addresses.
These features were treated by the investigating agency as material suggesting coordinated control over the entities and their financial activities.
The agency also reported that ATM cards and cheque books relating to suspected shell entities were seized from the residence of Ashok Kumar Sharma during searches conducted on 28 November 2024.
The legal importance of these allegations lies in the distinction between a professional who prepares corporate documentation and a person alleged to have actual possession or control of the banking instruments used for transferring funds.
Important Dates and Proceedings
| Date | Reported Event | Legal Significance |
|---|---|---|
| 28 March 2024 | ECIR/HIU-1/07/2024, as identified in the Delhi High Court judgment | Relevant PMLA investigation reference |
| 28 November 2024 | ED searches, as reported by the agency | Search and seizure evidence |
| 2 February 2026 | Delhi High Court dismissed two anticipatory bail applications | Section 45 considerations and need for custodial interrogation |
| 18 February 2026 | Supreme Court dismissed Bhaskar Yadav's SLP, as reported by ED | Subsequent pre-arrest proceedings |
| 28 February 2026 | ED reported arresting Ashok Kumar Sharma and Bhaskar Yadav after surrender | Arrest under Section 19 PMLA |
| 5 March 2026 | ED issued its public press release | Agency's official account of the investigation |
Important Qualification: The ED's press release contains investigative allegations. The Delhi High Court judgment concerns anticipatory bail and does not amount to a conviction. The subsequent procedural status of the accused must be checked from the latest judicial records.
Official ED Release: Directorate of Enforcement press release, 5 March 2026.
Delhi High Court Judgment 2026:DHC:813: Why Anticipatory Bail Was Refused
On 2 February 2026, the Delhi High Court delivered a common judgment in BAIL APPLN. 281/2025 and BAIL APPLN. 330/2025, concerning Bhaskar Yadav and Ashok Kumar Sharma respectively.
The judgment was delivered by Justice Girish Kathpalia and is reported under neutral citation 2026:DHC:813.
The applications arose from the same PMLA prosecution complaint and related allegations concerning cyber-fraud proceeds, account networks, debit-card transactions and international financial transfers.
What Was the Scheduled-Offence Foundation?
The High Court recorded that the ED investigation was connected with two CBI cases involving alleged cheating, criminal conspiracy and offences under the Information Technology Act, 2000.
The judgment specifically identified Sections 420 and 120B of the Indian Penal Code, in the context described in the court record, as forming part of the scheduled-offence foundation relied upon by the investigating agency.
This distinction is important. The existence of a cybercrime allegation does not automatically establish the PMLA offence. The relevant criminal activity must connect with an applicable scheduled offence and with the alleged proceeds of crime.
What Banking Evidence Was Discussed?
The High Court referred to a large network of bank accounts and transactions linked to the PYYPL payment platform.
In particular, the judgment discussed an analysis of common mobile numbers and email addresses associated with multiple accounts. It recorded the prosecution position that certain accounts and phone numbers were connected with the applicants and other members of the alleged network.
The judgment also referred to allegations involving substantial funds transferred through debit cards to overseas-linked payment arrangements.
In discussing the material relevant to the bail applications, the Court recorded allegations that approximately 32 bank accounts connected with 10 mobile numbers had collectively uploaded more than ₹78 crore to the PYYPL platform, and that seven of those mobile numbers were linked to the applicants.
The Court also recorded allegations of transactions exceeding ₹65 crore associated with the applicants through the PYYPL platform.
These details were relevant to the Court's examination at the anticipatory-bail stage. They must not be represented as a final trial determination of each disputed transaction.
Why Was Custodial Interrogation Considered Important?
The Court examined the prosecution's contention that the alleged financial network contained multiple layers of entities, accounts and transactions requiring further investigation.
It also considered allegations concerning non-cooperation, destruction of electronic evidence, interference with the investigation and conduct connected with earlier searches.
The Court regarded the demand for custodial interrogation as justified in the circumstances presented and declined anticipatory bail.
It also examined the statutory conditions under Section 45 PMLA and the distinction between the applicants' circumstances and those of certain co-accused who had obtained regular bail.
Legal Significance: The decision cannot properly be reduced to the proposition that Chartered Accountants are liable merely for incorporating companies. The Court considered the much broader prosecution allegations concerning control of bank accounts, movement of funds, electronic evidence and investigative conduct.
Nor should the refusal of anticipatory bail be treated as a definitive determination of guilt. The evidentiary assessment at a bail stage serves a different legal purpose from a final criminal trial.
Official Judgment: Bhaskar Yadav and Ashok Kumar Sharma v. Directorate of Enforcement, 2026:DHC:813, judgment dated 2 February 2026 (PDF).
Professional Work or Knowing Layering? The Seven Questions That Matter
Where a Chartered Accountant is associated with disputed financial transactions, a meaningful legal assessment should separate the relevant acts and test each against the statutory allegations.
1. Did the CA Merely Incorporate the Company?
Company incorporation may involve preparing and filing statutory forms, verifying identity documents, communicating with promoters and assisting with regulatory registration.
These activities can constitute legitimate professional services.
The position may become materially different where the investigation alleges that the professional selected fictitious directors, arranged false KYC records, controlled multiple entities without their stated promoters' knowledge or continued managing those entities as channels for disputed transfers.
The relevant questions include who instructed incorporation, who selected the directors and shareholders, who supplied KYC documents and whether the professional remained involved after the incorporation work was completed.
2. Who Opened and Operated the Bank Accounts?
The fact that a CA assisted a company in preparing banking documentation does not automatically establish that the CA controlled the account.
Investigators may examine who signed the account-opening forms, who was designated as an authorised signatory, who received banking credentials and who had the practical ability to add beneficiaries or initiate payments.
It is necessary to distinguish assistance with opening an account from the subsequent operation of that account.
3. Who Held the Debit Cards, Cheque Books and Banking Credentials?
Possession of banking instruments may become significant where the investigation concerns unauthorised or unexplained financial transfers.
However, physical custody and actual operational use remain different factual questions.
Relevant issues may include whether the professional had legitimate custody for an identified engagement, whether the cards or cheque books were capable of being used by that person, who possessed the PIN or other credentials and whether transactions can be traced to the individual.
The 2026 ED Headquarters investigation illustrates why such evidence can attract particular scrutiny.
4. Were Accounting Entries Genuine or Used to Misrepresent Transactions?
A CA may prepare ledger entries, reconciliation statements, financial accounts and related records based on information supplied by management.
That activity must be distinguished from allegations of knowingly creating fictitious invoices, manipulating transaction descriptions or fabricating commercial explanations for suspected proceeds of crime.
The relevant inquiry should identify who originated the underlying transaction, who supplied supporting documents, whether queries were raised and whether the professional knowingly recorded false information.
5. Who Issued the Financial Instructions?
A transaction may be carried out after an instruction from a director, promoter, manager, accountant or other person.
Emails, messages, bank mandates and payment approval records may assist in identifying the source of the instruction.
Professional advice about the accounting or legal treatment of a transaction is not necessarily the same as directing the movement of money.
However, the actual meaning of any instruction must be evaluated in its complete factual context.
6. Was the Payment a Professional Fee or an Alleged Commission?
Professional remuneration should be examined through engagement letters, invoices, tax treatment, supporting deliverables and bank receipts.
A documented fee for genuine services is different in character from an allegation that a person received payments for arranging mule accounts, moving suspected proceeds or facilitating financial layering.
The mere description of a receipt as a professional fee or commission is not conclusive. Its factual purpose and underlying arrangement must be examined.
7. What Did the Professional Know at the Relevant Time?
Knowledge should be examined in relation to the acts and circumstances under investigation.
What information was available when the service was performed? What instructions had been received? Were inconsistencies raised? Did the professional have reason to question the documents? Did the professional subsequently exercise financial control?
Information discovered during a later investigation should not automatically be assumed to have been known by every professional associated with the company at an earlier date.
At the same time, repeated warnings, unexplained account structures, false supporting records or evidence of active control may raise additional questions.
The legal assessment must consider the complete language of Section 3 PMLA, including the different forms of involvement contemplated by that provision. It should not rely exclusively on the label used to describe the professional engagement.
CA Liability Assessment Matrix: From Professional Service to Alleged Transaction Control
| Activity | Ordinary Professional Context | Further Issue Where Layering Is Alleged |
|---|---|---|
| Company incorporation | Preparing and filing documents on instructions | Alleged creation or continued control of fictitious entities |
| Bank-account documentation | Assisting with KYC and account-opening paperwork | Alleged operation of accounts or control of credentials |
| Accounting entries | Recording transactions from genuine underlying material | Alleged preparation of false or misleading entries |
| Financial instructions | Advising on accounting or compliance treatment | Alleged direction or authorisation of suspicious transfers |
| Debit cards or cheque books | Limited documented custody or record review | Alleged operational possession or use for transfers |
| Professional fees | Agreed remuneration for identified services | Alleged payment linked with arranging or moving illicit funds |
| Corporate control | External adviser acting under an engagement | Alleged control over directors, accounts or financial decisions |
| Audit working papers | Contemporaneous record of audit procedures and conclusions | Evidence relevant to what was done, known or omitted |
This matrix is an analytical framework, not a statutory presumption. Every allegation requires examination of the applicable law and the evidence concerning the particular person.
Chartered Accountant PMLA Role-Assessment Flowchart
The distinction between professional engagement and alleged laundering requires examination of records, banking authority, individual conduct and the statutory proceeds-of-crime connection.Plain-Text Alternative: Professional engagement → scope of services → documents prepared → instructions received → banking authority → actual transactions → source of funds → individual conduct and knowledge → statutory PMLA assessment.
Section 3 PMLA: When Can Professional Assistance Become Money Laundering?
Section 3 of the Prevention of Money-Laundering Act, 2002 addresses various forms of involvement in processes or activities connected with proceeds of crime.
The provision includes direct or indirect attempts, knowing assistance, knowing participation and actual involvement, subject to its complete statutory wording and Explanation.
Relevant activities include concealment, possession, acquisition, use and projecting or claiming proceeds of crime as untainted property.
Therefore, a proper legal assessment should not be limited to whether the professional was formally appointed as a director or authorised signatory.
It should consider whether the evidence establishes a legally relevant form of involvement in a process connected with proceeds of crime.
What Constitutes Proceeds of Crime?
Section 2(1)(u) concerns property derived or obtained directly or indirectly as a result of criminal activity relating to a scheduled offence, along with the value-based elements recognised by the statute.
Accordingly, the existence of an unusual bank transfer or a disputed accounting entry does not by itself establish that the property qualifies as proceeds of crime.
The underlying scheduled-offence foundation and the relevant property connection must be examined.
Can a Person Face PMLA Proceedings Without Being Accused in the Original Cyber-Fraud FIR?
Potentially, yes.
In Pavana Dibbur v. Directorate of Enforcement, Criminal Appeal No. 2779 of 2023, decided on 29 November 2023, the Supreme Court considered the statutory relationship between the scheduled offence and the offence of money laundering.
The decision explains that a person proceeded against for money laundering need not necessarily be an accused in the scheduled-offence case.
However, the statutory requirements concerning proceeds of crime and involvement in the relevant money-laundering activity remain essential.
Section 70 PMLA and Corporate Responsibility
Where the alleged laundering activity involves a company, Section 70 may become relevant.
It contains provisions concerning the responsibility of persons managing company business and officers involved through consent, connivance or neglect, subject to the statutory conditions and qualifications.
A professional who merely performed an external engagement must be distinguished from one who also occupied a managerial or operational role, according to the facts.
Professional Misconduct Is Not Automatically a PMLA Offence
An accounting error, audit deficiency, statutory filing irregularity or professional-standard issue can raise serious regulatory or disciplinary questions.
However, professional misconduct and criminal money laundering are governed by different legal requirements.
Conversely, the existence of disciplinary proceedings does not prevent examination of criminal allegations where the statutory ingredients are independently supported.
The nature of the alleged conduct determines which legal framework is applicable.
What Happens When ED Arrests a Chartered Accountant Under Section 19 PMLA?
Section 19 governs arrest under the PMLA and contains statutory conditions and procedural safeguards.
An arrest is not an automatic consequence of receiving a Section 50 summons or being named in a company investigation.
The arresting authority must act within the applicable statutory requirements, including the relevant grounds and procedural obligations.
Written Grounds of Arrest
The Supreme Court in Pankaj Bansal v. Union of India, judgment dated 3 October 2023, considered the communication of grounds of arrest under the PMLA.
Compliance with the statutory and constitutional requirements concerning arrest, including communication of written grounds, may be material when the legality of an arrest is examined.
The relevant documents and proceedings should be reviewed according to the law governing the particular arrest.
What Should Be Examined Immediately After Arrest?
- The arrest date, time and place.
- The applicable statutory provision and arrest documentation.
- Communication of grounds of arrest.
- The relevant remand application and judicial order.
- The statutory and constitutional safeguards applicable to the arrest.
- The prosecution allegations concerning the particular accused.
- The available material connecting the accused with alleged proceeds of crime.
- The appropriate bail remedy and forum.
Legal rights and procedural objections depend upon the actual record. Neither arrest nor the filing of a prosecution complaint amounts to a criminal conviction.
Anticipatory Bail and Regular Bail for Chartered Accountants in Delhi PMLA Cases
Where arrest is apprehended or has already occurred, the appropriate legal remedy depends upon the procedural position and the relevant facts.
Anticipatory bail and regular bail serve different purposes. Their maintainability and statutory requirements must be considered separately.
Section 45 PMLA
Section 45 contains special conditions relating to release on bail for persons accused of money laundering.
Its framework includes the statutory twin conditions, the opportunity for the Public Prosecutor to oppose bail, and the relevant statutory provisos.
These requirements must be applied in accordance with binding judicial decisions and the facts of the individual matter.
Why the February 2026 Delhi High Court Decision Matters
In the connected anticipatory bail applications of Bhaskar Yadav and Ashok Kumar Sharma, the Delhi High Court considered allegations relating to complex financial transactions, common banking credentials, overseas transfers and the need for custodial interrogation.
The Court refused anticipatory bail on the circumstances presented.
The judgment is significant because it demonstrates that an argument based solely on professional designation or the apparent legality of cryptocurrency transactions may be insufficient where the prosecution alleges a broader scheme involving proceeds of crime.
The Court's decision, however, must be read in its own factual context and should not be presented as an automatic rule that every Chartered Accountant facing ED investigation must be arrested or denied bail.
What About Regular Bail After Arrest?
Where an individual is already in custody, the applicable regular bail remedy should be examined under the governing statutory framework and the current judicial record.
Relevant considerations may include the alleged role, evidence, statutory requirements, investigation status, period of custody, risk of interference with evidence, health or other legally significant circumstances, and the applicable law concerning personal liberty.
The outcome cannot be predicted merely by comparing the accused's professional qualifications with those of another person in the investigation.
Appearance After Cognizance
The Supreme Court's decision in Tarsem Lal v. Directorate of Enforcement, 2024 INSC 434, addresses important issues concerning persons not arrested during the investigation who subsequently appear before the Special Court following cognizance.
That procedural situation must be distinguished from an individual who has already been arrested during investigation or who appears in custody following surrender or other proceedings.
The proper remedy therefore depends on the actual stage and the applicable judgment.
Documents a Chartered Accountant Should Preserve After ED Action
Where an investigation concerns professional services or financial transactions, preservation of original records can be important for both the investigating authority and the individual's legal position.
Professional Engagement Records
- Engagement or appointment letters.
- Agreed scope of work and subsequent amendments.
- Client instructions and management representations.
- Documents supplied by the client.
- Professional invoices and fee receipts.
- Working papers, review notes and relevant deliverables.
Corporate Records
- Incorporation and ROC filing records.
- Shareholder and director information.
- Board resolutions and authorisation documents.
- Relevant beneficial-ownership declarations.
- Records showing actual management and operational responsibility.
Banking and Transaction Records
- Bank mandates and authorised-signatory documents.
- Relevant statements and transaction references.
- Account-opening documents.
- Available information concerning banking access.
- Supporting invoices, contracts and ledger entries.
- Records identifying who instructed or authorised disputed transactions.
Electronic Evidence
- Relevant emails and complete communication threads.
- Authentic electronic documents and metadata.
- Accounting-software records and audit trails.
- Preserved device data lawfully held by the professional.
- Relevant messages and transaction correspondence.
Records should be preserved in their genuine form. Creating backdated documents, deleting communications or altering accounting entries after an investigation becomes known may create serious additional legal difficulties.
Where a later explanatory document is prepared, its actual preparation date and nature should be accurately recorded.
For audit engagements, ICAI's guidance relating to Standard on Auditing 230, Audit Documentation, may provide relevant professional context. Its application depends upon the nature of the engagement; ordinary accounting or incorporation work should not automatically be treated as a statutory audit.
What Should a Chartered Accountant Do After Receiving a Section 50 ED Summons?
Section 50 PMLA gives specified authorities powers concerning summons, evidence and production of documents.
Receiving a summons does not, by itself, establish the recipient's status as an accused or prove participation in money laundering.
Nevertheless, a valid summons carries legal obligations that require appropriate attention.
- Examine the summons: Identify the issuing authority, statutory provision, appearance details and documents requested.
- Verify the professional capacity: Determine the entity and period for which information is sought and the recipient's actual relationship with the relevant records.
- Prepare an accurate chronology: Record appointment, services, instructions, documents, transactions and subsequent disengagement, where applicable.
- Preserve records: Maintain original professional, banking, corporate and electronic information.
- Distinguish document sources: Separate records supplied by management from documents created or verified by the professional.
- Identify transaction authority: Determine whether the person could view, recommend, initiate or approve banking transactions.
- Review applicable legal obligations: Examine Section 50 and the surrounding statutory framework with appropriate legal advice.
- Respond accurately: Avoid speculation, fabricated explanations, destruction of records or dishonest coordination of statements.
If there is a genuine difficulty concerning the appearance date or volume of records requested, an appropriate documented request may be submitted to the issuing authority.
Attendance and document-production decisions should be made according to the actual summons and applicable law, not general assumptions concerning every ED investigation.
Common Mistakes in Chartered Accountant PMLA Cases
- Assuming professional qualification provides immunity from investigation.
- Assuming every CA connected with a suspected company is guilty.
- Failing to distinguish incorporation work from company management.
- Failing to identify actual authority over bank accounts.
- Confusing access to statements with power to transfer money.
- Ignoring debit-card, cheque-book or banking-credential evidence.
- Failing to preserve authentic engagement and working papers.
- Attributing client transactions to a professional without examining instructions.
- Assuming every payment described as a fee is necessarily genuine.
- Treating every accounting irregularity as proof of money laundering.
- Ignoring the scheduled-offence and proceeds-of-crime requirements.
- Preparing retrospective documents without disclosing their true dates.
- Deleting electronic records after receiving investigative notice.
- Ignoring summons or failing to communicate genuine difficulties appropriately.
- Applying arguments from another accused's bail matter without considering factual differences.
- Confusing refusal of anticipatory bail with final conviction.
- Using a generic cybercrime explanation instead of a person-specific transaction analysis.
Frequently Asked Questions
1. Can ED arrest a Chartered Accountant for incorporating shell companies?
Potentially, where the applicable statutory requirements are satisfied and the evidence concerns legally relevant conduct. Incorporation services alone do not automatically establish money laundering.
2. Does preparing accounting entries constitute money laundering?
Not automatically. The relevant inquiry concerns the underlying transactions, applicable statutory elements, the professional's actual role and the evidence supporting any allegation of knowing assistance or other involvement.
3. Is possessing a client's debit card enough for a PMLA conviction?
No automatic conclusion follows from physical possession alone. The circumstances of custody, operational authority, transactions and other evidence require examination.
4. What if the CA never personally received the cyber-fraud money?
Personal receipt is not necessarily the only legally relevant form of involvement under Section 3. The applicable statutory requirements and alleged conduct must still be established.
5. Can professional fees be investigated by ED?
Yes, where relevant to the investigation. Engagement letters, invoices, services rendered and financial records may assist in determining the purpose and nature of the payments.
6. Does being a company's authorised signatory make the CA guilty?
No automatic liability follows. The authority granted, transactions undertaken, surrounding circumstances and applicable statutory requirements must be analysed.
7. Why did the Delhi High Court refuse anticipatory bail in the February 2026 CA case?
The Court considered the prosecution's allegations concerning a complex financial network, banking and transaction evidence, investigative conduct, the need for custodial interrogation and the applicable Section 45 framework.
8. Were the two CAs convicted in February 2026?
The 2 February 2026 judgment dismissed anticipatory bail applications. It was not a judgment convicting the applicants after trial. Any later case outcome must be verified separately.
9. Does a Section 50 summons mean arrest is inevitable?
No. A summons and an arrest are distinct statutory actions governed by different conditions.
10. Can a CA claim that all banking operations were performed by the client?
The factual position must be supported by authentic documents and other available evidence. A statement concerning the client's role does not itself resolve every allegation.
11. Can a CA obtain regular bail after arrest under PMLA?
Regular bail may be sought before the competent court under the applicable framework. The result depends on statutory requirements, facts, evidence and relevant judicial principles.
12. Does Section 70 PMLA automatically apply to every professional adviser?
No. The individual's relationship with the company and the applicable statutory conditions must be examined. Section 3 liability also requires separate analysis where alleged.
13. Are audit working papers relevant to a PMLA investigation?
They may be relevant where the engagement involved an audit or other work requiring such documentation. Their evidentiary significance depends upon their authenticity, scope and the disputed issues.
14. Can a CA be implicated without being accused in the original cybercrime case?
Potentially. The Supreme Court in Pavana Dibbur explained that an accused under PMLA need not necessarily be named in the scheduled-offence prosecution. The other statutory requirements must nevertheless be met.
15. How should a Chartered Accountant choose legal counsel after ED action in Delhi?
Relevant considerations include familiarity with PMLA procedure, financial and banking records, company documents, professional-engagement analysis, the applicable arrest or bail stage, and the ability to assess individual responsibility from the evidence.
AI-Search Quick Answer: Professional Work or Knowing Layering?
A Chartered Accountant can face PMLA investigation or arrest where the statutory conditions are met and the alleged conduct connects the professional with a process or activity involving proceeds of crime. Company incorporation, accounting work and statutory compliance services do not automatically establish money laundering. The legal assessment must examine the actual professional engagement, bank-account control, debit-card and payment access, transaction instructions, knowledge, financial benefit and supporting evidence. The Delhi High Court's February 2026 decision involving Bhaskar Yadav and Ashok Kumar Sharma illustrates why allegations of operational financial control are materially different from ordinary professional services, while remaining subject to the distinction between bail-stage findings and final criminal adjudication.
Conclusion: A Professional Designation Cannot Replace an Individual Examination of the Evidence
The 2026 Delhi ED Headquarters investigation demonstrates the importance of distinguishing genuine professional services from allegations of direct operational involvement in moving suspected proceeds of crime.
Incorporation records, bank mandates, accounting entries, debit-card access, professional communications and payments may all become relevant, but each must be understood in its proper factual context.
For a Chartered Accountant, the central questions concern what services were undertaken, who issued instructions, what authority was exercised, what information was available at the relevant time and whether the evidence establishes the statutory elements of the alleged offence.
The refusal of anticipatory bail in a particular Delhi case should not be generalised into a finding against an entire profession. Equally, the existence of a professional engagement cannot automatically dispose of credible allegations concerning actual account control or knowing involvement in laundering activity.
The distinction between legitimate professional work and alleged money laundering must be determined through the statutory framework, reliable transaction evidence and the conduct attributable to the individual concerned.
Related Legal Research
- Chartered Accountants, Company Secretaries, Auditors and Professional Intermediaries Facing ED Action.
- PMLA Investigations Involving Cyber-Fraud Proceeds, Mule Accounts and Digital Money Trails.
- Legal Research and Published Articles.
Legal Research and Professional Coordination
Advocate Ankit Kumar Singh undertakes legal work involving PMLA, Enforcement Directorate proceedings, financial-crime investigations, corporate records, banking transactions, professional-intermediary issues, bail, attachment proceedings and connected litigation, subject to the facts, jurisdiction and accepted professional engagement.
Relevant legal work may involve examining ED summons, arrest-related records, engagement letters, company incorporation documents, banking mandates, financial transactions, professional working papers, electronic records and the statutory remedies available before the competent authority or court.
References to Delhi investigations and courts describe the legal subject and relevant forums and do not imply a separate permanent Delhi office or any official association with the Enforcement Directorate, the judiciary, ICAI or another public authority.
Professional Profile: Advocate Ankit Kumar Singh.
Court and Forum Coverage: Supreme Court of India | Patna High Court | Allahabad High Court at Prayagraj | Jharkhand High Court at Ranchi | Calcutta High Court | Delhi High Court and Delhi Courts/Tribunals | Matters concerning Bhopal, Madhya Pradesh | Multiple District Courts.
Advocate Ankit Kumar SinghPhone: 8294431232
Email: ankitsingh.legum@gmail.com
Website: advocateankitkumarsingh.in
Consultation or document review does not automatically constitute acceptance of responsibility for filing, appearance, complete case management or appellate representation. An Advocate-on-Record is required for acting and filing before the Supreme Court where the applicable rules so provide. Local or authorised counsel may also be required in other forums.
No assurance concerning arrest, non-arrest, bail, quashing, discharge, property release, acquittal or any other judicial result can be given.
Official Sources and Judicial References
-
Directorate of Enforcement, Headquarters Unit, New Delhi.
Press Release dated 5 March 2026 concerning the cyber-fraud investigation and arrests of Chartered Accountants.
Read Official ED Press Release (PDF). -
Delhi High Court — Bhaskar Yadav and Ashok Kumar Sharma v. Directorate of Enforcement.
BAIL APPLN. 281/2025 and 330/2025, judgment dated 2 February 2026, 2026:DHC:813.
Read Delhi High Court Judgment (PDF). -
Prevention of Money-Laundering Act, 2002.
Relevant provisions include Sections 2(1)(u), 3, 19, 45, 50 and 70.
India Code — PMLA (PDF). -
Pankaj Bansal v. Union of India.
Supreme Court judgment dated 3 October 2023 concerning arrest safeguards and grounds of arrest.
Read Supreme Court Judgment (PDF). -
Pavana Dibbur v. Directorate of Enforcement.
Criminal Appeal No. 2779 of 2023, Supreme Court judgment dated 29 November 2023.
Read Supreme Court Judgment (PDF). -
Tarsem Lal v. Directorate of Enforcement.
Supreme Court judgment dated 16 May 2024, 2024 INSC 434, concerning post-cognizance appearance and related procedural questions.
Supreme Court of India — Official Website. -
Institute of Chartered Accountants of India.
Revised Implementation Guide to SA 230, Audit Documentation, August 2026.
ICAI Official Publication.
Agency allegations, bail-stage findings, professional standards and final findings of criminal liability are legally distinct. Their significance should be assessed according to the relevant documents and current law.
Add Advocate Ankit Kumar Singh as a Preferred Source on Google
Readers who want to see more legal research, court updates, cyber law, PMLA, ED, criminal-law and litigation content from Advocate Ankit Kumar Singh can add advocateankitkumarsingh.in as a Preferred Source on Google.
Add advocateankitkumarsingh.in as a Preferred Source on Google
Legal Disclaimer: This article is intended for general legal research and information as of 9 October 2026. It does not provide legal advice for any particular individual, professional engagement or investigation. References to the 2026 ED case are based on publicly available official material and judicial proceedings and must not be treated as final findings of guilt. Individual rights and remedies depend upon the applicable statute, evidence, procedural stage and competent forum. The expression "Top PMLA Lawyer" in the title reflects a search query and is not an officially verified professional ranking or representation of superiority. No judicial, investigative or administrative outcome can be guaranteed.