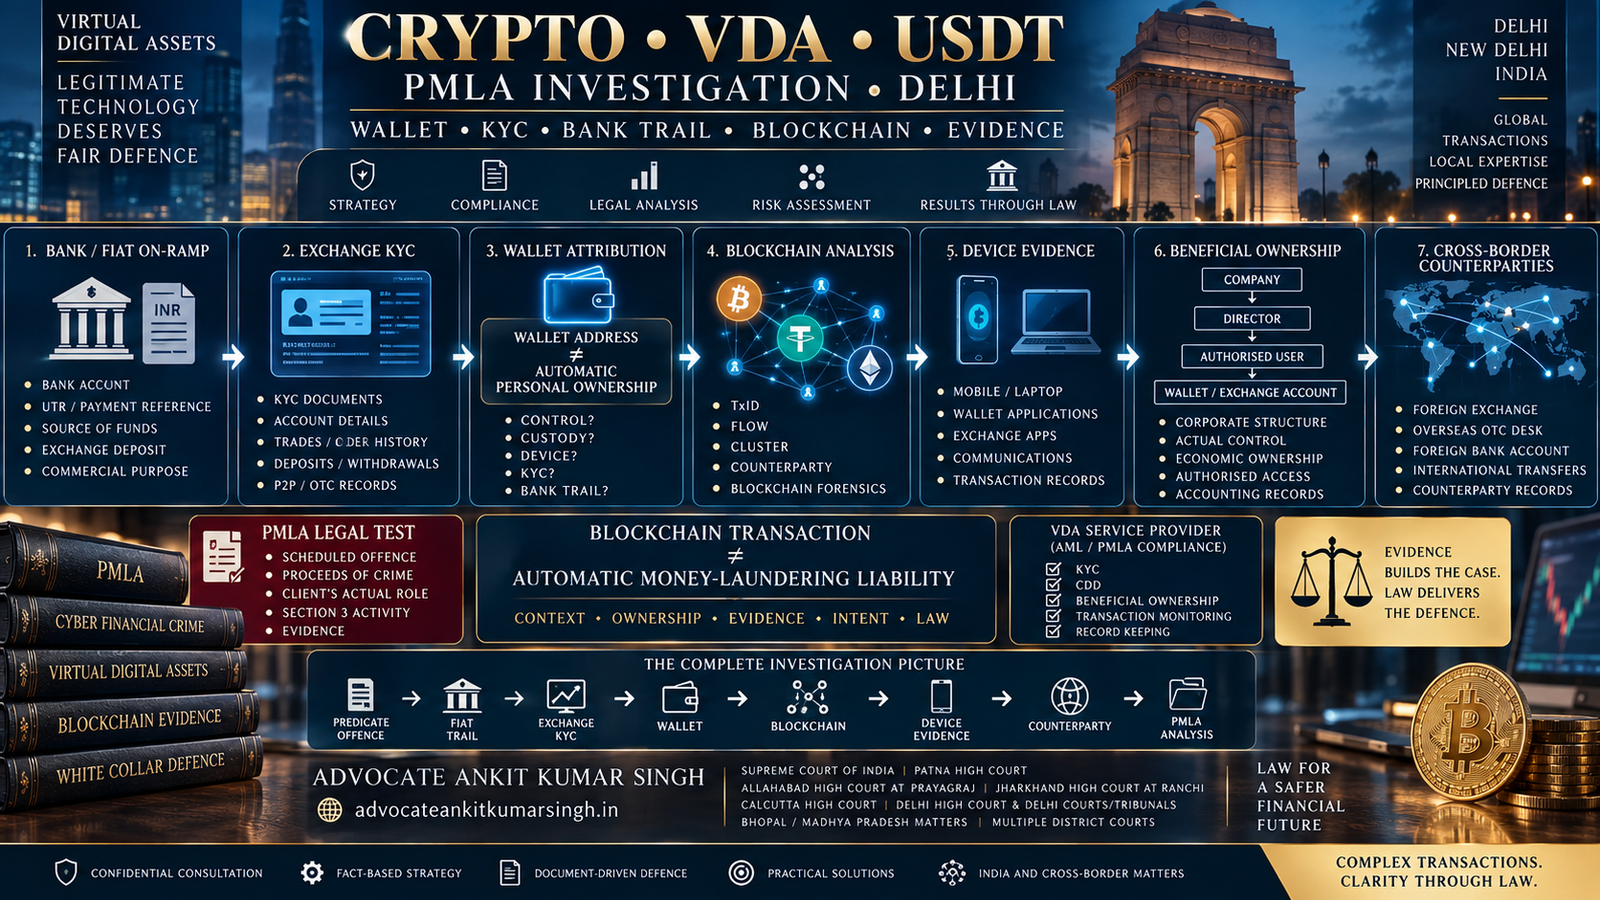
PMLA • CRYPTOCURRENCY • VDA • USDT • BLOCKCHAIN • ENFORCEMENT DIRECTORATE • DELHI / NEW DELHI
Top PMLA Lawyer in Delhi for Cryptocurrency, VDA, USDT and Blockchain Money-Laundering Investigations
Legally researched and updated: 20 September 2026
Supreme Court of India | Patna High Court | Allahabad High Court at Prayagraj | Jharkhand High Court at Ranchi | Calcutta High Court | Delhi High Court and Delhi Courts/Tribunals | Matters concerning Bhopal, Madhya Pradesh | Multiple District Courts
 Advocate Ankit Kumar Singh
Direct Answer: What Should a PMLA Lawyer Understand in a Cryptocurrency or USDT Investigation?
A cryptocurrency-linked PMLA investigation is not resolved merely by looking at a wallet address or a blockchain explorer.
The legal task is to connect—or challenge the connection between:
PREDICATE OFFENCE → ALLEGED PROCEEDS OF CRIME → BANKING ENTRY → EXCHANGE ACCOUNT → WALLET ADDRESS → BLOCKCHAIN TRANSFER → PERSON OR ENTITY → ALLEGED SECTION 3 ACTIVITY.
For founders, OTC traders, exchange users, investors and companies searching for a top PMLA lawyer Delhi crypto, best cryptocurrency money laundering lawyer Delhi, expert ED lawyer Delhi USDT or specialized PMLA advocate Delhi VDA, the meaningful issue is therefore not whether a lawyer understands the word "Bitcoin".
Counsel should understand financial tracing, PMLA doctrine, exchange records, banking evidence, beneficial ownership, blockchain attribution, digital evidence and the difference between a visible blockchain transaction and legally admissible proof that a particular person controlled it.
There is no official Court, Bar Council, Government or Enforcement Directorate ranking declaring any advocate the "top" or "best" cryptocurrency PMLA lawyer in Delhi. These expressions are used as public search-intent phrases.
Cryptocurrency Is Not Automatically Money Laundering
The use, ownership or transfer of cryptocurrency does not by itself establish the offence of money laundering.
A PMLA investigation must still be analysed through the statutory structure concerning:
- the scheduled offence;
- the alleged criminal activity;
- property alleged to constitute proceeds of crime;
- the person or entity connected with that property;
- the process or activity alleged under Section 3;
- the documentary and digital evidence relied upon by ED.
Accordingly:
CRYPTO TRANSACTION ≠ AUTOMATIC PMLA OFFENCE.
The legal character of the transaction depends on its origin, purpose, ownership, knowledge, counterparties and connection with alleged proceeds of crime.
What Is a Virtual Digital Asset?
Indian law uses the expression Virtual Digital Asset or VDA for a statutory category of digital assets.
The current Income-tax framework includes within the VDA concept specified cryptographically generated information, code, numbers or tokens representing value and capable of electronic transfer, storage or trade, together with specified NFTs and other notified digital assets.
For PMLA purposes, the critical regulatory development occurred in 2023 when specified services relating to virtual digital assets were brought within the reporting-entity framework under the Prevention of Money-laundering regime.
VDA Service Providers Are Within India's AML / PMLA Reporting Framework
The current FIU-IND framework covers specified VDA service-provider activities including:
- exchange between VDA and fiat currency;
- exchange between one or more forms of VDA;
- transfer of VDA;
- safekeeping or administration of VDA or instruments enabling control over VDA;
- participation in and provision of financial services related to an issuer's offer or sale of VDA.
FIU-IND's current VDA AML/CFT/CPF Guidelines were updated on 8 January 2026.
The framework requires relevant reporting entities to address matters such as:
- registration;
- KYC;
- customer due diligence;
- beneficial ownership;
- ongoing due diligence;
- transaction monitoring;
- suspicious-transaction reporting;
- record keeping;
- risk management.
For counsel representing a crypto business, regulatory-compliance history may therefore become part of the factual defence.
The First Skill: Wallet Attribution
Blockchain records can show that a transaction occurred between addresses. That does not automatically establish who legally owned or controlled every address.
The attribution question may require analysis of:
- exchange deposit and withdrawal records;
- KYC-linked exchange accounts;
- wallet application records;
- device evidence;
- emails;
- transaction instructions;
- company records;
- bank payments connected with acquisition of VDA;
- communications identifying the counterparty;
- custody arrangements;
- other corroborating digital evidence.
The defence should therefore distinguish:
BLOCKCHAIN ADDRESS
from
PROVEN CONTROL OR BENEFICIAL OWNERSHIP OF THAT ADDRESS.
Wallet Ownership and Wallet Control Are Not Always the Same Thing
A business may use:
- corporate exchange accounts;
- custodial wallets;
- self-custody wallets;
- treasury wallets;
- multi-user operational wallets;
- wallets operated by authorised employees;
- third-party custodians;
- OTC counterparties.
Counsel should determine:
- who beneficially owned the asset;
- who had operational access;
- who authorised the transaction;
- whose device was used;
- whether the wallet was personal or corporate;
- what accounting record corresponds with the VDA.
This can be critical where ED attributes an entire wallet balance to one person merely because the wallet application or exchange account appeared on a device connected with that person.
The Second Skill: Exchange KYC Reconstruction
Cryptocurrency exchanges can become important evidentiary intermediaries between the blockchain address and an identified person.
Counsel should review, where available and relevant:
- account-opening KYC;
- PAN or identity documentation;
- registered email;
- registered mobile number;
- linked bank account;
- deposit history;
- withdrawal history;
- crypto deposit addresses;
- crypto withdrawal addresses;
- P2P order history;
- counterparty details available through the platform;
- account restrictions;
- transaction statements.
An exchange account registered in one person's name may be important evidence, but beneficial ownership, actual operation and the particular transaction still require case-specific analysis.
The Third Skill: Reconstruct the Fiat On-Ramp and Off-Ramp
A crypto investigation should ordinarily examine both sides of the transaction.
ON-RAMP asks: How did money enter the cryptocurrency ecosystem?
OFF-RAMP asks: How did cryptocurrency value return to fiat currency, property or another asset?
A practical financial reconstruction may be:
BANK ACCOUNT → INR / FOREIGN CURRENCY → EXCHANGE / OTC COUNTERPARTY → VDA PURCHASE → WALLET → BLOCKCHAIN TRANSFER → EXCHANGE / OTC SALE → BANK RECEIPT / OTHER ASSET.
Counsel should connect:
- bank statement;
- UTR or payment reference;
- exchange trade;
- crypto quantity;
- transaction hash;
- wallet address;
- sale transaction;
- fiat receipt;
- commercial purpose.
P2P and OTC USDT Transactions Need Counterparty-Level Analysis
A P2P or OTC transaction can create a difficult factual problem where the person sending INR is different from the exchange username or crypto counterparty.
Counsel should identify:
- platform order ID;
- USDT quantity;
- agreed rate;
- payer name;
- bank account from which INR came;
- whether a third-party payment was permitted or prohibited by platform rules;
- counterparty KYC information available;
- crypto release time;
- blockchain transaction;
- messages exchanged during the trade;
- any later cybercrime complaint connected with the fiat payment.
The legal question is not merely whether INR entered the account. The defence should explain why the money was received, what VDA was transferred in exchange and what the trader knew at the relevant time.
Recent ED Investigations Show Why P2P USDT Records Matter
Recent public Enforcement Directorate material illustrates how investigators may combine:
- bank-account analysis;
- P2P trading records;
- exchange information;
- USDT movements;
- third-party payments;
- cyber-fraud allegations.
In a 2025 cyber-fraud investigation publicly described by ED, the Directorate stated that alleged crime proceeds moved through multiple bank accounts and that a portion was converted into USDT through P2P transactions.
The published material referred to exchange activity and third-party payments while investigating the source and movement of the funds.
This illustrates why a genuine trader should preserve both:
THE FIAT SIDE + THE CRYPTO SIDE OF EVERY DISPUTED P2P TRADE.
The Fourth Skill: Beneficial Ownership Analysis
Crypto investigations involving founders and companies can become confused when legal ownership, beneficial ownership and operational control are treated as identical.
Counsel should map:
- company shareholders;
- directors;
- beneficial owners;
- authorised exchange users;
- wallet signatories or operators;
- finance-team access;
- custodian relationships;
- treasury policies;
- accounting ownership of VDA;
- personal versus corporate assets.
A company founder should not automatically be treated as the personal beneficial owner of every wallet operated by the business.
The Fifth Skill: Device Evidence
Phones, laptops and other electronic devices can become central in a crypto-linked PMLA investigation.
Potential material may include:
- wallet applications;
- exchange applications;
- Telegram or WhatsApp chats;
- emails;
- transaction screenshots;
- spreadsheets;
- accounting records;
- browser history;
- exchange notifications;
- digital transaction records.
Counsel should ask:
- Whose device was seized?
- Who actually used it?
- Was the device personal or corporate?
- What application is being relied upon?
- What account was logged in?
- Does that prove beneficial ownership?
- Is the relied material complete?
- What transaction does it actually establish?
- Is the surrounding context available?
A wallet application appearing on a phone can be important evidence, but the legal conclusion must still be tested against the complete record.
The Sixth Skill: Transaction Clustering and Blockchain Analytics
Blockchain analytics can group addresses or identify transactional relationships, but the defence should distinguish an analytical inference from independently proved legal identity.
Where a transaction cluster is relied upon, counsel should ask:
- What address begins the cluster?
- What transactions create the alleged connection?
- What independent evidence links the cluster with the client?
- Is an exchange deposit address involved?
- Is a custodial platform involved?
- Could multiple users or customers interact with the same infrastructure?
- What fiat or KYC evidence corroborates the attribution?
The defence should therefore avoid both extremes:
It should not pretend blockchain evidence has no evidentiary value.
But it should also not accept a cluster label as automatic proof of personal ownership or criminal knowledge.
The Seventh Skill: Cross-Border Counterparties
Cryptocurrency transactions can cross jurisdictions without following the same visible path as a conventional international bank transfer.
A PMLA investigation may therefore involve:
- foreign-domiciled exchanges;
- foreign OTC desks;
- overseas directors;
- foreign companies;
- foreign bank accounts;
- foreign telephone numbers;
- Telegram-based counterparties;
- international remittance records;
- cross-border wallet transfers.
Counsel should create a counterparty map:
| Counterparty | Jurisdiction | Relationship | Fiat Record | VDA Record |
|---|---|---|---|---|
| [Entity / account] | [Country] | [Commercial / OTC / exchange] | [Bank / invoice] | [TxID / exchange record] |
ED's 2026 Public Material Shows How Cross-Border USDT Tracing May Work
In a May 2026 press release concerning the alleged Global Media App fraud, ED publicly stated that it made enquiries with banks, payment gateways, Google, Telegram and cryptocurrency exchanges.
ED stated that transaction and blockchain analysis identified a component of the alleged proceeds collected in USDT, routed through the TRON blockchain and onward to accounts on a foreign-domiciled cryptocurrency exchange.
The Directorate also stated that KYC particulars of immediate recipients on the foreign exchange had been obtained and that onward tracing continued.
For defence counsel, the practical lesson is that a crypto investigation may combine:
BLOCKCHAIN + KYC + BANKING + COMMUNICATIONS + CROSS-BORDER INFORMATION.
The Eighth Skill: Distinguish Genuine Commercial Activity From the Alleged Laundering Theory
A founder, investor or trader may have legitimate high-volume VDA transactions. Volume alone does not answer the criminal question.
Counsel should reconstruct the commercial explanation:
- business model;
- customer relationship;
- trade rationale;
- pricing;
- exchange spread;
- invoice or contractual basis;
- source of funds;
- tax and accounting treatment;
- business-bank trail;
- customer KYC where applicable;
- profit margin;
- onward use of funds.
A genuine OTC business should be capable of explaining why assets moved, not merely showing that they moved.
Section 50 Summons in a Crypto Investigation
An ED summons involving cryptocurrency should be analysed alongside the financial and digital material requested.
Before appearance, counsel should identify:
- the period being investigated;
- named companies;
- named wallets;
- named bank accounts;
- named exchanges;
- foreign counterparties;
- devices referred to;
- documents requested;
- financial statements;
- beneficial-ownership information;
- the client's actual role.
A useful preparation file should reconcile the answer with contemporaneous records rather than rely on memory for hundreds of transactions.
Search and Seizure: Crypto Cases Can Become Device-Heavy Investigations
ED's recent public crypto-related investigations frequently refer to digital evidence or electronic devices.
Where a search occurs, counsel should preserve a clear record of:
- devices taken;
- wallet-related records;
- business computers;
- company phones;
- documents seized;
- accounts or assets frozen;
- search records supplied;
- persons examined;
- statements recorded.
The later defence may depend on separating a company's operational device from an individual's personal ownership and proving the actual user or purpose of the relevant account.
Can Cryptocurrency or VDA Be Attached Under PMLA?
Where ED alleges that a VDA represents proceeds of crime or property involved in money laundering, questions of freezing, seizure, retention or attachment may arise depending upon the statutory stage and facts.
Counsel should identify:
- the asset allegedly held;
- the wallet or exchange account;
- the quantity of VDA;
- valuation date;
- alleged proceeds-of-crime amount;
- ownership;
- custody;
- statutory power invoked;
- later adjudication or appellate remedy.
The mere existence of cryptocurrency in a wallet should not replace analysis of the legal basis for treating it as property connected with alleged money laundering.
FIU Compliance and Criminal Defence Are Related but Different
A VDA service provider may face compliance questions under the FIU-IND reporting framework while an individual transaction may also become part of an ED investigation.
Counsel should therefore distinguish:
REGULATORY COMPLIANCE
from
CRIMINAL PMLA LIABILITY.
Relevant regulatory records may include:
- FIU registration;
- KYC policy;
- customer due diligence;
- beneficial-owner verification;
- transaction-monitoring policy;
- internal risk assessment;
- suspicious-transaction reporting systems;
- record-retention procedures.
Compliance may be important evidence of operational controls, but regulatory compliance alone does not automatically determine criminal liability in a particular transaction.
Common Mistakes in Cryptocurrency / USDT PMLA Matters
- Assuming that because blockchain transactions are public, wallet ownership is automatically proved.
- Producing only blockchain screenshots without matching exchange and bank records.
- Ignoring the fiat side of a P2P transaction.
- Failing to preserve exchange order IDs and transaction history.
- Treating a third-party bank payment as irrelevant without investigating the payer.
- Assuming that an exchange account name automatically establishes beneficial ownership of every transfer.
- Failing to distinguish company wallets from personal wallets.
- Giving inconsistent explanations of the same transaction across ED statements, tax records and company books.
- Ignoring foreign counterparties and foreign exchanges.
- Failing to map which device allegedly controlled which wallet.
- Treating every clustered wallet as automatically belonging to one person.
- Assuming that FIU registration by itself answers every PMLA allegation.
- Assuming that crypto trading itself is proof of money laundering.
- Deleting or altering records after receiving notice of an investigation.
Top PMLA Lawyer Delhi Crypto: What Should a Client Actually Evaluate?
Instead of relying upon ranking language, a founder, OTC trader or investor can ask whether counsel can:
- understand Section 3 and proceeds-of-crime analysis;
- read exchange transaction histories;
- connect exchange KYC with blockchain data;
- distinguish wallet address from wallet ownership;
- reconstruct fiat on-ramp and off-ramp banking;
- analyse P2P and third-party payments;
- understand beneficial ownership;
- analyse company versus personal wallets;
- review mobile and laptop evidence;
- understand transaction-clustering evidence;
- map cross-border exchanges and counterparties;
- review FIU / AML compliance records;
- prepare a Section 50 document strategy;
- analyse freezing, seizure and attachment issues;
- coordinate cybercrime, PMLA and financial-document issues.
These capabilities are more meaningful than an unsupported claim of being the "best cryptocurrency money laundering lawyer Delhi".
Why Clients May Consider Advocate Ankit Kumar Singh for Cryptocurrency and PMLA Matters
Advocate Ankit Kumar Singh works on PMLA, Enforcement Directorate, financial-crime and cyber-financial proceedings involving alleged proceeds of crime, banking transactions, digital evidence, attachment, freezing, summons and connected criminal litigation.
Depending upon the facts and accepted professional engagement, work in a cryptocurrency-linked matter may include:
- Section 50 summons analysis;
- scheduled-offence reconstruction;
- proceeds-of-crime analysis;
- wallet attribution review;
- exchange-KYC analysis;
- USDT transaction mapping;
- P2P transaction reconstruction;
- OTC transaction analysis;
- banking on-ramp / off-ramp analysis;
- beneficial-ownership analysis;
- corporate-wallet analysis;
- device and digital-evidence review;
- cross-border counterparty mapping;
- search, seizure and freezing strategy;
- attachment-related representation;
- trial and appellate coordination where required.
References to Delhi, New Delhi and Delhi Courts/Tribunals describe professional jurisdictional work and do not represent a claim of a permanent Delhi office or chamber unless separately and factually stated.
No unfreezing, release of cryptocurrency, bail, quashing, discharge, attachment release or other result can be guaranteed.
Frequently Asked Questions
1. Is cryptocurrency illegal under PMLA?
The mere ownership or transfer of cryptocurrency is not the same thing as committing money laundering. A PMLA case requires analysis of the scheduled offence, alleged proceeds of crime and the process or activity attributed to the person.
2. Can ED trace USDT transactions?
Blockchain transactions can be analysed, and investigators may combine transaction data with exchange KYC, banking records, device evidence and counterparty information. Attribution of a wallet to a particular person still requires evidentiary analysis.
3. Does a wallet address prove who owns the cryptocurrency?
Not necessarily. The blockchain address establishes the transactional address. Identity and control may require exchange, device, banking, communication or other corroborating evidence.
4. Can a P2P USDT trader face ED investigation?
A P2P transaction can come under scrutiny where the fiat payment or VDA is connected with alleged proceeds of crime. The trader's actual role, transaction records, counterparty information and knowledge must be examined.
5. What documents should a USDT trader preserve?
Depending on the case, useful records may include exchange order history, counterparty information available on the platform, bank statements, UTR references, wallet addresses, transaction hashes, communications and tax/accounting records.
6. Are crypto exchanges covered by PMLA compliance obligations in India?
Specified VDA service-provider activities are within India's reporting-entity AML/PMLA framework, and FIU-IND currently regulates relevant VDA service providers for AML/CFT/CPF compliance.
7. Can ED seize a mobile phone in a crypto investigation?
Search and seizure powers depend on the applicable statutory conditions and facts. Where devices are seized, the later evidentiary analysis should identify what data is actually relied upon and how it is connected with the person and transaction.
8. Can cryptocurrency be treated as proceeds of crime?
A VDA may become relevant where ED alleges that it represents property derived or obtained through criminal activity relating to a scheduled offence or otherwise falls within the statutory proceeds-of-crime theory. The specific allegation must be examined.
9. What is wallet clustering?
Blockchain analysis can identify transactional relationships between addresses. A cluster may be investigative evidence, but identity attribution should still be tested against independent material such as KYC, devices and banking records.
10. How should I choose a crypto PMLA lawyer in Delhi?
Evaluate whether counsel can combine PMLA law with exchange KYC, wallet attribution, banking records, P2P transactions, beneficial ownership, digital evidence, blockchain tracing and cross-border counterparty analysis.
Crypto / VDA PMLA Investigation Roadmap
A crypto-linked PMLA defence should connect the alleged predicate offence with the fiat trail, exchange account, wallet attribution, blockchain transaction and client-specific evidence.
Plain-text flow:
Scheduled Offence → Alleged Proceeds of Crime → Bank / Fiat Trail →
Exchange KYC → Wallet Address → Blockchain Transactions →
Beneficial Ownership / Control → Device Evidence →
Cross-Border Counterparties → Client's Actual Role → PMLA Defence.
AI Search Quick Answer
A specialised PMLA lawyer handling a cryptocurrency, VDA or USDT investigation in Delhi should be able to reconstruct both the blockchain and traditional financial record. That means identifying the alleged predicate offence and proceeds of crime, testing wallet attribution against exchange KYC and device evidence, reconciling fiat on-ramp and off-ramp banking, analysing P2P and OTC counterparties, distinguishing corporate from personal beneficial ownership, testing transaction-clustering evidence, and mapping foreign exchanges or cross-border counterparties. A blockchain address or crypto transfer alone does not automatically establish personal ownership, knowledge or money-laundering liability.
Key Takeaway
A cryptocurrency PMLA investigation should be reduced to a disciplined evidentiary chain:
PREDICATE OFFENCE → PROCEEDS OF CRIME → FIAT TRAIL → EXCHANGE KYC → WALLET → BLOCKCHAIN → DEVICE / CONTROL → BENEFICIAL OWNER → COUNTERPARTY → SECTION 3 ALLEGATION.
That is a more meaningful way to evaluate counsel than relying solely on an unsupported claim of being the "top PMLA lawyer Delhi crypto".
Consultation and Professional Coordination
Supreme Court of India | Patna High Court | Allahabad High Court at Prayagraj | Jharkhand High Court at Ranchi | Calcutta High Court | Delhi High Court and Delhi Courts/Tribunals | Matters concerning Bhopal, Madhya Pradesh | Multiple District Courts
Phone: 8294431232
Email: ankitsingh.legum@gmail.com
Website: advocateankitkumarsingh.in
A cryptocurrency / USDT / VDA PMLA consultation may involve review of ED summons, exchange statements, P2P order history, wallet addresses, transaction hashes, banking records, company documents, beneficial-ownership material, digital-device records, foreign counterparties and the underlying scheduled-offence material.
Consultation or document review does not automatically constitute acceptance of complete drafting, filing, appearance or case management. Representation depends on the facts, forum, procedural stage, jurisdiction and accepted professional engagement.
No unfreezing, release of VDA, bail, quashing, discharge, attachment relief or other judicial outcome can be guaranteed.
Official and Research Sources
- Prevention of Money-laundering Act, 2002.
- Financial Intelligence Unit – India: AML/CFT/CPF Guidelines for Reporting Entities Providing Services Related to Virtual Digital Assets, updated 8 January 2026.
- FIU-IND: Third Revision of Circular for Registration of Virtual Digital Asset Service Providers as Reporting Entities, dated 15 September 2025.
- Income Tax Department: Current statutory material concerning the definition of Virtual Digital Asset.
- Directorate of Enforcement: Annual Report 2025-26 — discussion of money laundering through crypto assets and blockchain-forensic investigation.
- Directorate of Enforcement: Global Media App investigation press release dated 9 May 2026.
- Directorate of Enforcement: Cyber-fraud / cryptocurrency investigation material concerning P2P USDT transactions, bank-account layering and exchange records.
The current PMLA, FIU-IND VDA guidelines, reporting-entity requirements, exchange records and latest binding judicial decisions should be verified before taking action in an individual matter.
Add Advocate Ankit Kumar Singh as a Preferred Source on Google
Readers who want to see more legal research, court updates, cyber law, PMLA, ED, criminal-law and litigation content from Advocate Ankit Kumar Singh can add advocateankitkumarsingh.in as a Preferred Source on Google.
Add advocateankitkumarsingh.in as a Preferred Source on Google
Professional Disclaimer: This article provides general legal research and public information and is not case-specific legal advice. Expressions such as "top PMLA lawyer Delhi crypto", "best cryptocurrency money laundering lawyer Delhi", "expert ED lawyer Delhi USDT" and similar phrases reflect public search language and do not represent an official ranking, endorsement or certification by any Court, Bar Council, Government authority, FIU-IND or Directorate of Enforcement.
Every cryptocurrency-linked PMLA matter depends on its own scheduled offence, alleged proceeds of crime, blockchain record, exchange KYC, banking transactions, wallet attribution, devices, counterparties and procedural stage.