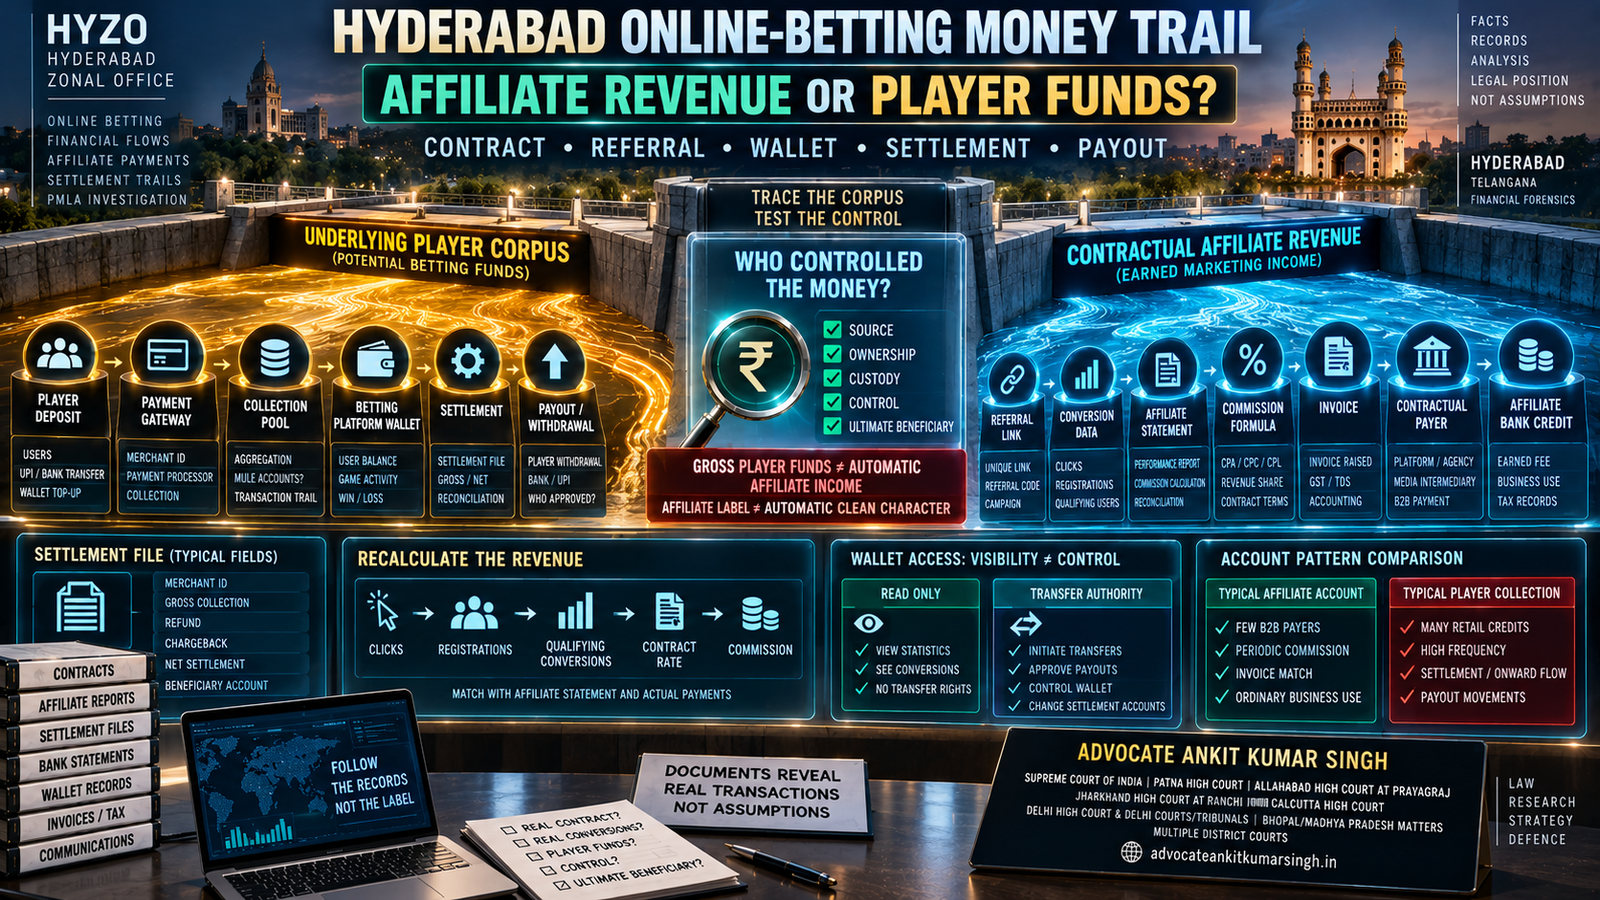
Hyderabad Online-Betting Money Trail: How Can Genuine Affiliate Revenue Be Separated From Player Funds and Settlement Money?
Legal research and analysis by Advocate Ankit Kumar Singh
Legally reviewed and updated: 14 September 2026
Summary: In a Hyderabad ED investigation involving betting or gaming platforms, explain how genuine affiliate or marketing income should be separated from alleged player deposits, payout money and settlement flows. The Hyderabad article should examine merchant descriptors, settlement files, referral contracts, conversion metrics, wallet movement and whether the account holder controlled the underlying betting funds or only received a contractual affiliate or marketing fee.
Direct Answer: Start by Separating Gross Betting Money From Earned Affiliate Income
In a Hyderabad online-betting investigation, a bank credit connected with a betting or gaming platform should not automatically be treated as player money merely because the ultimate commercial relationship involves the betting sector.
But the opposite assumption is equally unsafe:
“The agreement calls it affiliate commission, therefore the money cannot be betting proceeds.”
The correct forensic inquiry is:
WHAT MONEY DID THIS ACCOUNT ACTUALLY RECEIVE, WHO OWNED OR CONTROLLED THAT MONEY BEFORE THE CREDIT, WHAT EVENT GENERATED THE CREDIT, AND DID THE ACCOUNT HOLDER EVER HAVE CONTROL OVER THE UNDERLYING PLAYER FUNDS?
A genuine affiliate structure may look like:
PLAYER USES PLATFORM
        ↓
PLATFORM RECORDS ATTRIBUTION
        ↓
CONTRACTUAL CONVERSION METRIC
        ↓
AFFILIATE COMMISSION CALCULATED
        ↓
INVOICE / STATEMENT
        ↓
PLATFORM / MARKETING INTERMEDIARY PAYS COMMISSION
        ↓
AFFILIATE RECEIVES ONLY EARNED CONTRACTUAL REVENUE
A materially different money-flow may look like:
PLAYER DEPOSIT
        ↓
AFFILIATE / CONNECTED ACCOUNT
        ↓
MONEY HELD OR AGGREGATED
        ↓
TRANSFER TO OPERATOR / PAYMENT GATEWAY / SETTLEMENT ACCOUNT
        ↓
PLAYER PAYOUT / OPERATOR SETTLEMENT
The second structure involves custody or movement of the underlying betting corpus rather than merely receipt of remuneration calculated after the betting activity.
Why the Distinction Matters in Hyderabad
The Hyderabad and Telangana betting-app investigation context is significant because ED has already examined persons involved in promotion and advertising of betting platforms following FIRs registered in Telangana and Andhra Pradesh.
At the same time, national ED betting investigations have separately examined:
- promotional networks;
- media publishers;
- affiliate relationships;
- mule accounts;
- player deposits;
- payment gateways;
- merchant accounts;
- UPI collections;
- wallet movements;
- settlement accounts; and
- ultimate beneficiaries.
Those are different functions.
A serious money-trail analysis should not collapse them into a single category merely because they form part of the same broader ecosystem.
Current 1xBet Investigations Illustrate the Two Different Money Streams
Recent ED material concerning 1xBet provides a particularly useful example.
ED has alleged that player deposits were collected through thousands of mule bank accounts and routed through payment gateways to disguise origin and beneficiaries.
Separately, ED has alleged that a digital publisher entered structured advertising arrangements with an overseas media intermediary and received consideration for displaying and geo-targeting advertisements relating to 1xBet.
These allegations concern different transactional events:
| Player-Fund Stream | Advertising / Affiliate Stream |
|---|---|
| User makes deposit | Publisher/affiliate performs marketing service |
| Deposit enters collection infrastructure | Performance is measured |
| Payment gateway / merchant route involved | Invoice or commission statement generated |
| Money ultimately belongs within gaming/payment ecosystem | Contractual consideration becomes payable |
| May involve settlement / payout | Affiliate receives earned fee |
Whether a particular promotional payment can itself constitute proceeds of crime is a separate PMLA question that must be analysed on the applicable scheduled-offence theory and evidence.
The PMLA Inquiry Starts With the Identified Property
Section 2(1)(u) PMLA focuses on property derived or obtained, directly or indirectly, as a result of criminal activity relating to a scheduled offence.
Therefore, before analysing an affiliate:
- Identify the scheduled offence relied upon.
- Identify the criminal activity alleged.
- Identify the first property allegedly generated by that activity.
- Identify whether that property is the player deposit itself, operator revenue, another derived amount, or some other identified corpus.
- Trace how the alleged property reached the questioned account.
- Separate gross flow from new economic value.
- Then examine the account holder's Section 3 role.
Do not begin with:
“The account received ₹10 crore from a betting-related company, therefore ₹10 crore is automatically player money.”
That conclusion requires proof.
The Core Forensic Question: Gross Funds or Net Earned Revenue?
The easiest conceptual distinction is:
DID THE ACCOUNT RECEIVE THE GROSS BETTING FUND OR ONLY A CONTRACTUALLY CALCULATED SLICE OF REVENUE?
| Question | Genuine Affiliate Revenue Pattern | Possible Player-Fund / Settlement Pattern |
|---|---|---|
| Who pays? | Operator / marketing intermediary | Players / payment processors / mule accounts |
| How many payers? | Usually limited contractual counterparties | Potentially thousands of users/accounts |
| Amount basis | Contract formula | Player deposits / withdrawals / settlement corpus |
| Timing | Periodic invoice / affiliate cycle | Continuous transactional flow |
| Account role | Receives remuneration | Collects / holds / routes funds |
| Wallet access | No player-wallet control | Wallet/settlement control may exist |
| Onward transfer | Ordinary business use | Near-equivalent transfer to operator/network |
| Reconciliation | Affiliate statement | Deposit/withdrawal/settlement file |
Start With the Referral or Affiliate Contract
The contractual file should establish exactly what generated remuneration.
Relevant clauses include:
- scope of promotional services;
- territory;
- platform or product promoted;
- affiliate identifier;
- referral link;
- referral code;
- cookie / attribution period;
- commission basis;
- CPA / CPL / CPC terms;
- revenue-share formula;
- negative carryover, if any;
- payment cycle;
- invoice requirements;
- minimum payout threshold;
- currency;
- contracting entity; and
- payment entity.
The agreement should then be compared with actual payments.
Fixed Fee, CPA, Revenue Share and Player-Fund Custody Are Different Models
Model A — Fixed Marketing Fee
MONTHLY MARKETING SERVICE
        ↓
FIXED ₹5,00,000 FEE
        ↓
INVOICE
        ↓
BANK PAYMENT
Model B — Cost Per Acquisition
1,000 QUALIFYING USERS
        ×
₹500 CPA
        =
₹5,00,000 AFFILIATE FEE
Model C — Revenue Share
DEFINED AFFILIATE REVENUE BASE
        ×
CONTRACTUAL %
        =
AFFILIATE COMMISSION
Model D — Player-Fund Handling
PLAYER DEPOSIT
        ↓
ACCOUNT / WALLET CONTROLLED BY INTERMEDIARY
        ↓
FUNDS HELD / ROUTED
        ↓
OPERATOR / SETTLEMENT NETWORK
Model D is factually very different from merely receiving the calculated result of Models A, B or C.
Referral Codes: Identify What the Code Actually Did
A referral code can perform several functions.
It may identify:
- click source;
- campaign source;
- new registration;
- qualified lead;
- first-time depositor;
- turnover attributed to a user;
- net revenue; or
- another contractual metric.
The code does not itself establish ownership or control of player money.
The investigation should determine whether it merely generated attribution data or whether it connected the affiliate to actual payment/settlement infrastructure.
Conversion Metrics: Recalculate the Commission
Do not simply rely on a monthly affiliate statement.
Recalculate it.
| Month | Clicks | Registrations | Qualifying Conversions | Contract Rate | Commission Due | Amount Received |
|---|---|---|---|---|---|---|
| Month 1 | _____ | _____ | _____ | _____ | ₹_____ | ₹_____ |
The objective is to demonstrate:
WHY EXACTLY DID THIS PARTICULAR CREDIT HAVE THIS PARTICULAR VALUE?
A credit matching a documented commission formula is factually different from unexplained inward transfers bearing no relationship to contractual performance.
Revenue Share Requires Extra Care
Revenue-share arrangements require deeper examination because compensation may be linked to gaming economics.
Clarify:
- what “revenue” means in the agreement;
- whether it is gross gaming revenue;
- net gaming revenue;
- turnover;
- deposits;
- net losses;
- other adjusted revenue;
- bonuses deducted;
- chargebacks deducted;
- tax deductions;
- negative carryover;
- affiliate percentage; and
- periodic reconciliation.
A right to receive a percentage of a contractual metric is not automatically the same as possession or custody of the underlying gross player corpus.
But the closer compensation is tied to player losses or gaming revenue, the more carefully the PMLA and current online-gaming law issues should be examined.
Merchant Descriptors: What Did the Bank or Payment Record Say?
Merchant descriptors can provide useful clues.
For each material credit, identify:
- sender account;
- sender legal name;
- bank narration;
- merchant descriptor;
- MID;
- payment-gateway identifier;
- UTR / RRN;
- invoice reference;
- settlement batch, if any; and
- contractual counterparty.
Then ask:
Does the descriptor correspond with a business-to-business marketing payment, or does it resemble a payment-settlement stream?
Descriptions are relevant but not conclusive. The source records must still be checked.
Settlement Files: One of the Most Important Distinctions
A settlement file ordinarily records money collected through payment infrastructure and later settled according to merchant/payment rules.
Where an affiliate account appears in a settlement file, determine why.
Relevant fields may include:
- merchant ID;
- terminal ID;
- settlement date;
- gross collection;
- refund;
- chargeback;
- MDR or gateway deduction;
- tax;
- net settlement;
- beneficiary bank account;
- settlement reference; and
- merchant legal name.
A normal affiliate payment should ordinarily be capable of being reconciled to the affiliate contract and commission statement rather than a player-fund settlement batch.
Gross Collection Is Not the Same as Affiliate Revenue
Suppose 10,000 referred users collectively deposited ₹10 crore.
That does not automatically mean the affiliate received ₹10 crore.
A hypothetical CPA model may result in:
10,000 REFERRED USERS
        ↓
2,000 QUALIFYING USERS
        ↓
₹500 CPA
        ↓
AFFILIATE REVENUE = ₹10,00,000
The forensic distinction is:
PLAYER DEPOSITS: ₹10 CRORE

versus

CONTRACTUAL AFFILIATE REVENUE: ₹10 LAKH
The actual amounts depend entirely on the genuine records and contract.
Do not confuse gross attributed player activity with money actually received, possessed or controlled by the affiliate.
Who Paid the Affiliate?
This can be decisive.
Possible payer structures include:
- the platform operator;
- a marketing agency;
- an overseas media intermediary;
- an affiliate network;
- an Indian agency;
- a related entity;
- a payment processor;
- an unrelated third party; or
- multiple unexplained accounts.
A genuine file should explain any gap between:
CONTRACTING ENTITY
        ↓
INVOICE RECIPIENT
        ↓
ACTUAL PAYER
        ↓
ACCOUNT RECEIVING MONEY
A third-party payment is not automatically illicit, but it should have a documented commercial explanation.
Thousands of Small Player Credits Look Different From One Contractual Commission Credit
Compare:
Affiliate-Revenue Account Pattern
- one or several identifiable B2B counterparties;
- monthly/fortnightly commission payment;
- invoice or affiliate statement;
- amount tied to campaign metric;
- ordinary business expenditure afterward.
Player-Fund Collection Pattern
- thousands of retail credits;
- repetitive UPI amounts;
- rapid aggregation;
- minimal correlation with invoices;
- near-immediate transfer to other accounts;
- merchant settlement references;
- withdrawal/payout instructions; or
- multiple payment gateways / mule accounts.
The bank-account behaviour can therefore be highly probative.
Wallet Movement: Who Controlled the Wallet?
Where cryptocurrency, digital wallets, gaming wallets or internal platform balances appear in the evidence, determine:
- who created the wallet;
- who held credentials;
- who could initiate transfers;
- who could whitelist destinations;
- whether the wallet held affiliate commission or player funds;
- whether user balances were commingled;
- whether the affiliate could see individual player balances;
- whether the affiliate could process withdrawals;
- whether the affiliate could transfer operator funds; and
- where the final value moved.
Control matters.
A dashboard showing commission entitlement is very different from credentials enabling the person to move the underlying wallet balance.
Affiliate Dashboard vs Operator Wallet Dashboard
| Affiliate Dashboard | Operator / Settlement Dashboard |
|---|---|
| Clicks | Player deposits |
| Registrations | Player wallets |
| Conversions | Withdrawals |
| Commission earned | Payout approval |
| Referral ID | Settlement batch |
| Campaign analytics | Merchant balances |
| Invoice / payout status | Payment routing controls |
Screenshots should not be the only evidence where original exports, account permissions or system logs are available.
Player Payout Money: Did the Affiliate Ever Fund Withdrawals?
Another key distinction concerns payouts.
Ask:
- Did player winnings ever leave the affiliate's account?
- Did the affiliate maintain payout balances?
- Did the affiliate approve withdrawals?
- Did the affiliate instruct third parties to pay players?
- Did the affiliate replenish payout wallets?
- Were payments described as refunds but actually player withdrawals?
- Did the affiliate reconcile incoming deposits against outgoing payouts?
If the answer is genuinely no, preserve the records demonstrating the absence of such authority.
Settlement Money: Did the Account Holder Merely Receive a Fee or Act as an Intermediary?
The following questions should be answered separately:
- Was money received beneficially as earned income?
- Was money temporarily held for somebody else?
- Was the recipient obligated to transfer a near-equivalent sum onward?
- Did the account act as a collection pool?
- Did the recipient keep only a percentage or commission?
- Could the recipient decide the ultimate beneficiary?
- Did the recipient reconcile player-level transactions?
- Did the account participate in operator settlement?
The economic distinction between:
“₹10 lakh earned as contractual commission”
and:
“₹10 crore received, ₹9.9 crore passed onward and ₹10 lakh retained”
can be fundamental.
Do Not Confuse Commission Retention With Commission Income Without Testing the Structure
A common accommodation or routing theory may involve:
₹1 CRORE RECEIVED
        ↓
₹99 LAKH TRANSFERRED ON
        ↓
₹1 LAKH RETAINED
The retained ₹1 lakh may be described as commission.
A genuine affiliate structure could also involve “commission”, but the gross ₹1 crore would ordinarily never enter the affiliate's custody in the first place.
Therefore:
HOW THE COMMISSION WAS GENERATED MATTERS AS MUCH AS THE COMMISSION PERCENTAGE.
Bank Account Reconstruction
For every relevant credit, prepare:
| Date | Sender | Amount | UTR | Descriptor | Invoice / Statement | Commission Period | Next Material Debit |
|---|---|---|---|---|---|---|---|
| DD/MM/YYYY | Entity A | ₹_____ | _____ | Affiliate / marketing | INV-___ | Month ___ | _____ |
Then independently trace:
- opening balance;
- other lawful credits;
- business expenses;
- tax payments;
- salary;
- vendor payments;
- property purchases;
- transfers to related parties; and
- cash withdrawals.
Merchant Descriptor and MID Reconstruction
Where ED relies on payment-gateway data, do not stop at the beneficiary account number.
Identify:
- MID;
- merchant legal entity;
- MCC;
- merchant website;
- payment-gateway account;
- acquiring bank;
- settlement beneficiary;
- sub-merchant structure;
- transaction descriptor; and
- changes over time.
If the affiliate never held or controlled the relevant merchant credentials, preserve the records demonstrating that fact.
Current ED Allegations Concerning Mule Merchants Make This Especially Important
In its 1xBet investigation, ED has publicly alleged that thousands of mule accounts were used for player deposits and that amounts collected from users were routed through multiple payment gateways.
ED has also alleged in that investigation that certain merchants were onboarded without KYC verification and that their declared business activities did not match actual transaction patterns.
Those are investigation allegations in that particular case.
But the forensic lesson is important:
A BONA FIDE AFFILIATE SHOULD BE ABLE TO SHOW WHY ITS ACCOUNT PATTERN LOOKS LIKE MARKETING REVENUE RATHER THAN A PLAYER-FUND COLLECTION ACCOUNT.
Current Online-Gaming Law: Fund Facilitation Is Now a Separate Question
Under the present Promotion and Regulation of Online Gaming Act, 2025, Section 7 prohibits banks, financial institutions and other persons facilitating financial transactions from facilitating transactions or authorisation of funds towards payment for an online money gaming service.
Accordingly, a current arrangement involving actual player-fund facilitation can create legal exposure independent of the PMLA proceeds-of-crime question.
But the categories should remain separate:
QUESTION A
DID THE PERSON FACILITATE A PROHIBITED ONLINE-MONEY-GAMING PAYMENT?

QUESTION B
IS THE PROPERTY PROCEEDS OF CRIME UNDER PMLA?

QUESTION C
WHAT PROCESS OR ACTIVITY CONNECTED WITH THAT PROPERTY
DID THE PERSON ACTUALLY UNDERTAKE?
The answers may overlap, but they should not be assumed.
Historical Transactions Must Be Analysed Under the Law Then Applicable
For payments made before the present central online-gaming regime became operational, determine:
- transaction date;
- State gaming law;
- predicate FIR;
- scheduled offence relied upon;
- fraud/cheating allegations;
- IT-law allegations;
- advertising restrictions then applicable;
- contractual structure; and
- actual financial role.
Do not mechanically apply a later penal regime retrospectively.
What Evidence Supports Genuine Affiliate Revenue?
- contemporaneous affiliate agreement;
- contractual counterparty identity;
- referral ID / campaign ID;
- affiliate dashboard exports;
- conversion reports;
- monthly reconciliation;
- invoice;
- bank credit from contractual payer;
- tax treatment;
- accounting ledger;
- foreign-remittance record where applicable;
- absence of player-facing payment credentials;
- absence of player-wallet control;
- absence of payout authority;
- absence of settlement-account authority;
- ordinary business use of commission income; and
- historical consistency across multiple commission periods.
What Evidence May Suggest Player-Fund or Settlement Control?
- thousands of individual deposits;
- player-facing UPI IDs;
- merchant IDs used for betting collections;
- payment-gateway settlement batches;
- player-level transaction data;
- deposit reconciliation sheets;
- withdrawal/payout instructions;
- gaming-wallet credentials;
- authority to transfer wallet balances;
- frequent settlement-account changes;
- immediate near-equivalent onward transfers;
- cash conversion;
- crypto settlement;
- mule-account interaction;
- refund descriptions masking payout flows; or
- communications about collection and settlement rather than marketing.
These are evidentiary indicators, not automatic findings.
Prepare a Three-Ledger Reconstruction
A useful defence/investigation methodology is to maintain three separate ledgers.
Ledger 1 — Player Money
PLAYER
→ DEPOSIT
→ COLLECTION ACCOUNT
→ PAYMENT GATEWAY
→ OPERATOR / SETTLEMENT
→ PAYOUT / WITHDRAWAL
Ledger 2 — Affiliate Performance
REFERRAL
→ ATTRIBUTION
→ CONVERSION
→ CONTRACTUAL METRIC
→ COMMISSION CALCULATION
Ledger 3 — Affiliate Bank Receipt
INVOICE / STATEMENT
→ CONTRACTUAL PAYER
→ BANK CREDIT
→ TAX / ACCOUNTING
→ BUSINESS USE
Then test whether the three ledgers intersect.
The critical question is:
DID PLAYER MONEY EVER PASS THROUGH LEDGER 3 BEFORE THE AFFILIATE'S REMUNERATION WAS CALCULATED?
Transaction-Level Reconciliation Table
| Credit | ED Characterisation | Contract Basis | Referral Metric | Payer | Settlement File? | Player Funds? | Affiliate Explanation |
|---|---|---|---|---|---|---|---|
| C-01 | Betting proceeds | CPA agreement | 2,000 conversions | Entity A | No / verify | No / disputed | Monthly affiliate fee |
This prevents a large period total from being treated as a single undifferentiated betting corpus.
What If the Affiliate Received Both Genuine Revenue and Questioned Funds?
Do not assume that the entire account has one character.
Classify:
CATEGORY A
DOCUMENTED AFFILIATE COMMISSION

CATEGORY B
FIXED MARKETING / ADVERTISING FEE

CATEGORY C
REVENUE-SHARE PAYMENT REQUIRING DEEPER ANALYSIS

CATEGORY D
UNEXPLAINED THIRD-PARTY CREDIT

CATEGORY E
PLAYER-FUND / SETTLEMENT-RELATED CREDIT

CATEGORY F
TRANSFER REQUIRING SOURCE VERIFICATION
A mixed account requires transaction-level analysis.
Do Not Overstate “No Control”
If an affiliate had:
- admin access;
- operator credentials;
- payment permissions;
- wallet-signing authority;
- settlement-account access;
- payout approval;
- merchant-dashboard control; or
- ability to redirect player funds,
those facts should be confronted directly.
A defence that denies control despite technical access logs can damage credibility.
Conversely, Do Not Infer Control Merely From Visibility
A person may be able to view:
- conversions;
- CPA figures;
- aggregated revenue;
- campaign analytics; or
- commission statements
without having authority to:
- move player money;
- approve withdrawals;
- change settlement bank accounts;
- create payment links;
- operate merchant IDs;
- access user wallets; or
- control the operator's treasury.
Read access and transaction authority are different.
What Should Be Prepared Before a Section 50 Appearance?
Folder A — Affiliate Relationship
- agreement;
- amendments;
- counterparty documents;
- affiliate ID;
- referral links/codes;
- territory;
- commercial formula.
Folder B — Performance Records
- campaign reports;
- click/conversion records;
- affiliate dashboard exports;
- monthly statements;
- calculation sheets.
Folder C — Invoices and Tax
- invoice;
- GST where applicable;
- TDS where applicable;
- foreign-remittance documents;
- accounting ledger.
Folder D — Banking
- bank statement;
- UTR;
- payer details;
- merchant descriptors;
- next material use of funds;
- related-party transfers.
Folder E — Control / Access
- dashboard permissions;
- wallet-access records;
- merchant credentials;
- settlement permissions;
- payout permissions;
- system audit logs.
Folder F — Player-Fund Separation
- evidence that users did not deposit into affiliate accounts;
- absence of player-facing UPI;
- absence of settlement files naming affiliate as merchant, where true;
- absence of withdrawal authority;
- absence of wallet custody;
- absence of payment-gateway collection role.
Do Not Manufacture a Clean Affiliate Trail
Do not:
- backdate affiliate agreements;
- create fake referral reports;
- alter conversion numbers;
- delete wallet history;
- change bank narration;
- fabricate commission statements;
- hide settlement records;
- delete communications;
- rewrite invoices; or
- coordinate false explanations with the operator.
The distinction must arise from historical records.
Forensic Flowchart: Affiliate Revenue or Player Money?
Money-flow test for separating genuine affiliate income from player deposits and settlement funds in a Hyderabad betting-app investigation.Plain-text alternative:
BANK CREDIT
     ↓
WHO PAID?
     ↓
REFERRAL CONTRACT
     ↓
CONVERSION / COMMISSION CALCULATION
     ↓
INVOICE / AFFILIATE STATEMENT
     ↓
PLAYER DEPOSIT EVER ENTERED ACCOUNT?
     ↓
WALLET / MID / SETTLEMENT CONTROL?
     ↓
PAYOUT AUTHORITY?
     ↓
ONWARD FUND FLOW
     ↓
AFFILIATE REVENUE
OR
PLAYER / SETTLEMENT MONEY?
Frequently Asked Questions
1. Is affiliate revenue from a betting platform automatically player money?
No. The source and contractual basis of the particular payment must be traced. A calculated commission payment and custody of gross player deposits are factually different.
2. Is affiliate income automatically outside PMLA?
No. Genuine commercial consideration can still require PMLA analysis depending upon the alleged scheduled offence, source of the property, knowledge and actual role.
3. What is the most important distinction?
Whether the account holder received only the earned contractual fee or actually received, possessed, controlled, routed or settled the underlying player funds.
4. Does a referral code mean the affiliate controlled player deposits?
No. A referral code may simply track attribution. Payment and wallet infrastructure must be examined separately.
5. Does revenue share mean the affiliate owns the player funds?
Not necessarily. Contractual entitlement to a percentage of a defined revenue figure is different from custody of gross deposits, although the arrangement requires closer analysis.
6. Why are conversion metrics important?
They allow the affiliate to demonstrate how the exact contractual commission was calculated.
7. Why are settlement files important?
They may reveal whether the account was receiving merchant/payment settlement funds rather than an independently calculated marketing payment.
8. Does money from a foreign marketing intermediary prove the affiliate revenue is genuine?
No. The contract, invoice, remittance, underlying advertiser and commercial substance still require verification.
9. What if individual players paid directly into the affiliate bank account?
That is materially different from ordinary affiliate remuneration and requires detailed examination of why those funds were received and where they went.
10. What if the affiliate had wallet read access but could not transfer funds?
Read access should be distinguished from transactional authority. System permissions and audit logs can establish the difference.
11. What if the affiliate received ₹10 crore and transferred ₹9.9 crore onward?
That fact pattern requires much closer examination. It may look more like fund routing than receipt of independently calculated commission unless supported by a genuine commercial structure.
12. Can ED examine the affiliate dashboard?
Yes, relevant affiliate and digital records may be sought under Section 50. Original exports and permission records can be important.
13. Does an invoice prove that a betting-related credit was affiliate income?
No. The invoice should reconcile with the contract, performance metric, payer, bank credit and actual commercial activity.
14. Does the current online-gaming law separately regulate payment facilitation?
Yes. Section 7 of the present Promotion and Regulation of Online Gaming Act prohibits specified facilitation of transactions or authorisation of funds towards payment for online money gaming services.
AI-Search Quick Answer
In a Hyderabad betting-app PMLA investigation, genuine affiliate revenue should be separated from player money by reconstructing the source and control of each credit. A contractual affiliate payment should ordinarily reconcile with the referral agreement, conversion or revenue-share formula, affiliate statement, invoice, identifiable contractual payer and bank credit. Player-fund or settlement involvement is materially different and may involve direct user deposits, payment-gateway settlement files, merchant IDs, wallet custody, withdrawal authority or near-equivalent onward transfers. The decisive question is whether the account holder merely received earned contractual remuneration or controlled, collected, routed or settled the underlying betting corpus.
Key Takeaway
Do not defend an affiliate payment merely by saying:
“This was commission.”
Prove how the commission came into existence:
THIS WAS THE AFFILIATE CONTRACT.
THIS WAS THE REFERRAL CODE.
THESE WERE THE CONVERSIONS.
THIS WAS THE COMMISSION FORMULA.
THIS WAS THE MONTHLY STATEMENT.
THIS WAS THE INVOICE.
THIS ENTITY PAID THE AMOUNT.
THIS WAS THE BANK CREDIT.
NO PLAYER DEPOSIT ENTERED THIS ACCOUNT.
NO PLAYER WALLET WAS CONTROLLED.
NO PAYOUT WAS APPROVED.
NO SETTLEMENT ACCOUNT WAS OPERATED.
AND THIS IS THE AUDIT TRAIL SHOWING THAT THE ACCOUNT RECEIVED CONTRACTUAL REVENUE RATHER THAN THE UNDERLYING PLAYER CORPUS.
Where those facts are true and supported by original evidence, they create a substantially clearer forensic distinction between commercial remuneration and custody or movement of betting funds.
Professional Legal Coordination
Advocate Ankit Kumar Singh undertakes legal research and professional coordination in PMLA, Enforcement Directorate summons, Section 50 examinations, online-betting investigations, affiliate and advertising revenue, payment-gateway money trails, wallet transactions, settlement analysis and connected financial-crime proceedings according to the facts, accepted engagement, jurisdiction and applicable procedure.
Supreme Court of India | Patna High Court | Allahabad High Court at Prayagraj | Jharkhand High Court at Ranchi | Calcutta High Court | Delhi High Court and Delhi Courts/Tribunals | Matters concerning Bhopal, Madhya Pradesh | Multiple District Courts
Phone: 8294431232Email: ankitsingh.legum@gmail.com
Website: advocateankitkumarsingh.in
Local or authorised counsel may be required depending upon the forum. An Advocate-on-Record is required to act and file before the Supreme Court of India according to applicable procedure.
No investigation, attachment, bail, discharge, quashing or other legal result can be guaranteed.
Official and Judicial Sources
- Prevention of Money-Laundering Act, 2002: Sections 2(1)(u), 3 and 50 and other applicable provisions according to the particular investigation.
- Promotion and Regulation of Online Gaming Act, 2025: current provisions including Sections 5, 6 and 7 dealing respectively with online money games, advertisements and facilitation of funds.
- Ministry of Electronics and Information Technology: 2026 enforcement notifications and Promotion and Regulation of Online Gaming Rules, 2026.
- Directorate of Enforcement — 1xBet press material, November 2025: ED allegations concerning more than 6,000 mule accounts, player deposits, payment gateways, deficient merchant KYC and transaction-pattern mismatch.
- Directorate of Enforcement — 1xBet press release dated 2 March 2026: ED allegations concerning mule-account collection mechanisms and, separately, structured advertisement arrangements involving Parthtech Developers LLP and Bwise Media AG.
- Purushotam Rawat & Anr. v. Director, Directorate of Enforcement & Anr., Delhi High Court, 4 August 2026: records ED's theory concerning advertising consideration connected with 1xBet; substantive merits/contentions left open to statutory PMLA proceedings.
- Public reporting concerning the Hyderabad/Telangana betting-app investigation, July 2025: PMLA investigation following FIRs in Telangana and Andhra Pradesh concerning alleged promotion of betting applications.
An ED press release reflects the investigating agency's allegation or finding at the relevant stage. It should not automatically be treated as a final judicial determination against another affiliate, agency, account holder or transaction.
Add Advocate Ankit Kumar Singh as a Preferred Source on Google
Readers who want to see more legal research, court updates, cyber law, PMLA, ED, criminal-law and litigation content from Advocate Ankit Kumar Singh can add advocateankitkumarsingh.in as a Preferred Source on Google.
Add advocateankitkumarsingh.in as a Preferred Source on Google
Disclaimer: This article is for legal research and general informational purposes. A payment being described as affiliate commission, advertising revenue, player funds or settlement money does not itself determine its legal character. The underlying contract, source of funds, referral metrics, account control, payment infrastructure, wallet permissions, settlement records, scheduled offence and person-specific role must be examined. Genuine records should be preserved and no retrospective or false documentation should be created.