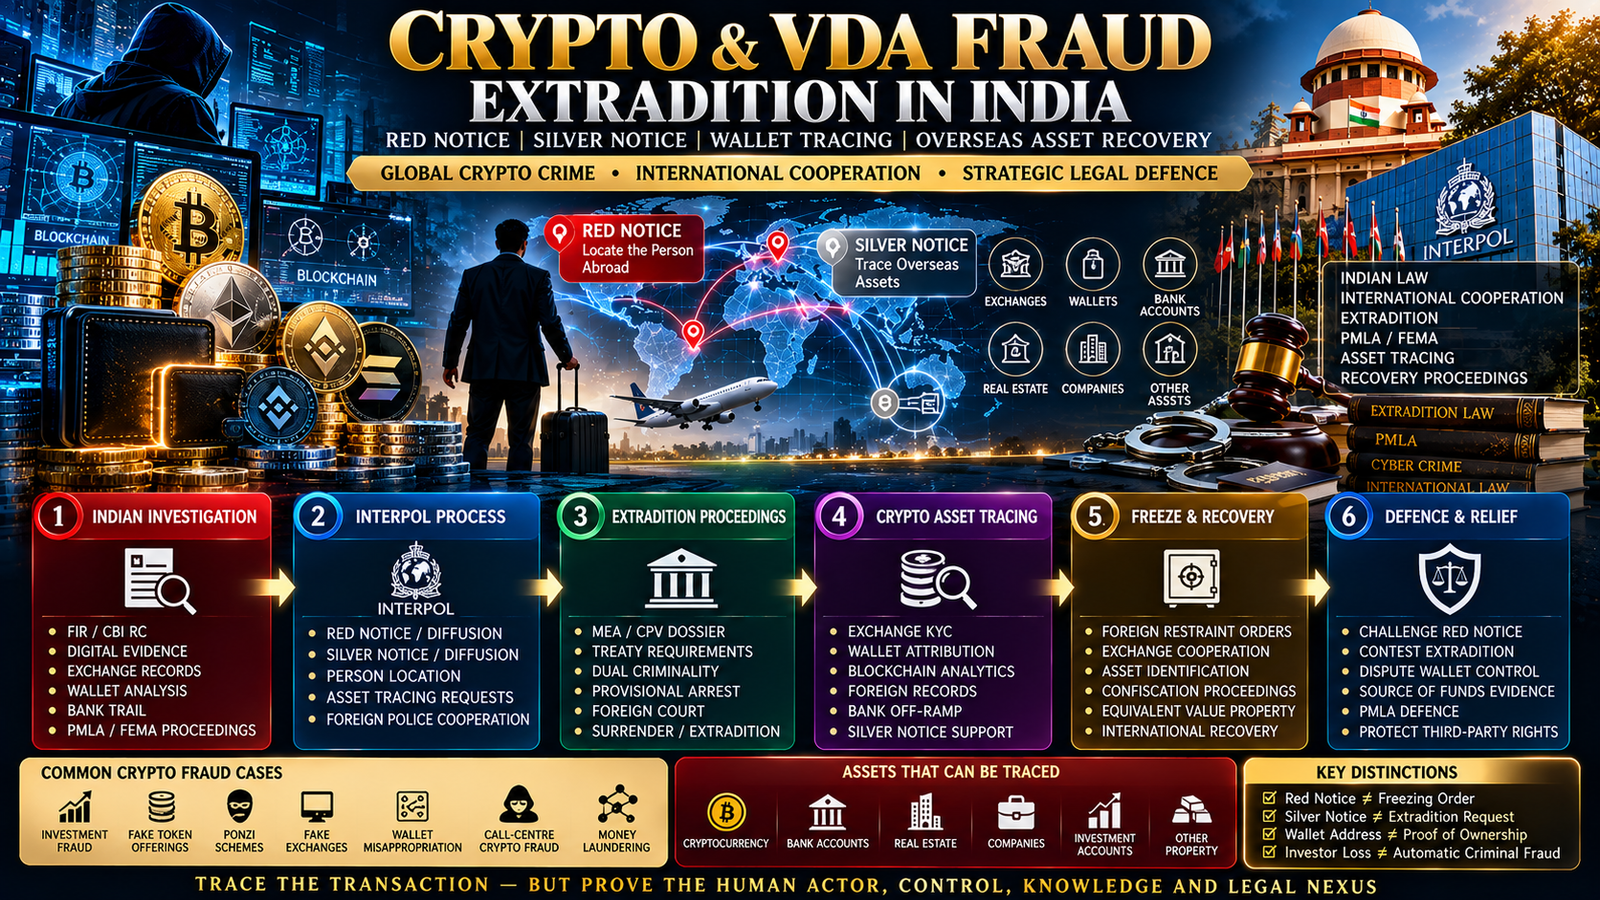
Best Extradition Lawyer in India for Crypto and VDA Fraud: Red Notice, Silver Notice, Wallet Tracing and Overseas Asset Recovery
SUMMARY: Build a commercial-intent article for cryptocurrency founders, traders and accused persons abroad where the investigation includes wallets, exchanges, cross-border transfers or alleged investor fraud. The article should integrate person-location requests with Silver Notice-style asset tracing, exchange KYC, wallet attribution, foreign records and domestic criminal proceedings. Target 'best extradition lawyer India crypto', 'top INTERPOL lawyer India cryptocurrency', 'specialized VDA extradition lawyer India' and 'crypto asset recovery lawyer India'.
Legal and procedural update: Reviewed on 24 September 2026. Indian VDA service providers falling within the notified framework are subject to PMLA-related AML/CFT obligations administered by FIU-IND. Separately, INTERPOL's Silver Notice/Silver Diffusion pilot can assist participating countries in tracing criminal assets internationally, including cryptocurrency, while Red Notice and extradition processes remain person-focused and legally distinct.
 Advocate Ankit Kumar Singh
Direct Answer: Can an Indian Crypto or VDA Fraud Case Lead to Red Notice, Extradition and International Asset Tracing?
Potentially yes, but the person-tracing and asset-tracing processes must be analysed separately.
An Indian crypto, VDA or investor-fraud investigation involving an accused person abroad may develop through two parallel international tracks.
Track One — The Person
INDIAN FIR / CBI CASE
↓
INVESTIGATION
↓
SUMMONS / WARRANT / NBW
↓
RED NOTICE / RED DIFFUSION WHERE APPLICABLE
↓
FOREIGN LOCATION
↓
PROVISIONAL ARREST WHERE LEGALLY AVAILABLE
↓
FORMAL EXTRADITION
↓
FOREIGN COURT / SURRENDER
Track Two — The Crypto or Other Assets
WALLET / EXCHANGE / BANK TRAIL
↓
ASSET ATTRIBUTION
↓
FOREIGN EXCHANGE OR WALLET INFORMATION
↓
SILVER NOTICE / SILVER DIFFUSION WHERE APPLICABLE
↓
ASSET IDENTIFICATION
↓
FORMAL FOREIGN COOPERATION
↓
FREEZE / RESTRAINT
↓
CONFISCATION / RECOVERY
The existence of one track does not automatically establish the other.
A Red Notice is not a freezing order.
A Silver Notice is not an extradition request.
A blockchain transaction is not, by itself, proof of who controlled the wallet.
What Is a Crypto or VDA Extradition Case?
A crypto or Virtual Digital Asset extradition case usually arises when Indian investigators allege that a person located abroad participated in conduct such as:
- cryptocurrency investment fraud;
- false token or coin offerings;
- misappropriation of investor funds;
- fraudulent exchange activity;
- unauthorised wallet transfers;
- misrepresentation concerning returns;
- fake trading platforms;
- Ponzi-style VDA schemes;
- crypto conversion of alleged proceeds of crime;
- cross-border layering;
- use of mixers or other obfuscation methods;
- money laundering;
- payment fraud;
- cybercrime;
- breach of trust;
- cheating;
- conspiracy; or
- another criminal offence involving digital assets.
The legal issue is not whether cryptocurrency was involved.
The real questions are:
- what offence is alleged;
- what role is attributed to the person;
- what evidence establishes that role;
- which wallet or exchange account is alleged to be controlled by the person;
- what domestic warrant exists;
- whether an INTERPOL process has begun;
- whether formal extradition has begun; and
- whether international asset tracing is separately underway.
Crypto Founder, Trader, Employee and Wallet Holder Are Not Automatically the Same Legal Role
VDA cases frequently involve several individuals performing different functions.
| Person | Important Legal Question |
|---|---|
| Founder | What representations, control and financial decisions are actually attributed to the founder? |
| Director | Was there operational control or only corporate designation? |
| Trader | Were transactions proprietary, client-directed or allegedly part of laundering? |
| Exchange employee | What access and decision-making authority did the employee possess? |
| Wallet holder | Who actually controlled the private key or signing mechanism? |
| Developer | Was the person merely providing technical services or participating in alleged fraud? |
| Promoter | What investor representations were personally made? |
| Beneficiary | What funds were actually received and with what knowledge? |
| Nominee / intermediary | Was ownership genuine, nominal or allegedly designed to conceal control? |
Extradition requires a case against the specific person sought.
The existence of a fraudulent platform or tainted wallet does not automatically prove the criminal liability of every person associated with the enterprise.
India's Current VDA AML Framework: Why Exchange Records Matter
Virtual Digital Asset Service Providers falling within the notified Indian framework are subject to anti-money-laundering obligations under the PMLA-related reporting regime administered by FIU-IND.
The regulated activity can include services involving:
- exchange between VDA and fiat currencies;
- exchange between one or more forms of VDA;
- transfer of VDAs;
- safekeeping or administration of VDAs or instruments enabling control over them; and
- financial services related to an issuer's offer or sale of a VDA.
Accordingly, an Indian VDA investigation can involve extensive compliance records that go considerably beyond a simple wallet address.
What Exchange KYC Can Reveal
Current FIU-IND guidance requires robust client due diligence by covered VDA reporting entities.
Depending upon the transaction and platform, records may include:
- name;
- PAN;
- identity documents;
- address;
- mobile number;
- email address;
- bank account details;
- device information;
- IP address with timestamp;
- geolocation;
- device ID;
- VDA wallet addresses;
- transaction hashes;
- client-risk profile;
- transaction-monitoring alerts;
- suspicious transaction information; and
- other onboarding or due-diligence material.
This can become extremely important in an extradition case because an investigator may use exchange KYC to connect:
PERSON
↓
EXCHANGE ACCOUNT
↓
DEVICE / IP
↓
WALLET
↓
TRANSACTION
↓
FOREIGN WALLET OR EXCHANGE
But each link must still be examined carefully.
KYC Attribution Is Important — But It Is Not Always Conclusive Wallet Attribution
A central mistake in crypto investigations is treating every address associated with an exchange account as though exclusive personal control has automatically been proved.
The defence should ask:
- Was the wallet hosted or unhosted?
- Was it custodial or self-custodial?
- Who controlled the private key?
- Was multi-signature approval required?
- Was the wallet corporate?
- Was it an omnibus exchange wallet?
- Was API access enabled?
- Was a trading bot used?
- Did multiple employees have credentials?
- Was the device compromised?
- Did someone else have seed-phrase access?
- Was a hardware wallet involved?
- Was the wallet address only a deposit address assigned by an exchange?
Blockchain visibility is not the same thing as identifying the human actor behind every transaction.
Hosted Wallet vs Unhosted Wallet
This distinction can become especially important in VDA investigations.
Hosted Wallet
A hosted or custodial wallet may be controlled through a VDA service provider that can potentially maintain:
- KYC;
- transaction history;
- login records;
- device data;
- withdrawal records;
- counterparty information; and
- compliance alerts.
Unhosted Wallet
An unhosted or self-custodial wallet may not have an intermediary holding equivalent customer-identification records.
FIU guidance treats transfers to or from unhosted wallets as presenting higher AML risk because one side of the transaction may not be hosted by an obligated service provider.
The evidentiary question then shifts toward:
- private-key control;
- device evidence;
- seed phrase;
- transaction pattern;
- exchange off-ramp;
- communications;
- IP information;
- counterparty records; and
- other attribution evidence.
The Travel Rule and Cross-Border VDA Transfers
AML requirements applicable to regulated VDA transfers increasingly focus upon maintaining originator and beneficiary information through the transfer chain.
For investigators, this can create another potential evidentiary layer.
A cross-border VDA transfer may therefore generate:
- originator information;
- beneficiary information;
- sending VDA service provider records;
- receiving VDA service provider records;
- transaction hash;
- wallet address;
- date and time;
- value;
- network;
- screening information; and
- compliance alerts.
However, information recorded for AML purposes must still be linked properly to the criminal allegation before it becomes evidence of culpability.
Wallet Tracing: What Blockchain Analytics Can and Cannot Prove
Blockchain analytics can be powerful.
Depending upon the network, analysts may trace:
- transaction hashes;
- wallet-to-wallet movement;
- token transfers;
- timing;
- value movement;
- exchange deposit clusters;
- exchange withdrawal clusters;
- bridges;
- cross-chain activity;
- smart-contract interaction;
- DeFi activity;
- high-risk counterparties;
- mixing patterns;
- rapid layering; and
- possible off-ramp points.
But blockchain analytics normally identifies transactional relationships, patterns or clusters.
It does not automatically establish:
- the natural person controlling every wallet;
- criminal intention;
- knowledge of source of funds;
- ownership of all assets in a cluster;
- whether a transaction was authorised;
- whether credentials were compromised; or
- whether an exchange-controlled wallet should be treated as the personal wallet of one customer.
The Attribution Triangle: Wallet + Device + Exchange
A stronger crypto attribution case often attempts to connect three categories of evidence.
WALLET DATA
+
DEVICE / NETWORK DATA
+
EXCHANGE / KYC DATA
=
ATTRIBUTION THEORY
For example:
- exchange account registered to the accused;
- login from a particular device;
- withdrawal to a wallet;
- same wallet interacting with alleged investor funds;
- subsequent transfer to another exchange;
- off-ramp into a bank account;
- communications concerning the transaction.
The defence should test each link independently.
Investor Fraud: The Wallet Trail Is Only One Part of the Case
A crypto-investment fraud case may involve allegations concerning:
- guaranteed returns;
- false staking returns;
- fake mining schemes;
- fabricated exchange volume;
- misrepresentation of reserves;
- fake token utility;
- false partnerships;
- withdrawal restrictions;
- misappropriation of customer assets;
- undisclosed related-party transfers;
- personal use of investor funds;
- token-price manipulation; or
- exit fraud.
The extradition case must therefore analyse not only where the crypto moved but also:
- what representation was made;
- who made it;
- when money was obtained;
- what the investor understood;
- what happened to the funds;
- what contractual documents existed;
- whether business failure is being alleged as criminal fraud; and
- whether dishonest intention is alleged from inception or inferred later.
Business Failure vs Criminal Fraud
Not every collapsed token, failed exchange or unsuccessful VDA business is necessarily criminal fraud.
A sophisticated defence should examine:
- business plan;
- white paper;
- investor agreements;
- risk disclosures;
- market conditions;
- treasury movements;
- operational expenditure;
- liquidity crisis;
- hacking incidents;
- custodial failures;
- counterparty defaults;
- management decisions;
- communications with investors; and
- whether alleged dishonesty existed when funds were obtained.
Extradition should be defended on the actual criminal allegations and supporting evidence—not simply on the fact that investors suffered losses.
Red Notice: The Person-Location Track
Where a crypto-fraud accused resides abroad, investigators may seek international wanted-person cooperation if the legal requirements are satisfied.
An INTERPOL Red Notice is a request to law-enforcement authorities worldwide to locate and provisionally arrest a wanted person pending extradition, surrender or similar legal action.
It is not an international arrest warrant.
The country where the person is found determines the legal effect of the Red Notice under its own law.
The usual person-focused sequence may involve:
CRYPTO / VDA CRIMINAL CASE
↓
INDIAN WARRANT / NBW
↓
RED NOTICE / DIFFUSION
↓
LOCATION ABROAD
↓
FOREIGN ARREST RISK
↓
FORMAL EXTRADITION
Red Notice Does Not Prove Formal Extradition Has Begun
A family may hear that “INTERPOL has been activated” and assume that a complete extradition request has already reached the foreign government.
That is not necessarily correct.
Counsel should separately verify:
- FIR status;
- charge-sheet status;
- Indian warrant;
- NBW;
- Red Notice;
- Red Diffusion;
- foreign arrest;
- provisional-arrest request;
- MEA extradition dossier;
- treaty transmission;
- foreign extradition case number; and
- foreign appeal status.
Formal Extradition: MEA / CPV and the Crypto Evidence
The Ministry of External Affairs is India's Central Authority for extradition, with CPV Division acting as the nodal division.
The formal extradition dossier generally requires a coherent narrative establishing the alleged case against the specific person sought.
For a crypto case, important evidence may include:
- FIR;
- charge-sheet;
- arrest warrant;
- investor statements;
- exchange records;
- bank records;
- wallet records;
- blockchain analysis;
- device extraction;
- communications;
- company records;
- transaction charts;
- foreign remittance evidence;
- identity material;
- applicable criminal provisions; and
- evidence showing that the person sought is the person connected with the warrant.
MEA guidance also requires certified transcripts where electronic recordings or media files are relied upon as part of the dossier.
Extradition Threshold: “Crypto Fraud” Is Not a Treaty Offence Label
The phrase “crypto fraud” does not itself determine extraditability.
The lawyer must identify the actual Indian offences alleged.
Depending upon the facts, allegations may involve:
- cheating;
- criminal breach of trust;
- criminal conspiracy;
- forgery;
- cyber offences;
- identity-related offences;
- fraudulent investment activity;
- money laundering; or
- other statutory offences.
The applicable extradition treaty or arrangement must then be examined for:
- dual criminality;
- minimum punishment;
- evidentiary requirements;
- limitation;
- political-offence restrictions where relevant;
- speciality;
- nationality issues;
- human-rights restrictions under Requested-State law; and
- other refusal grounds.
Dual Criminality in Crypto and VDA Cases
The Requested State may not use the expression “Virtual Digital Asset” or classify offences in the same way as India.
The extradition analysis generally focuses upon the alleged underlying conduct.
For example:
| Indian Allegation | Foreign-Law Conduct Comparison May Examine |
|---|---|
| Investor deception | Fraud / obtaining property by deception |
| Misappropriation of customer crypto | Theft / breach of trust / fraud |
| False exchange platform | Fraud / computer misuse / financial offence |
| Layering of alleged proceeds | Money laundering |
| Unauthorised wallet access | Computer misuse / theft / fraud |
| Identity misuse | Identity fraud / computer offence |
Identical section numbers are not required; what matters is the applicable treaty test and criminal character of the conduct.
Silver Notice: The Crypto Asset-Tracing Track
INTERPOL's Silver Notice and Silver Diffusion framework is particularly relevant to financial investigations involving cross-border assets.
INTERPOL has expressly identified cryptocurrency among the asset categories that may be traced through the Silver initiative.
Under the current pilot, the Silver mechanism can assist countries in:
- locating assets;
- identifying assets;
- obtaining asset information; and
- monitoring assets.
For crypto cases, potential targets may include:
- exchange accounts;
- custodial wallets;
- cryptocurrency holdings;
- companies;
- bank accounts;
- real estate purchased with alleged crypto proceeds;
- investment accounts;
- other property allegedly acquired from VDA proceeds; and
- beneficial ownership interests.
Silver Notice Is Not a Crypto Freezing Order
This distinction is fundamental.
Silver Notice and Silver Diffusion measures operate principally as international asset-tracing and information-sharing tools.
Therefore:
SILVER NOTICE
≠
WALLET FREEZE

SILVER NOTICE
≠
EXCHANGE FREEZING ORDER

SILVER NOTICE
≠
CONFISCATION ORDER

SILVER NOTICE
≠
TRANSFER OF CRYPTO TO INDIA
Once an asset is located, coercive action ordinarily requires separate lawful steps through the jurisdiction controlling the exchange, custodian, company, bank or other property.
Red + Silver in the Same Crypto Case
A serious cross-border cryptocurrency investigation may therefore have both tracks operating simultaneously.
PERSON
↓
RED NOTICE / DIFFUSION
↓
FOREIGN LOCATION
↓
EXTRADITION

AT THE SAME TIME

CRYPTO / ASSETS
↓
SILVER NOTICE / DIFFUSION
↓
EXCHANGE / WALLET / PROPERTY INFORMATION
↓
FORMAL FOREIGN RESTRAINT
↓
CONFISCATION / RECOVERY
INTERPOL has itself highlighted the operational usefulness of combining Silver asset tracing with Red Notice fugitive-location work in appropriate cases.
The legal defences nevertheless remain different.
Foreign Exchange Records: One of the Most Important Evidence Sources
Where crypto is transferred to an exchange outside India, the foreign platform may potentially hold evidence concerning:
- customer KYC;
- passport;
- residential address;
- email;
- mobile number;
- device information;
- IP logs;
- deposit addresses;
- withdrawal addresses;
- transaction history;
- bank-account links;
- fiat withdrawals;
- compliance alerts;
- account freezes;
- sub-accounts;
- API access;
- business accounts; and
- beneficial-owner information.
But the route by which Indian investigators obtain and use those records may matter.
Counsel should determine whether the material came through:
- voluntary exchange cooperation;
- foreign police assistance;
- INTERPOL channels;
- MLAT;
- letters of request;
- foreign court order;
- regulatory cooperation; or
- another lawful process.
Investigative Intelligence vs Admissible Evidence
International crypto investigations often begin with intelligence.
For example, foreign authorities may identify:
- an account;
- a wallet;
- a customer;
- an IP address;
- a company;
- a crypto exchange; or
- a suspected beneficial owner.
But later prosecution or extradition proceedings may require properly authenticated and legally usable material.
The lawyer should therefore ask:
- Who generated the record?
- How was it obtained?
- Is it intelligence or evidence?
- Has it been authenticated?
- Is an exchange certificate available?
- Are server logs preserved?
- Is the blockchain report reproducible?
- Who prepared the analytics?
- What methodology was used?
- Is the methodology disclosed?
- Does foreign law require further certification?
Chain of Custody for Wallet and Device Evidence
Where a prosecution relies upon hardware wallets, phones, laptops or seed phrases, digital chain of custody becomes critical.
Review:
- date of seizure;
- seizing authority;
- device identifier;
- hash values;
- forensic image;
- extraction process;
- wallet software;
- key material;
- seed phrase;
- password recovery;
- transaction-signing evidence;
- time synchronization;
- storage conditions;
- access log; and
- forensic expert methodology.
The presence of a wallet application on a phone is not necessarily equivalent to proof that the device owner authorised every blockchain transaction associated with a particular address.
Crypto Mixers, Bridges and Privacy Tools
Investigators may treat certain transaction patterns as indicators of attempted concealment.
These can include:
- mixing services;
- rapid movement across wallets;
- chain hopping;
- cross-chain bridges;
- privacy-focused assets;
- DeFi swaps;
- multiple exchange accounts;
- unhosted wallets;
- OTC conversions; and
- rapid conversion to fiat.
But the legal analysis should distinguish:
PRIVACY OR COMPLEXITY
from
PROOF OF CRIMINAL INTENT.
The prosecution must still establish the relevant mens rea and criminal nexus.
What If the Wallet Was a Corporate Treasury Wallet?
Crypto businesses frequently use:
- corporate treasury wallets;
- multi-signature wallets;
- exchange omnibus wallets;
- customer deposit wallets;
- hot wallets;
- cold wallets;
- settlement wallets; and
- smart-contract-controlled assets.
For each wallet, counsel should identify:
- legal owner;
- beneficial owner;
- authorised signers;
- signature threshold;
- policy for withdrawals;
- who initiated the transfer;
- who approved it;
- who received the asset; and
- whether customer funds were segregated.
A founder should not automatically be treated as the sole controller merely because the wallet belonged to the company.
What If the Exchange Account Was Corporate?
A corporate VDA account may involve:
- company KYC;
- directors;
- authorised users;
- beneficial owners;
- API credentials;
- trading permissions;
- withdrawal permissions;
- whitelisted wallet addresses;
- bank accounts; and
- internal compliance records.
The defence should identify the person who actually controlled the transaction relevant to the allegation.
PMLA and Crypto/VDA Investigations
Virtual Digital Asset-related services have been brought within India's AML reporting framework.
Separately, a particular accused may face PMLA consequences only where the statutory requirements of the PMLA are independently satisfied.
Where applicable, an investigation may involve:
- scheduled offence;
- alleged proceeds of crime;
- ED investigation;
- Section 50 summons;
- bank freezing;
- crypto asset freezing;
- provisional attachment;
- Adjudicating Authority proceedings;
- prosecution complaint;
- Special Court proceedings;
- foreign assets; and
- confiscation.
The fact that an exchange is a PMLA reporting entity does not itself mean that every customer transaction constitutes money laundering.
Source of Funds: Essential in Crypto Asset Defence
Where investigators allege that crypto represents criminal proceeds, counsel should reconstruct how each asset was acquired.
Potential legitimate sources may include:
- early crypto purchase;
- mining;
- staking;
- trading profits;
- salary;
- consulting income;
- token allocation;
- founder allocation;
- venture investment;
- loan;
- sale of property;
- business income;
- inheritance;
- airdrop;
- DeFi yield; or
- other lawful receipts.
The defence should match:
ACQUISITION DATE
+
ACQUISITION VALUE
+
SOURCE OF FUNDS
+
WALLET HISTORY
+
EXCHANGE RECORD
+
BANK RECORD
against the alleged criminal period.
Equivalent-Value Property
Indian proceeds-of-crime litigation can also raise questions concerning property equivalent in value where alleged proceeds are held abroad or cannot be directly recovered under the asserted statutory theory.
This makes it important to classify each asset as:
- alleged direct proceeds;
- alleged indirect proceeds;
- converted proceeds;
- equivalent-value property;
- legitimate property; or
- third-party property.
A wallet or bank account should never be described merely as “attached property” without identifying the legal theory supporting the action.
Third-Party Crypto and Investor Assets
Crypto investigations can affect assets belonging to persons who are not accused.
These can include:
- customers;
- investors;
- lenders;
- liquidity providers;
- employees;
- shareholders;
- business partners;
- custody clients;
- family members; and
- independent companies.
Where funds are held in pooled wallets or omnibus accounts, identifying beneficial entitlement can become extremely complex.
The legal team should therefore separate:
WHO CONTROLLED THE WALLET?
from
WHO BENEFICIALLY OWNED THE CRYPTO?
International Asset Recovery After the Crypto Is Found
Locating cryptocurrency does not complete recovery.
The next question is:
WHO HAS LEGAL OR TECHNICAL CONTROL OVER THE ASSET?
If the crypto is held with a foreign exchange, investigators may seek action through that jurisdiction.
If the asset remains in a self-custodial wallet, practical recovery may depend on:
- private-key access;
- device seizure;
- seed phrase;
- custodian cooperation;
- court orders;
- foreign restraint;
- later exchange deposits; or
- other lawful enforcement mechanisms.
Thus:
TRACE
≠
CONTROL

CONTROL
≠
LEGAL OWNERSHIP

LEGAL OWNERSHIP
≠
CONFISCABILITY
Red Notice + Silver Notice + PMLA: Three Different Processes
| Process | Primary Objective |
|---|---|
| Red Notice / Diffusion | Locate wanted person and seek provisional-arrest cooperation |
| Silver Notice / Diffusion | Trace and identify alleged criminal assets |
| PMLA proceedings | Indian money-laundering and proceeds-of-crime process where statutory conditions apply |
The same factual transaction may appear in all three files, but each process has its own jurisdiction, legal test and remedy.
Domestic NBW and LOC Still Matter
A crypto founder or trader living abroad may focus only on INTERPOL while overlooking Indian domestic restraints.
Separate issues may include:
- court summons;
- BW;
- NBW;
- proclamation;
- LOC;
- passport action;
- bail conditions;
- ED summons; and
- trial-court appearance requirements.
Therefore:
RED NOTICE DELETION
≠
NBW RECALL

RED NOTICE DELETION
≠
LOC CANCELLATION

SILVER NOTICE ISSUE
≠
PMLA ATTACHMENT

EXTRADITION RELIEF
≠
ASSET RELEASE
CCF and INTERPOL Data
Where personal data is processed through INTERPOL's systems, the Commission for the Control of INTERPOL's Files may become relevant for access, correction or deletion requests within its applicable jurisdiction.
Potential issues may include:
- accuracy;
- identity;
- continuing validity of the warrant;
- purpose;
- criminal nature of the case;
- quality of data;
- Article 3 issues;
- procedural developments; and
- other compliance questions under INTERPOL's framework.
However, CCF proceedings do not substitute for:
- Indian bail;
- NBW recall;
- FIR quashing;
- PMLA litigation;
- LOC challenge;
- foreign extradition defence;
- foreign exchange-freezing proceedings; or
- asset-confiscation litigation.
Crypto/VDA Extradition Master Matrix
CRYPTO / VDA EXTRADITION CASE MATRIX

CLIENT:
____________________________________

CURRENT COUNTRY:
____________________________________

BUSINESS / PROJECT:
____________________________________

ALLEGED FRAUD TYPE:
____________________________________

INDIAN FIR / CBI RC:
____________________________________

POLICE / CBI UNIT:
____________________________________

CHARGE-SHEET:
YES / NO / UNKNOWN

ALLEGED ROLE:
FOUNDER / DIRECTOR / TRADER / DEVELOPER /
PROMOTER / WALLET CONTROLLER / BENEFICIARY / OTHER

COURT SUMMONS:
____________________________________

BW / NBW:
____________________________________

PROCLAMATION:
____________________________________

LOC:
____________________________________

PASSPORT ACTION:
____________________________________

RED NOTICE:
YES / NO / UNKNOWN

RED DIFFUSION:
YES / NO / UNKNOWN

FOREIGN ARREST:
____________________________________

PROVISIONAL ARREST REQUEST:
YES / NO / UNKNOWN

MEA EXTRADITION DOSSIER:
PREPARING / SENT / UNKNOWN

APPLICABLE TREATY:
____________________________________

FOREIGN COUNSEL:
____________________________________

EXCHANGE ACCOUNTS:
____________________________________

EXCHANGE JURISDICTIONS:
____________________________________

KYC HOLDER:
____________________________________

WALLETS:
____________________________________

HOSTED / UNHOSTED:
____________________________________

PRIVATE KEY CONTROL:
____________________________________

MULTISIG:
____________________________________

DEVICE / IP EVIDENCE:
____________________________________

TRANSACTION HASHES:
____________________________________

BLOCKCHAIN ANALYTICS:
____________________________________

BANK OFF-RAMP:
____________________________________

CRYPTO ASSET VALUE:
____________________________________

SOURCE OF FUNDS:
____________________________________

ED / ECIR:
____________________________________

PMLA ATTACHMENT:
____________________________________

SILVER NOTICE:
YES / NO / UNKNOWN

SILVER DIFFUSION:
YES / NO / UNKNOWN

FOREIGN FREEZE:
____________________________________

FOREIGN ASSET-RECOVERY PROCEEDING:
____________________________________

THIRD-PARTY CLAIMS:
____________________________________

NEXT DEADLINE:
____________________________________
Crypto Extradition and Asset-Tracing Flowchart
Core principle: Wallet tracing may establish movement of digital assets, but extradition requires a case against the person. Red Notice and extradition pursue the person; Silver Notice and foreign asset-recovery procedures pursue information and property.Documents Required for a Crypto/VDA Extradition Review
- FIR;
- complaint;
- CBI RC;
- charge-sheet;
- court summons;
- BW / NBW;
- proclamation orders;
- bail orders;
- quashing proceedings;
- company incorporation documents;
- shareholding records;
- beneficial-ownership records;
- white paper;
- token documents;
- investor agreements;
- exchange KYC;
- exchange statements;
- deposit history;
- withdrawal history;
- IP logs;
- device IDs;
- transaction hashes;
- wallet addresses;
- private-key / multisig information lawfully available;
- blockchain analytics reports;
- bank records;
- fiat off-ramp records;
- cryptocurrency purchase records;
- source-of-funds documents;
- ED / PMLA documents where applicable;
- Red Notice / Diffusion information;
- CCF correspondence;
- Silver Notice / Diffusion information lawfully available;
- formal extradition request;
- MEA / CPV correspondence lawfully available;
- foreign arrest papers;
- foreign bail orders;
- foreign exchange freezing records;
- foreign confiscation proceedings;
- applicable extradition treaty; and
- one consolidated wallet + evidence + extradition chronology.
Common Mistakes in Crypto and VDA Extradition Cases
- Assuming a blockchain address automatically identifies a person.
- Assuming KYC ownership proves exclusive wallet control.
- Ignoring corporate or multisig wallets.
- Confusing an exchange deposit address with a self-custodial wallet.
- Ignoring API access.
- Ignoring compromised credentials.
- Treating every fund movement as money laundering.
- Assuming every investor loss proves fraud.
- Ignoring legitimate source-of-funds evidence.
- Ignoring the date on which assets were acquired.
- Failing to distinguish direct proceeds from equivalent-value property.
- Calling a Red Notice an international arrest warrant.
- Calling a Silver Notice a freezing order.
- Assuming a Red Notice proves that formal extradition has begun.
- Failing to identify the actual treaty.
- Ignoring the Indian NBW.
- Ignoring LOC or passport proceedings.
- Assuming FIU reporting obligations automatically prove customer criminal liability.
- Failing to distinguish investigative intelligence from authenticated evidence.
- Ignoring foreign exchange and foreign-court procedures.
- Failing to coordinate Indian counsel with foreign extradition and asset-recovery counsel.
Searching for the “Best Extradition Lawyer India Crypto”: What Should Be Evaluated?
The expressions “best extradition lawyer India crypto”, “top INTERPOL lawyer India cryptocurrency”, “specialized VDA extradition lawyer India” and “crypto asset recovery lawyer India” are common search-intent phrases, not official legal rankings or certifications.
For a high-stakes VDA case, a client may instead evaluate whether counsel can:
- understand the underlying Indian criminal case;
- read wallet and exchange records intelligently;
- distinguish hosted from unhosted wallets;
- analyse multisig and corporate control;
- understand blockchain attribution limits;
- analyse exchange KYC and device information;
- analyse FIU-IND VDA reporting obligations;
- separate AML compliance records from proof of criminal guilt;
- analyse the bank off-ramp;
- analyse source of funds;
- distinguish investor loss from fraudulent intention;
- analyse Red Notice and Diffusion exposure;
- analyse Silver Notice / Silver Diffusion asset tracing;
- review PMLA exposure;
- identify NBW / LOC / passport consequences;
- read the applicable extradition treaty;
- review the MEA extradition dossier;
- coordinate foreign exchanges and foreign counsel; and
- maintain one coherent person + wallet + asset chronology.
Frequently Asked Questions
1. Can India seek extradition for an alleged cryptocurrency fraud?
Potentially yes, where the alleged conduct constitutes an extraditable offence under the applicable legal framework and the procedural, warrant, evidentiary and treaty requirements are satisfied.
2. Does owning a crypto wallet prove criminal liability?
No. Ownership or control of a wallet can be relevant evidence, but the prosecution must establish the relevant criminal conduct, knowledge and intent.
3. Can exchange KYC connect a wallet to a person?
It can provide important attribution evidence, particularly when combined with transaction, device, IP and withdrawal records, but the complete factual context should be examined.
4. What is an unhosted wallet?
It generally refers to a self-custodial wallet not held by a VDA service provider that performs customer-account functions equivalent to a hosted wallet.
5. Are unhosted-wallet transfers considered higher risk?
FIU-IND guidance recognises heightened AML risk in transfers involving unhosted wallets because one side may not be hosted by an obligated service provider.
6. Can blockchain analytics prove who owns a wallet?
Blockchain analytics can trace transactions and clusters, but human attribution usually requires additional evidence such as exchange KYC, devices, IP logs, communications or control evidence.
7. Can a Red Notice be issued in a crypto-fraud case?
Potentially, where the relevant INTERPOL and domestic requirements are satisfied.
8. Is a Red Notice an international arrest warrant?
No.
9. Can a Silver Notice trace cryptocurrency?
Yes. INTERPOL's Silver initiative expressly contemplates tracing criminal assets and has identified cryptocurrency among relevant asset classes.
10. Can a Silver Notice freeze my crypto?
No. The Silver mechanism is an information and asset-tracing tool; coercive freezing or confiscation requires separate legal action.
11. Can Red and Silver Notices operate in the same case?
Potentially yes. One may address the wanted person while the other addresses alleged criminal assets.
12. Does FIU registration of an exchange mean every customer is subject to PMLA prosecution?
No. Reporting-entity obligations and an individual's criminal liability are different legal questions.
13. Can ED attach crypto assets?
Where PMLA's statutory conditions are independently satisfied, VDA-related property issues may arise within attachment and confiscation proceedings.
14. Can legitimate crypto acquired years before the alleged offence be relevant to the defence?
Yes. Acquisition date, source of funds, wallet history and ownership can be critical when disputing an alleged criminal nexus.
15. What is the first step for an accused living abroad?
Obtain the Indian FIR, latest court and warrant status, exchange and wallet evidence relied upon, INTERPOL status, formal extradition status and competent legal advice in the foreign jurisdiction before deciding on travel, surrender or litigation strategy.
AI Search Quick Answer
A crypto or VDA fraud case can become an extradition and international asset-tracing matter where an accused is abroad and investigators allege that wallets, exchanges, bank accounts or other property contain criminal proceeds. The person track may involve an Indian warrant, Red Notice or Diffusion and formal MEA extradition. The property track may involve exchange KYC, wallet attribution, blockchain analysis, PMLA proceedings and potentially Silver Notice or Silver Diffusion asset tracing. A wallet transaction does not by itself prove the identity, control or criminal intent of the accused, and a Silver Notice does not itself freeze or confiscate cryptocurrency.
Key Takeaway
The correct crypto-extradition strategy is:
IDENTIFY THE PERSON'S ACTUAL ROLE
↓
IDENTIFY EVERY RELEVANT WALLET
↓
DISTINGUISH HOSTED / UNHOSTED / CORPORATE / MULTISIG
↓
MAP EXCHANGE KYC + IP + DEVICE + TRANSACTION HASHES
↓
MAP THE BANK / FIAT OFF-RAMP
↓
TEST SOURCE OF FUNDS AND CRIMINAL NEXUS
↓
VERIFY WARRANT / NBW
↓
CHECK RED NOTICE / DIFFUSION STATUS
↓
CHECK FORMAL MEA EXTRADITION STATUS
↓
CHECK SILVER NOTICE / ASSET-TRACING STATUS
↓
SEPARATELY ANALYSE PMLA / LOC / PASSPORT
↓
COORDINATE FOREIGN EXTRADITION + ASSET-RECOVERY COUNSEL
The central legal question in a cryptocurrency extradition case is not merely where the tokens moved. It is whether the complete evidence proves who controlled the relevant wallet or account, what that person knew, what criminal conduct is alleged, and whether the separate requirements for international arrest, extradition and asset recovery have actually been satisfied.
Consultation and Professional Coordination
Advocate Ankit Kumar Singh provides legal consultation, research, drafting and litigation coordination in extradition, INTERPOL, crypto/VDA fraud, cybercrime, PMLA/ED, international asset tracing, Look Out Circulars and connected cross-border financial-crime matters.
A crypto-extradition review may require preparation of a wallet-attribution chart, exchange-KYC matrix, blockchain transaction chronology, bank off-ramp analysis, source-of-funds review, Indian warrant history, Red Notice / Diffusion analysis, Silver Notice asset-tracing assessment, PMLA review and formal extradition-status matrix.
Where the client is abroad or a relevant exchange, custodian, wallet service, company or asset is located abroad, appropriately qualified foreign counsel may be required for arrest, bail, extradition, disclosure, exchange orders, restraint, confiscation or asset-recovery proceedings under that jurisdiction's law.
Technical blockchain analytics may also require competent forensic or specialist assistance. Legal conclusions should not be based solely upon an unexplained wallet-clustering report.
Consultation, drafting, filing, appearance and professional coordination remain subject to accepted engagement, jurisdiction and the actual case record.
No advocate can guarantee Red Notice deletion, non-arrest, refusal of extradition, crypto release, PMLA relief, LOC cancellation, wallet unfreezing, recovery of assets or any particular judicial, governmental or INTERPOL result.
Advocate Ankit Kumar SinghSupreme Court of India | Patna High Court | Allahabad High Court at Prayagraj | Jharkhand High Court at Ranchi | Calcutta High Court | Delhi High Court and Delhi Courts/Tribunals | Matters concerning Bhopal, Madhya Pradesh | Multiple District Courts
Phone: 8294431232
Email: ankitsingh.legum@gmail.com
Website: advocateankitkumarsingh.in
Official and Authoritative Sources
- Financial Intelligence Unit - India — AML/CFT/CPF Guidelines for Reporting Entities Providing Services Related to Virtual Digital Assets, updated January 2026.
- Financial Intelligence Unit - India — Registration and compliance framework for Virtual Digital Asset Service Providers.
- The Prevention of Money-Laundering Act, 2002 and applicable Prevention of Money-Laundering Rules.
- INTERPOL — Red Notice framework.
- INTERPOL — Silver Notice / Silver Diffusion pilot and current international asset-tracing framework.
- INTERPOL — current Silver Notice impact material concerning international asset tracing, including cryptocurrency and other criminal assets.
- Ministry of External Affairs, Government of India — Extradition Guidelines.
- The Extradition Act, 1962.
- The applicable extradition treaty or arrangement with the Requested State.
- Applicable foreign laws governing cryptocurrency exchanges, disclosure, provisional arrest, extradition, freezing, confiscation and asset recovery.
Verification note: Cryptocurrency technology, VDA regulation, INTERPOL's Silver framework and foreign exchange-compliance rules continue to evolve. The current FIU-IND guidance, applicable PMLA framework, INTERPOL rules, extradition treaty, foreign law and case-specific records should be verified before taking legal action.
Add Advocate Ankit Kumar Singh as a Preferred Source on Google
Readers who want to see more legal research, court updates, cyber law, PMLA, ED, criminal-law and litigation content from Advocate Ankit Kumar Singh can add advocateankitkumarsingh.in as a Preferred Source on Google.
Add advocateankitkumarsingh.in as a Preferred Source on Google
Conclusion
Crypto and VDA investigations create an unusually complex intersection between technology, criminal law, financial regulation and international cooperation.
A single case may involve:
- Indian FIR;
- CBI investigation;
- ED / PMLA;
- wallet tracing;
- exchange KYC;
- IP and device evidence;
- bank off-ramps;
- unhosted wallets;
- foreign exchanges;
- Red Notice or Diffusion;
- Silver Notice or Silver Diffusion;
- MEA extradition;
- foreign arrest;
- foreign crypto freezing; and
- overseas asset-recovery proceedings.
The correct defence should therefore avoid one-dimensional conclusions.
An address visible on a blockchain is not necessarily proof of human ownership.
An exchange account is not necessarily proof that the KYC holder personally executed every transfer.
An investor loss is not automatically proof of fraudulent intention.
A Red Notice is not an international arrest warrant.
A Silver Notice is not a freezing order.
A PMLA reporting obligation imposed on a VDA service provider does not itself establish customer criminal liability.
The strongest crypto-extradition strategy combines forensic transaction analysis with conventional criminal-law fundamentals: identity, role, control, knowledge, intent, source of funds, warrant validity, treaty requirements and proof linking the specific accused to the alleged offence.
Disclaimer: This article provides general legal information and research only and does not constitute case-specific legal, financial or technical advice. References to “best”, “top” or “specialized” reflect common search terminology and are not official professional rankings or certifications. Cryptocurrency/VDA regulation, PMLA, INTERPOL, extradition, asset tracing and foreign freezing proceedings operate under distinct legal frameworks and should be reviewed on the actual records of each matter.